
Is Umios (TSE:1333) Cheap After Its Rebrand Or Does Cash Flow Say Otherwise?
Umios (TSE:1333) has drawn investor attention after its recent rebranding from Maruha Nichiro Corporation in March 2026, prompting fresh scrutiny of the seafood and processed food group’s share performance and long term return profile.
Recent trading has been choppy for Umios, with the share price slipping 1.03% on the day and edging lower year to date. However, a 3.61% 90 day share price return and 16.55% 1 year total shareholder return hint that longer term momentum has been stronger than the latest pullback suggests.
Scan how Umios compares with other food related stocks that have recently caught market attention by reviewing the 74 high quality undiscovered gems.
Umios has just rebranded and the share price has cooled after a strong 1 year run. Do you lean into the pullback now, or wait for a clearer margin of safety in the valuation work that follows?
Price to earnings check on Umios: Is the discount justified?
On simple earnings math, Umios screens as cheap. The stock trades on a P/E of 10.1x, which is below both the wider JP market on 14.1x and the JP Food industry on 17.2x, even after the pullback to ¥1,292.5.
The P/E ratio compares the current share price with net profit per share. For a mature food and processing group like Umios, it is a common shorthand for how much investors are paying for current earnings power in a sector where growth trends can be steady rather than rapid.
That low multiple sits beside some mixed profit trends. Earnings over the past 5 years grew at 9.2% per year, yet the most recent year showed a decline of 17.7% and net profit margins moved from 2.1% to 1.7%. Return on equity of 8.4% is also described as low, and recent results were affected by a large one off gain of ¥8.4b, which makes headline profit quality harder to read.
Relative to food peers, the valuation gap is clear. A P/E of 10.1x versus a sector average of 17.2x suggests the market is assigning a sizeable discount to Umios compared with other JP Food stocks. There is no P/E fair ratio available for this ticker, so there is no regression based anchor for where that multiple could trend if sentiment or fundamentals shift.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.1x (UNDERVALUED).
Still, that low P/E only tells part of the story, as softer net profit margins and the impact of one off gains could influence how investors value Umios.
Find out about the key risks to this Umios narrative.
Another view on Umios using the SWS DCF model
The SWS DCF model paints a very different picture for Umios. On this approach, the estimated future cash flow value is ¥379.88 per share, while the market price sits at ¥1,292.5. That gap suggests the stock screens as expensive on cash flows, not cheap.
For investors, this creates a clear trade off. The earnings based P/E work points to value, while the cash flow lens points to valuation risk. Which signal matters more for you at this stage of the cycle: the headline profits or the underlying cash generation that feeds them?
Look into how the SWS DCF model arrives at its fair value.
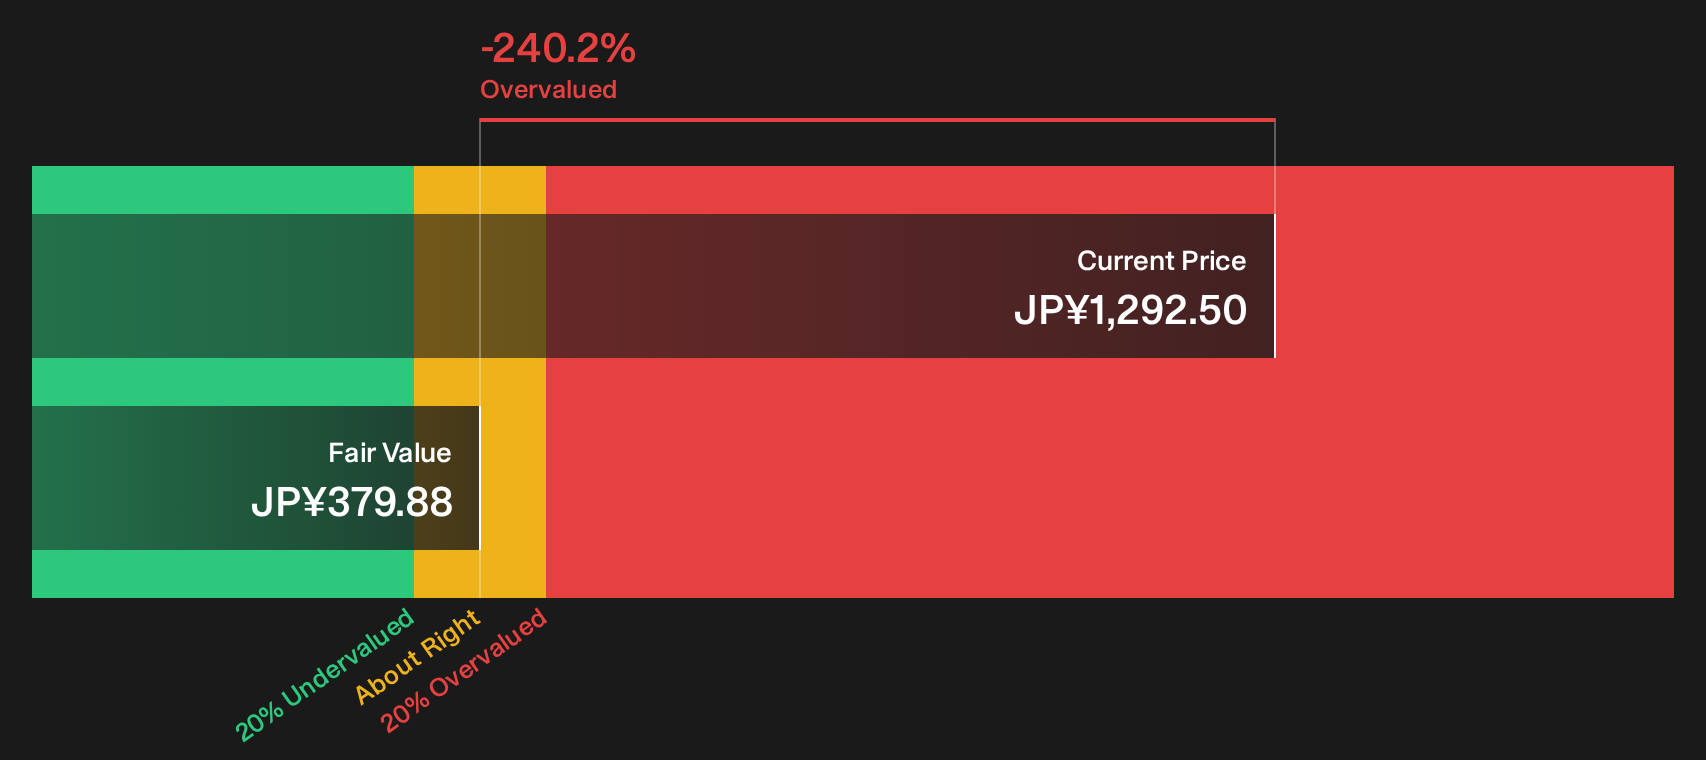
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Umios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
All of this leaves the picture on Umios finely balanced, with both risk flags and bright spots vying for attention. If you want to move fast and base your decision on more than just headline ratios, take a closer look at the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Umios?
Do not stop at Umios. Broader idea hunting can sharpen your watchlist and help you stress test whether this stock really deserves a place in your portfolio.
- Target resilient payers that prioritise consistent income by scanning the 14 dividend fortresses before the next ex dividend dates stack up.
- Hunt for quality at a sensible entry point by sorting through the 17 high quality undervalued stocks and comparing their fundamentals with what you see at Umios.
- Protect your downside first by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (20 results) so weaker businesses do not quietly drag on your returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com