
NagaCorp (SEHK:3918) Soft Earnings Raise The Question Of Whether The Stock Is Cheap
NagaCorp (SEHK:3918) has just posted half year earnings that showed softer sales and profit compared with the prior period, giving investors fresh numbers to assess the casino operator’s risk and reward trade off.
At a share price of HK$3.18, NagaCorp has seen a 1-day share price return of 1.27% and a 7-day gain of 2.25%. However, momentum has been fading over a longer stretch, with the 30-day share price return down 9.79% and the 1-year total shareholder return declining 47.88% as investors weigh the softer half year earnings against the broader risk profile.
Spot fresh ideas alongside NagaCorp by scanning a curated 612 high quality undiscovered gems that have strong fundamentals yet remain under the radar with recent earnings shifts.NagaCorp trades well below analyst targets after a long stretch of weak shareholder returns. The market sees risk. The key valuation question is whether that caution is excessive or entirely reasonable.
Preferred P/E of 5.9x: Is it justified?
Valuation on NagaCorp today starts with a simple comparison. At a last close of HK$3.18, the stock trades on a P/E of 5.9x that sits well below several benchmarks flagged by the data.
The P/E ratio links NagaCorp's share price to its earnings per share, giving you a snapshot of how much investors are paying for each unit of profit. For casino and hospitality operators, this is a common yardstick because earnings capture both the gaming floor and hotel operations in a single figure.
Here the gap is clear. The shares trade at 5.9x earnings, while the estimated fair P/E is 9.6x, and the Hong Kong hospitality average is 13.3x. Compared with peers on 9.5x, the current multiple suggests the market is pricing in a lower earnings profile than those reference points and leaves room for sentiment to move closer to that fair ratio level if conditions support it.
Explore the SWS fair ratio for NagaCorp.
Result: Price-to-earnings of 5.9x (UNDERVALUED)
Still, the long stretch of weak multi year shareholder returns and the wide discount to analyst targets both signal that sentiment around NagaCorp could remain fragile.
Find out about the key risks to this NagaCorp narrative.
Another view on NagaCorp’s value
There is a catch. Our DCF model points to a future cash flow value of HK$1.93 per share, which sits well below NagaCorp's current HK$3.18 price and flags the stock as overvalued on that lens.
This kind of gap can reflect very different beliefs about long term cash generation, which leaves you weighing whether the market is too optimistic or the DCF inputs are too strict. Look into how the SWS DCF model arrives at its fair value.
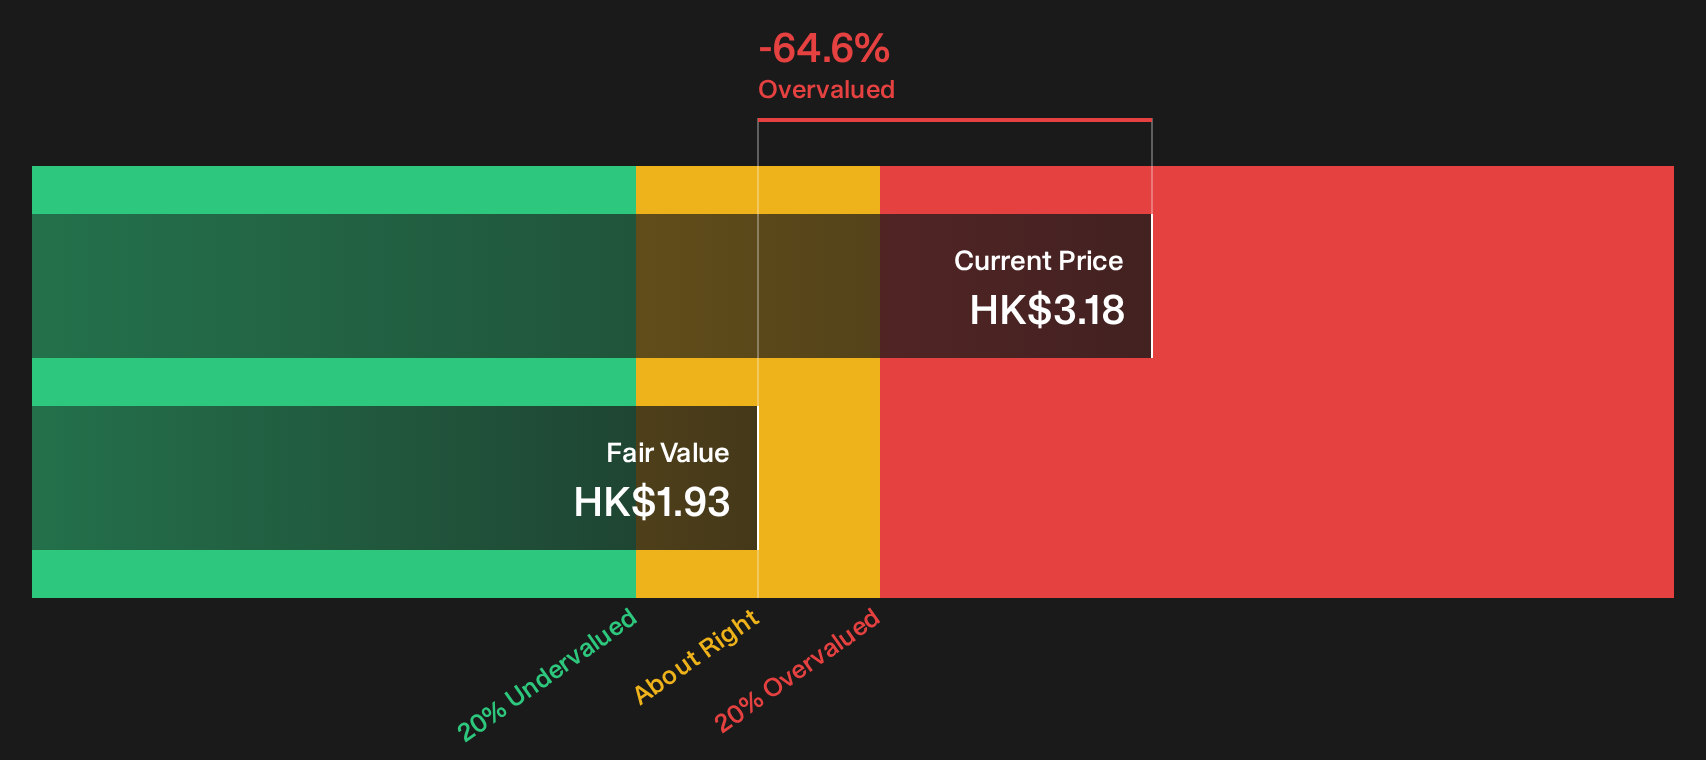
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NagaCorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
NagaCorp inspires mixed reactions, with some investors focused on risks while others see clear upsides and potential rewards. If you want to move quickly and shape your own view based on both sides of that debate, start by reviewing the detailed breakdown of 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond NagaCorp?
If NagaCorp has sharpened your focus on valuation and risk, do not stop here. Broader ideas can help you stress test your thinking and spot fresh opportunities.
- Target quality at a discount by scanning a curated set of 179 high quality undervalued stocks that pair strong fundamentals with prices that lag the underlying numbers.
- Prioritise resilience by zeroing in on companies from a list of solid balance sheet and fundamentals (197 results) where financial strength supports staying power through different market conditions.
- Reduce portfolio stress by reviewing a 227 resilient stocks with low risk scores that highlights businesses with calmer price moves and fewer financial red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com