
Should Earnings Revisions Require Action From ScanSource Stock Investors?
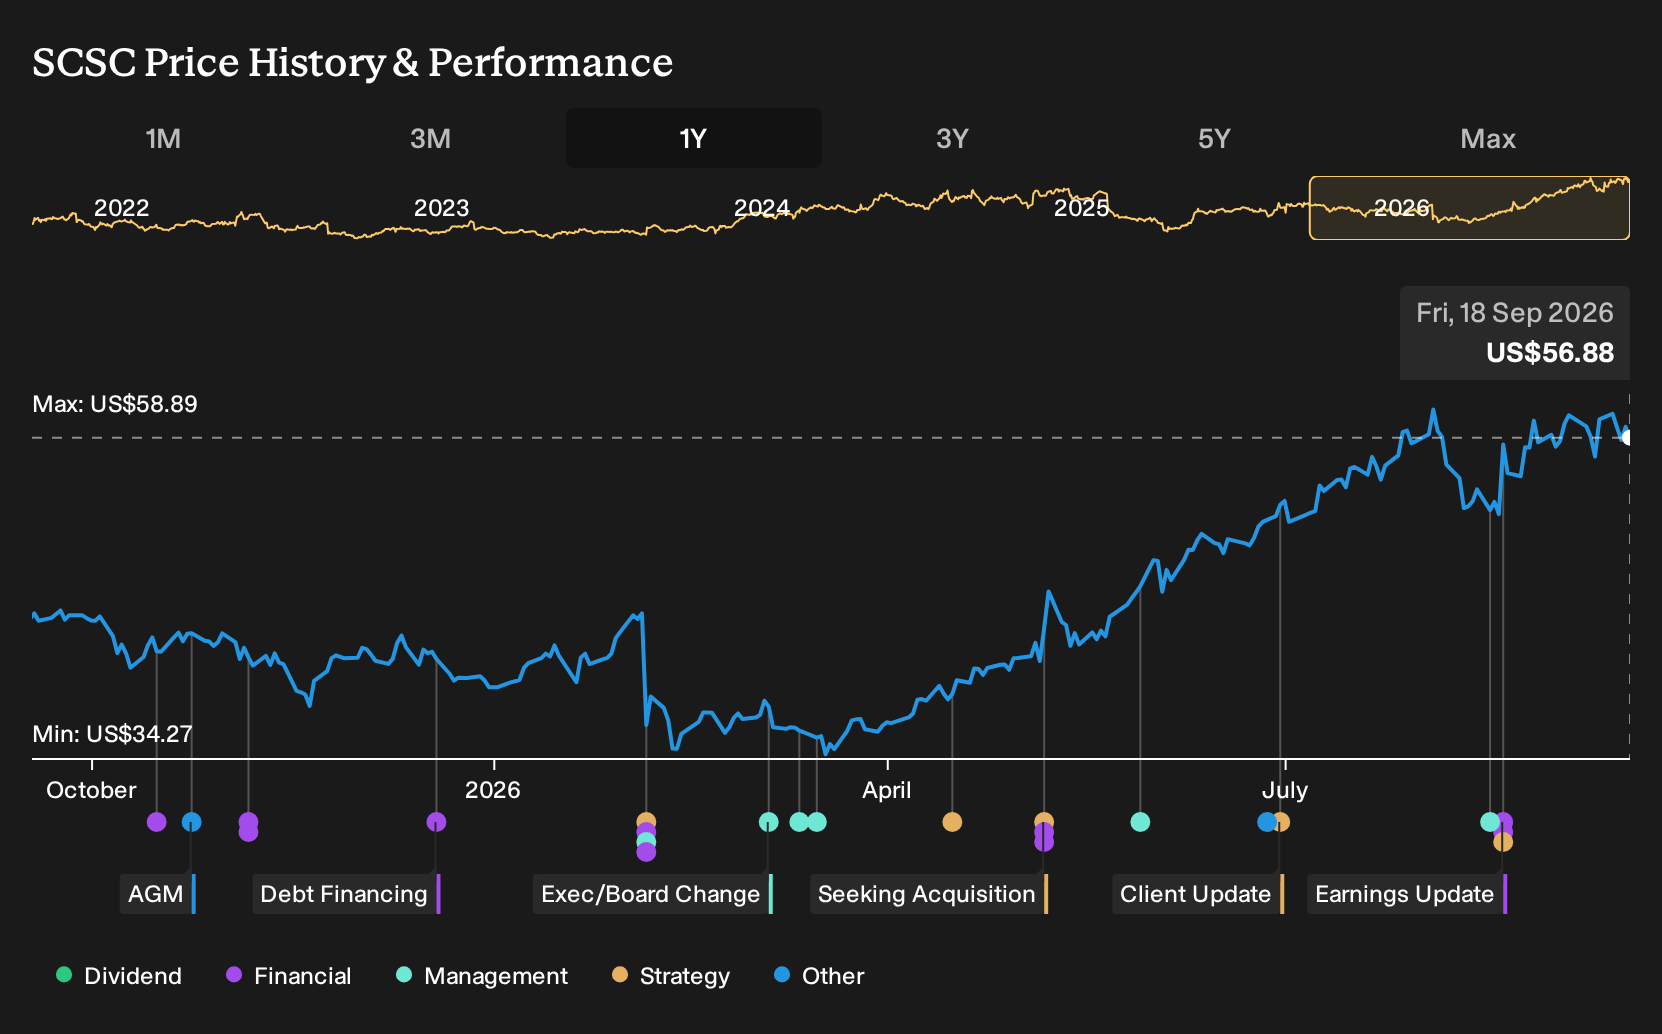
- ScanSource is attracting fresh attention after a period of strong price momentum that aligns with cash flow based valuation work and a focus on recurring technology and communications solutions for channel partners.
- The combination of upward earnings estimate revisions, a Momentum Score of B and a valuation below a discounted cash flow fair value estimate is drawing interest to how efficiently ScanSource converts its operating position into long term cash generation.
- This article explores how ScanSource's price momentum intersects with its recurring revenue focused investment narrative and what that may indicate for investors.
Scan recent momentum in ScanSource and then compare it with other cash flow focused opportunities on our hand picked 33 high quality undervalued stocks list.
ScanSource Investment Narrative Recap
To own ScanSource, you need to believe that demand for cloud, connectivity, CX and physical security will continue to support a richer mix of recurring and services-led gross profit. The key near-term catalyst is continued execution on this mix shift and converting that operating position into consistent free cash flow. Recent share price momentum does not materially change that thesis.
The biggest risk right now is execution. Integration of acquisitions like MicroAge, winning share in higher growth technologies and managing hardware cycles all have to work together. Any stumble here, combined with significant recent insider selling, could make the recent share price run more fragile.
The most relevant piece of recent information for this momentum story is that ScanSource is trading below a discounted cash flow estimate of US$66.30 while also carrying a P/E of 14.5x versus an estimated fair P/E of 21.9x and a higher industry multiple. That frames the current price action against cash flow expectations rather than headlines.
In addition, ScanSource currently has a P/S of 0.35 and a Momentum Score of B backed by upward earnings revisions. This creates a clear tension between recent performance and valuation. The operational catalysts still come from recurring revenue growth, MicroAge integration and Intelisys connectivity demand, while risks include slower-than-market revenue growth and the need to keep margins and returns moving in the right direction.
What ScanSource's Analyst Assumptions Really Say
ScanSource's narrative projects US$4.0b revenue and US$111.0m earnings by 2029. That path builds on analysts assuming 7.8% yearly revenue growth and an earnings increase of about US$32.1m from US$78.9m today.
Uncover why ScanSource's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For ScanSource, the alternate narrative centers on acquisition risk rather than execution upside. The most optimistic analysts were already modeling about US$4.3b of revenue and US$115.7m of earnings by 2029 before this latest price move. That outlook could prove aggressive if consolidation and digital direct sales reshape the story. You should treat that bullish setup as one of several competing viewpoints that may shift as the impact of the recent momentum becomes clearer.
Explore 3 other ScanSource fair value estimates, including one that suggests as much as 37% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ScanSource research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ScanSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ScanSource's overall financial health at a glance.
Looking For More Investment Ideas Beyond ScanSource?
If ScanSource has sharpened your focus on cash flow, valuation and risk, it can be useful to line it up against other opportunities that share some of those traits but with different business models and capital structures.
- For investors who care about resilience first and upside second, scan through a 30 resilient stocks with low risk scores that aims to keep surprises to a minimum.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (23 results) that prioritizes financial flexibility and staying power.
- When you want potential mispricing backed by fundamentals, filter through a 33 high quality undervalued stocks that highlights companies where cash flows and valuation sit out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com