
Will Marine Corps Security Rollout Change Honeywell Stock Narrative
- Honeywell International unit Honeywell Technologies completed a modernized LenelS2 OnGuard access control rollout for U.S. Marine Corps barracks, supporting Barracks 2030 with centralized management for more than 70,000 locks and compliance with Department of Defense cybersecurity standards.
- The Marine Corps reports around 80% lower labor costs and about 60% lower material costs versus legacy approaches, illustrating how Honeywell International’s access control platform can materially reshape security operating budgets for large, complex facilities.
- Next, the focus shifts to how Honeywell International’s investment narrative could be affected by this large scale, cost saving Marine Corps deployment.
Honeywell International Investment Narrative Recap
For Honeywell International, the big picture to assess is an industrial group leaning harder into software, automation and complex infrastructure projects, while also planning a split into three separate companies. The Marine Corps access control win reinforces Honeywell’s role in critical, security focused systems, but on its own it does not change the near term earnings outlook.
The short term swing factor still centers on execution of the breakup plan, acquisition integration and demand across Industrial and Building Automation. Key risks remain the forecast declines in revenue and earnings, the reliance on higher risk funding and debt that current operating cash flow does not comfortably cover.
The Marine Corps LenelS2 OnGuard rollout ties most directly into Honeywell International’s Building Automation operations, where access control, cybersecurity and software heavy platforms are important. That program shows the business competing for complex, multi site deployments that can support the thesis around automation and security as longer term demand drivers for the group.
Investors still need to weigh that against analyst expectations for declining revenue and profit over the next three years and the execution risk around separating into Automation, Aerospace and Advanced Materials entities. The contract underlines Honeywell’s operational relevance in secure infrastructure but does not remove concerns about earnings pressure, integration costs or balance sheet flexibility.
Honeywell International's narrative projects US$22.5b revenue and US$3.2b earnings by 2029. This reflects a forecast yearly revenue decline of 16.1% and an earnings decrease of US$5.1b from current earnings of US$8.3b.
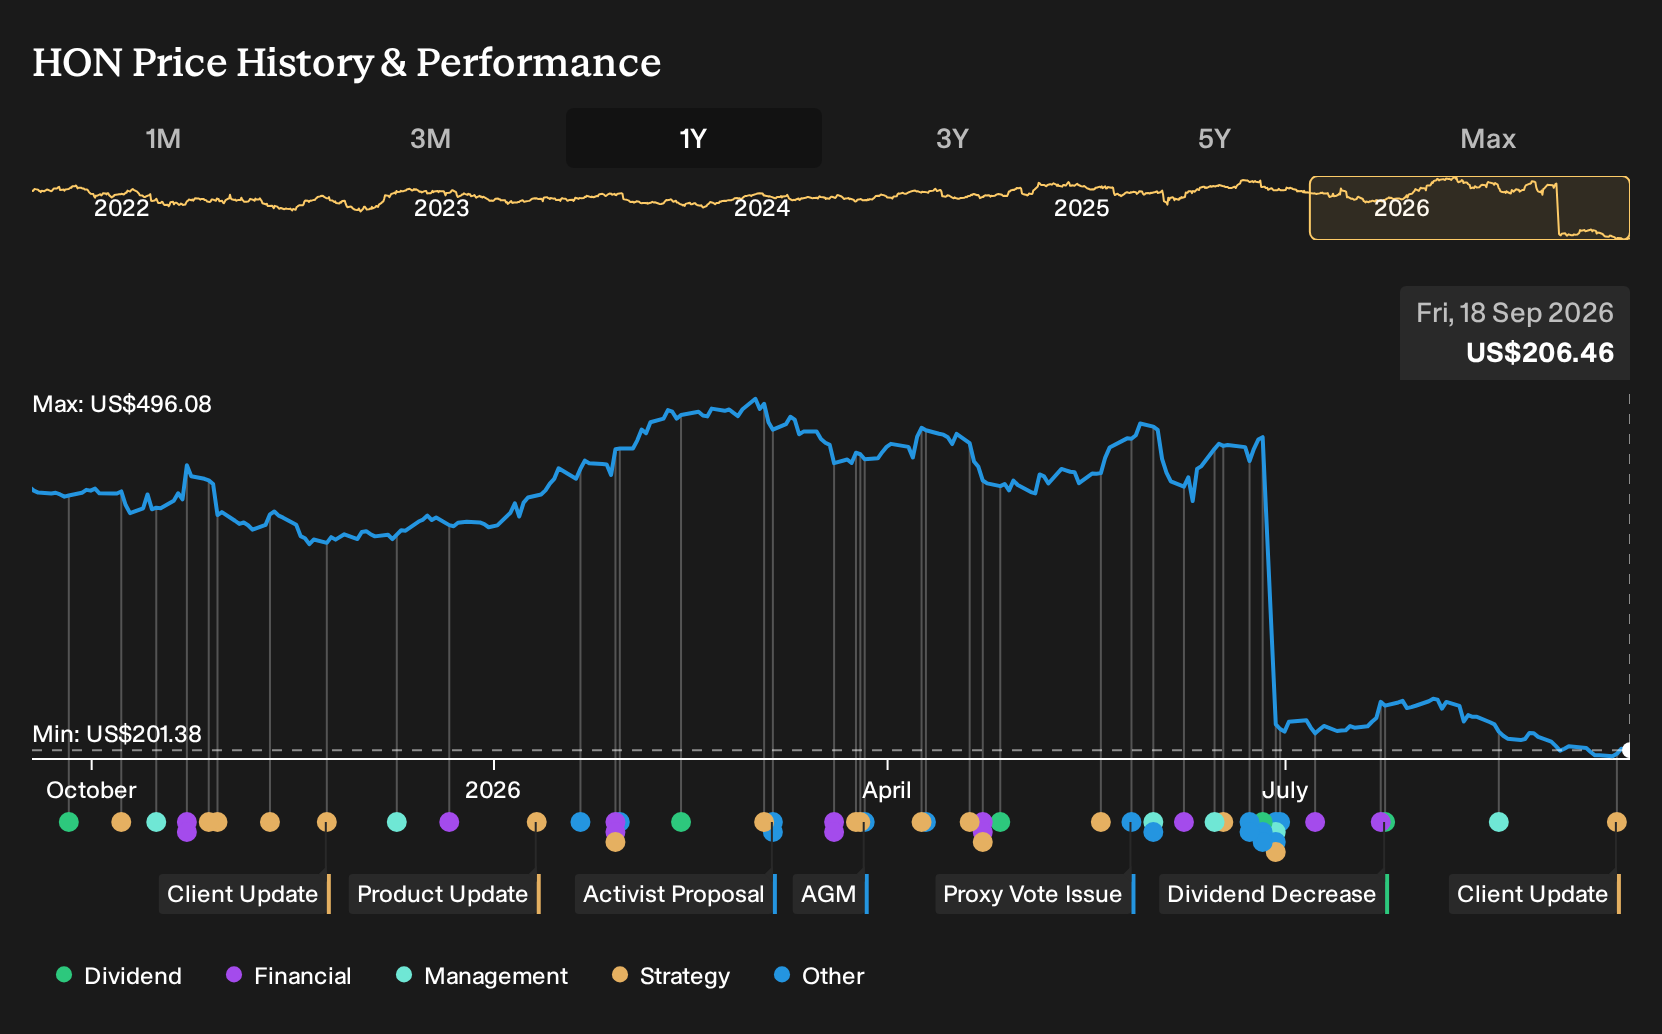
Uncover why Honeywell International's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Honeywell International as a beneficiary of building automation and energy efficiency, with forecasts around US$21.3b revenue and US$3.1b earnings by 2029. You can now ask whether this Marine Corps access control win strengthens that upbeat view or nudges expectations even higher over time.
Explore 10 other Honeywell International fair value estimates, including one that suggests up to 55% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Honeywell International research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Honeywell International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Honeywell International's overall financial health at a glance.
Looking For More Ideas Beyond Honeywell International?
If this Honeywell International story has you thinking about where else automation, cost control and balance sheet strength might matter, the Simply Wall St Screener can help you widen the field without losing focus on quality.
- For investors who want income to feel more predictable, review 6 dividend fortresses that lean on substantial cash payouts to shareholders.
- If capital preservation ranks high on your list, scan 30 resilient stocks with low risk scores that pair steadier risk profiles with more measured return potential.
- When you are hunting for underfollowed opportunities with solid fundamentals, filter for 16 high quality undiscovered gems that may not yet be crowded with attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com