
Is Raised Guidance Altering The Investment Case For Thermo Fisher Stock (TMO)?
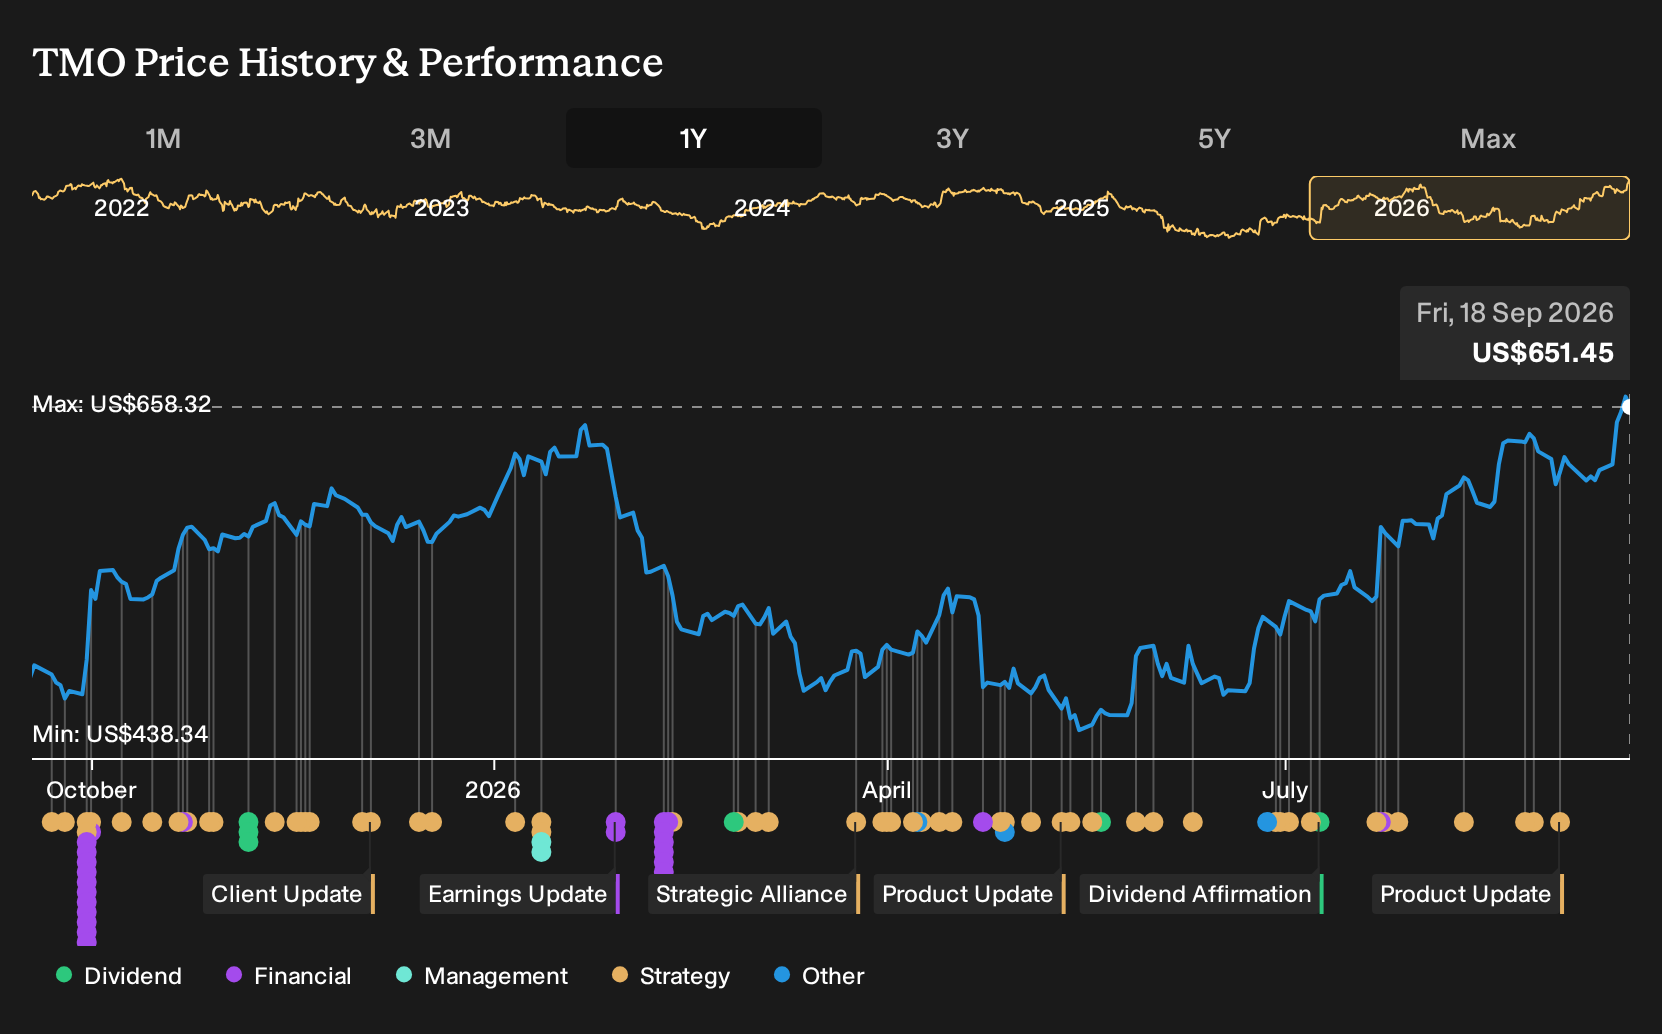
- Thermo Fisher Scientific recently raised its 2026 revenue and adjusted EPS outlook after reporting 5% organic growth and 13% adjusted EPS growth in the second quarter, supported by stronger pharma and biotech demand.
- The newly formed Precure collaboration with Mayo Clinic aims to combine proteomic, genomic, and clinical data for early disease detection, which deepens Thermo Fisher Scientific's role in large scale healthcare data generation.
- This article examines how Thermo Fisher Scientific's raised outlook shapes the investment narrative and what it might mean for future returns.
Thermo Fisher Scientific Investment Narrative Recap
To own Thermo Fisher Scientific, you need to believe the pharma and biotech recovery, plus demand across lab services, can offset weak pockets like academic and government funding and pressure in China. The raised 2026 outlook leans on that view. The near term swing factor is whether improving orders in bioproduction and clinical research keep translating into steady organic growth.
The main risk right now sits in external headwinds that Thermo Fisher Scientific cannot easily control. Tariffs, FX and policy shifts still weigh on analytical instruments margins, while high debt and leadership transition add execution risk. The latest guidance lift helps confidence, but it does not fully remove those constraints.
The Precure venture with Mayo Clinic looks like the most meaningful recent announcement for this setup. It ties Thermo Fisher Scientific’s instruments and reagents into a large multi omic data effort for early disease detection. That aligns squarely with pharma, biotech and clinical research customers that drive the current demand recovery story.
For you as a shareholder, Precure matters less as a headline partnership and more as a test of execution on complex, data heavy collaborations. If Thermo Fisher Scientific can show that its tools, software and services become embedded in these workflows, it strengthens the recurring element of the business. If projects like this stall, it would raise questions about how repeatable that catalyst really is.
Thermo Fisher Scientific Analyst Expectations in Context
Thermo Fisher Scientific's narrative projects US$54.8b revenue and US$10.0b earnings by 2029. Based on current analyst models, that path assumes revenue expands by 5.8% per year and earnings rise about US$3.0b from US$7.0b today.
Uncover why Thermo Fisher Scientific's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate angle on Thermo Fisher Scientific focuses on acquisition risk. The most optimistic analysts were already banking on revenue near US$56.6b and earnings of about US$10.4b by 2029, before this outlook hike and Precure news. That is a much richer story than consensus. Use this gap as a prompt to explore multiple viewpoints.
Explore 3 other Thermo Fisher Scientific fair value estimates, including one that indicates up to 12% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking For More Ideas Beyond Thermo Fisher Scientific?
If the Thermo Fisher Scientific story has you thinking about what else might fit your watchlist, the Simply Wall St Screener can help you quickly sift through the wider market using the same kind of fundamentals driven lens.
- For investors who want potential mispricings with quality behind them, start with a focused group of 33 high quality undervalued stocks that already screen well on both earnings power and balance sheet strength.
- If stability matters more than excitement, narrow your search to a curated pool of 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- When you are hunting for earlier stage opportunities with room to grow, broaden your research with a 8 elite penny stocks with strong financials that already show stronger financials than the typical micro cap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com