
Are Stronger Earnings Altering The Investment Case For KeyCorp Stock (KEY)?
- KeyCorp reported second quarter 2026 earnings with a 26% year-over-year rise, supported by commercial loan growth, a wider net interest margin, $340 million of share repurchases, and the planned acquisition of Clearwater UK, alongside higher full year guidance.
- The combination of stronger profitability metrics, active capital returns, and an expansion of its middle market advisory franchise provides additional detail on how KeyCorp is seeking to build a more diversified earnings mix.
- We will now look at how KeyCorp's investment narrative could be affected by its stronger earnings and higher full year guidance.
Compare what KeyCorp is doing with capital and lending to a curated group of banks and financial stocks on the move in our 33 high quality undervalued stocks.
KeyCorp Investment Narrative Recap
To own KeyCorp, you need to be comfortable with a traditional regional bank that is trying to lean harder into fee income and higher quality lending. Recent quarterly results pointed to stronger commercial loan activity and a wider net interest margin, which supports the idea that the core banking engine is still doing useful work.
The near term swing factor is whether net interest income continues to benefit from repricing while funding costs and credit issues stay contained. The bigger risk is that nonperforming loans or stress capital requirements rise from here, which could constrain buybacks, dividends, or the pace of reinvestment in growth areas.
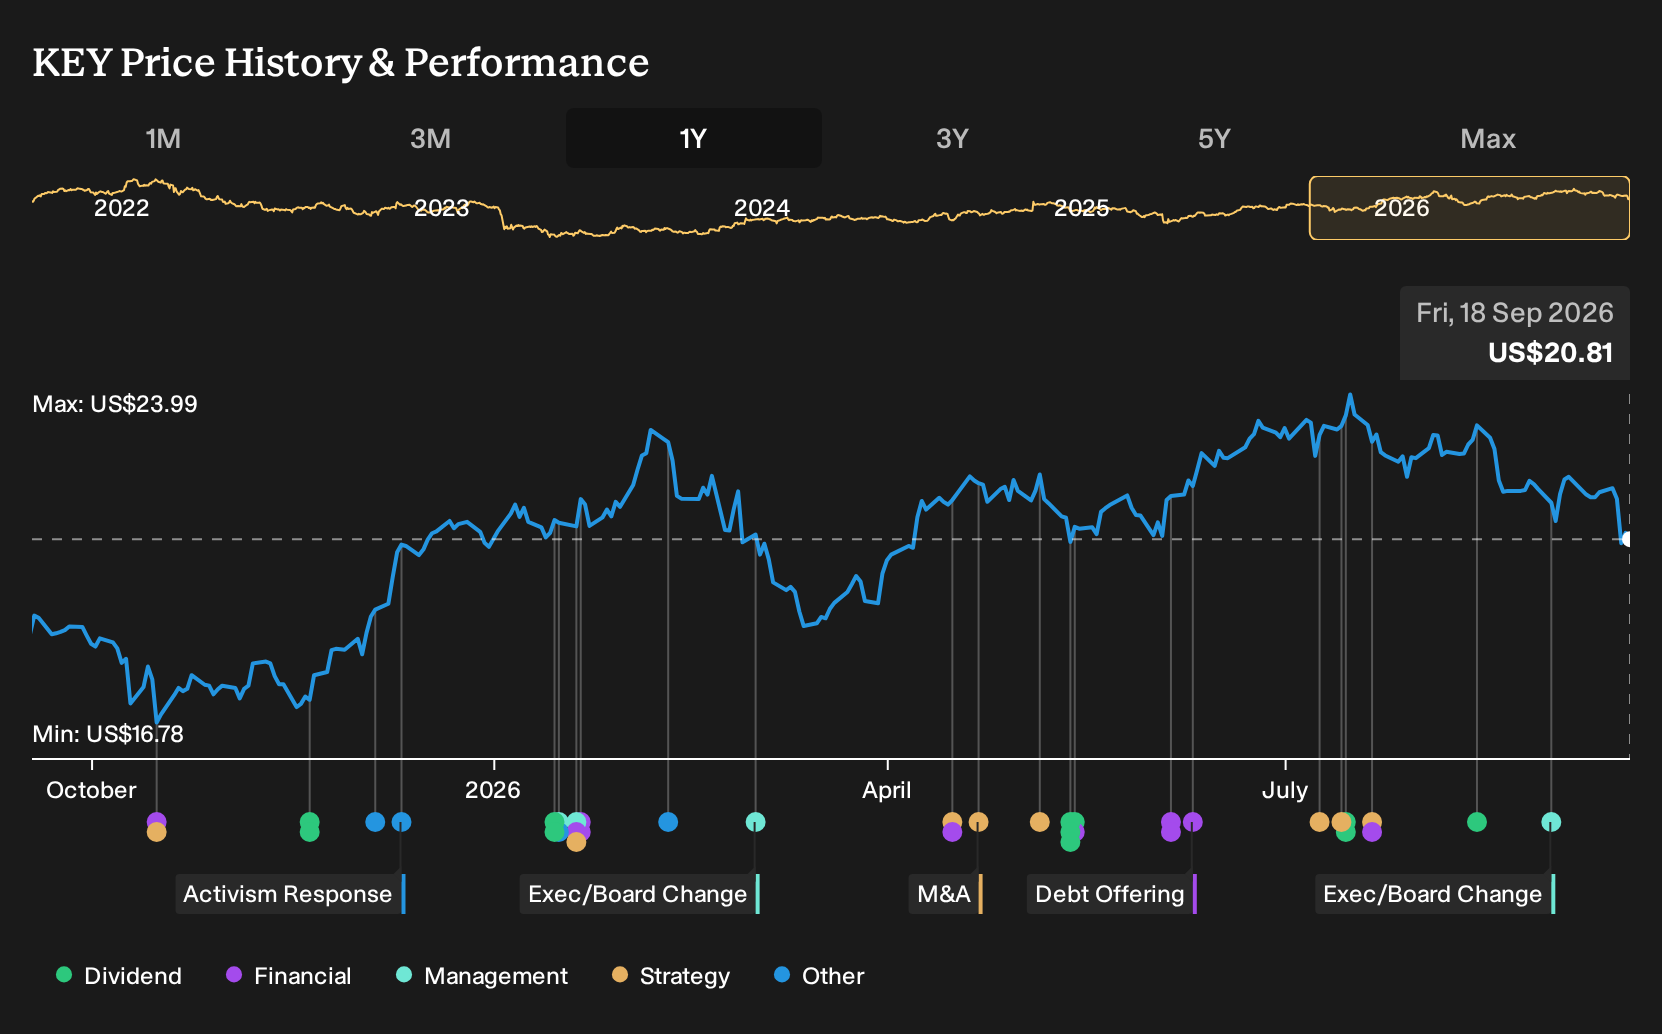
The clearest fresh data point is KeyCorp lifting its prime lending rate to 7.00% from 6.75% on September 17, 2026. That change affects many floating rate loans and credit products, which can support interest income if borrower performance holds up and deposit pricing does not climb just as quickly.
For potential catalysts, that prime hike sits alongside recent guidance for net interest income and revenue. Together they show management responding to the rate backdrop to support returns, while investors still have to weigh familiar issues such as loan demand, commercial real estate exposure, and potential shifts in regulatory capital buffers.
What The Current Forecasts Assume For KeyCorp
KeyCorp's analyst playbook is explicit. The group consensus ties the current story to a path where revenue grows by 8.8% a year and earnings rise from US$1.9b today to US$2.5b by 2029, helped by slightly higher profit margins and ongoing share reduction. Those same projections sit behind the idea that the stock would trade on a 12.5x P/E in that period, compared with 12.8x today and 12.1x for the wider US banks peer set. As a result, the overall thesis depends on investors being comfortable with a modest premium multiple and continued progress on profitability.
KeyCorp's narrative projects US$9.5b revenue and US$2.5b earnings by 2029. This requires 8.8% yearly revenue growth and about a US$0.6b earnings increase from US$1.9b today.
Uncover why KeyCorp's fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For a different angle on KeyCorp, focus on the cost side. The most bearish analysts worry that heavier hiring and tech spending could lock in higher expenses, especially if fee engines cool. Before this report, they were penciling in roughly US$9.2b of 2029 revenue and US$2.4b of earnings. Those views were set before the latest earnings surprise and guidance lift, so you can expect some of these pessimistic stories to evolve. Use that spread in expectations as a prompt to compare several viewpoints before you decide how this bank fits your portfolio.
Explore 2 other KeyCorp fair value estimates, including one that suggests it could be worth just $26.02!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your KeyCorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for KeyCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KeyCorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond KeyCorp?
If KeyCorp has sharpened your interest in banks and financials, it can help to line it up against other potential opportunities that match your risk profile and income goals using the Simply Wall St Screener.
- For investors who want potential value with income resilience, check out a curated set of higher yielding payers through the 6 dividend fortresses.
- If capital preservation and steadier metrics matter most to you, start with companies that score well on financial strength using the 30 resilient stocks with low risk scores.
- For those hunting for underfollowed stories with solid fundamentals, widen the search beyond KeyCorp by scanning the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com