
SpaceX (SPCX) Stock Looks Above Fair Value Despite Its 9% Run
Space Exploration Technologies has climbed sharply over the past few weeks, and the question now is whether a business this capital intensive is priced in line with the strength of its balance sheet and book value. SpaceX has become a focal point in the debate over how much investors should pay for hard assets like rockets, satellites, data centers and AI infrastructure when the story is moving this fast.
- Over the past month the stock has gained about 9.4%, which puts fresh pressure on investors to test whether that move is supported by the value of assets already on the books.
- Fresh contracts such as NASA’s recent US$946 million award for three additional crewed ISS missions may support expectations for future returns on the company’s existing launch and spacecraft infrastructure, which is a key input when you think about what the balance sheet is really worth.
- The analysts covering Space Exploration Technologies have run their own numbers. See what analysts think Space Exploration Technologies's shares could be worth.
The issue now is whether the current SpaceX share price can be squared with its book value when set against the industry average.
If you want another starting point for research alongside Space Exploration Technologies, you can apply the same book value lens across solid balance sheet and fundamentals stocks screener (23 results).
Has Space Exploration Technologies Run Too Far on Book Value?
P/B fits Space Exploration Technologies because so much of the story is tied to hard assets on the balance sheet and how investors price those against the stated equity value.
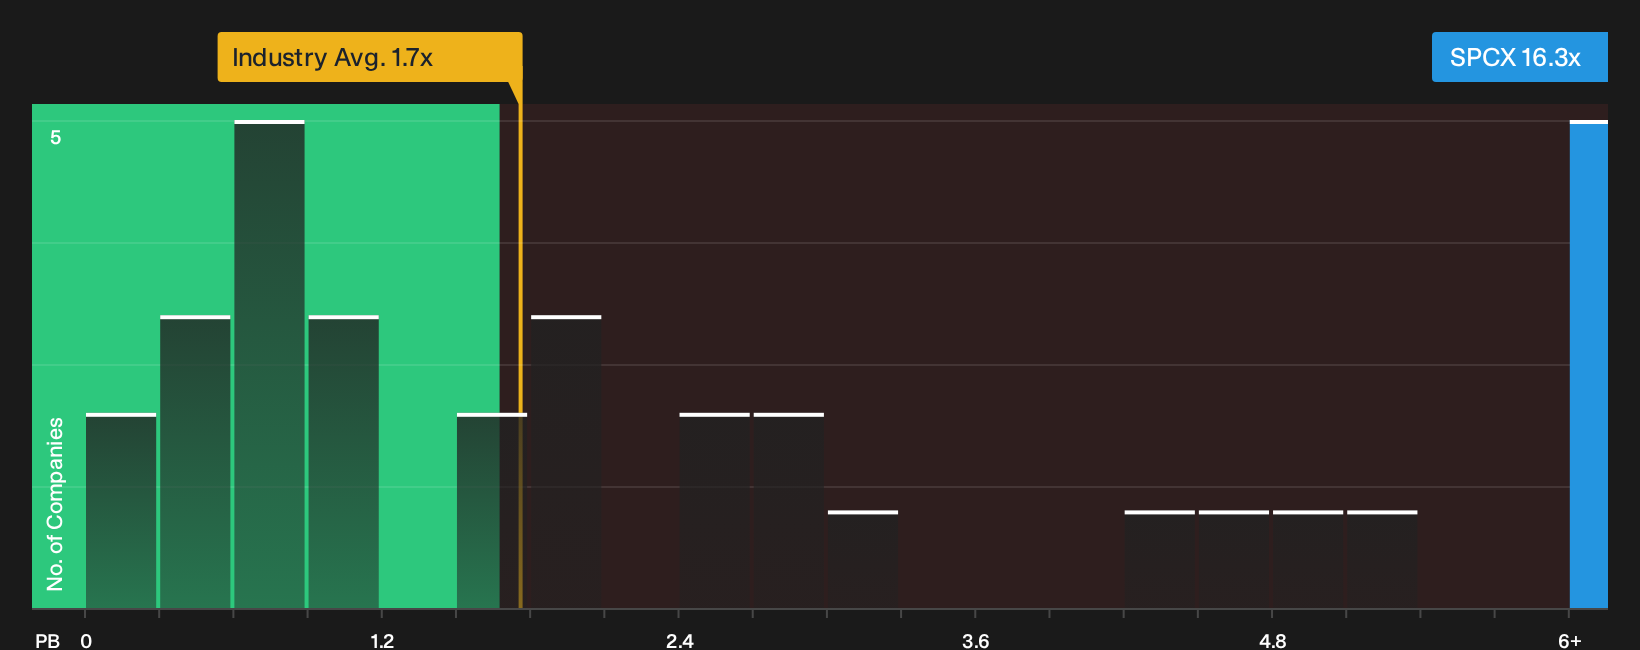
On this measure, SpaceX trades at a P/B of about 16.3x. That is far above both the broader telecom industry average of roughly 1.7x and the peer group around 14.6x, which points to a rich valuation relative to the book value already in place.
Despite the recent NASA Crew 15 to 17 contract lifting confidence in the current launch platform, the gap between SpaceX and sector norms suggests investors are paying a substantial premium for the existing asset base and whatever upside they expect it to support. Explore the numbers behind Space Exploration Technologies's P/B valuation.
The Space Exploration Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the price to book puzzle ends for Space Exploration Technologies by spelling out which expectations for future growth, profitability and earnings would need to hold for the stock to be worth significantly more or less than it is today on the market. Each Narrative sets out a fair value as a specific, testable view on Space Exploration Technologies' business so you can see how that thesis holds up over time on the Community page.
Community views on Space Exploration Technologies are split between those who see a vertically integrated AI and orbital platform taking shape and those who worry the losses and capital intensity still dominate the story.
Bull case: 31% undervalued
"Capital markets access has expanded sharply following the IPO and investment grade bond issuance, with US$85.7b of IPO proceeds, US$25b of notes and a cash and securities balance of US$100b at Q2 2026…"
Discover why this Narrative puts Space Exploration Technologies at 31% undervalued.
Bear case: 13% overvalued
"Although SpaceX’s revenue is growing steadily, the company as a whole is generating a net loss…"
Explore why this Narrative puts Space Exploration Technologies at 13% overvalued.
Space Exploration Technologies’ price is only one piece of the decision
Before you put a final view on Space Exploration Technologies, it helps to know who is steering the ship and how their pay packets push them to make choices over years, not quarters. See who runs Space Exploration Technologies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com