
Should Strong Sell Rating Require Action From Sea Stock Investors?
- Sea Limited is expected to report earnings of $1.08 per share and revenue of $8.36b for the upcoming quarter, with both figures projected above the prior year period, while its shares have recently lagged broader indexes.
- COO Gang Ye executed a pre-planned sale of 40,000 shares for about $4.2 million and still holds an estimated $2.18b stake, which underscores continued insider exposure alongside questions about whether Sea's premium P/E reflects the quality of its earnings.
- This article now examines how Sea's rich P/E multiple and strong forecasted earnings shape the investment narrative around the business.
Consider broadening your watchlist beyond Sea by scanning a curated set of stocks that combine solid earnings profiles with valuation support using the 33 high quality undervalued stocks.
Sea Investment Narrative Recap
To own Sea stock, you need to believe the business can keep turning its e commerce, gaming and fintech reach into durable earnings, not just headline growth. The most important near term catalyst is the upcoming quarter, with the market already watching the forecast US$1.08 EPS and US$8.36b in revenue as a test of execution.
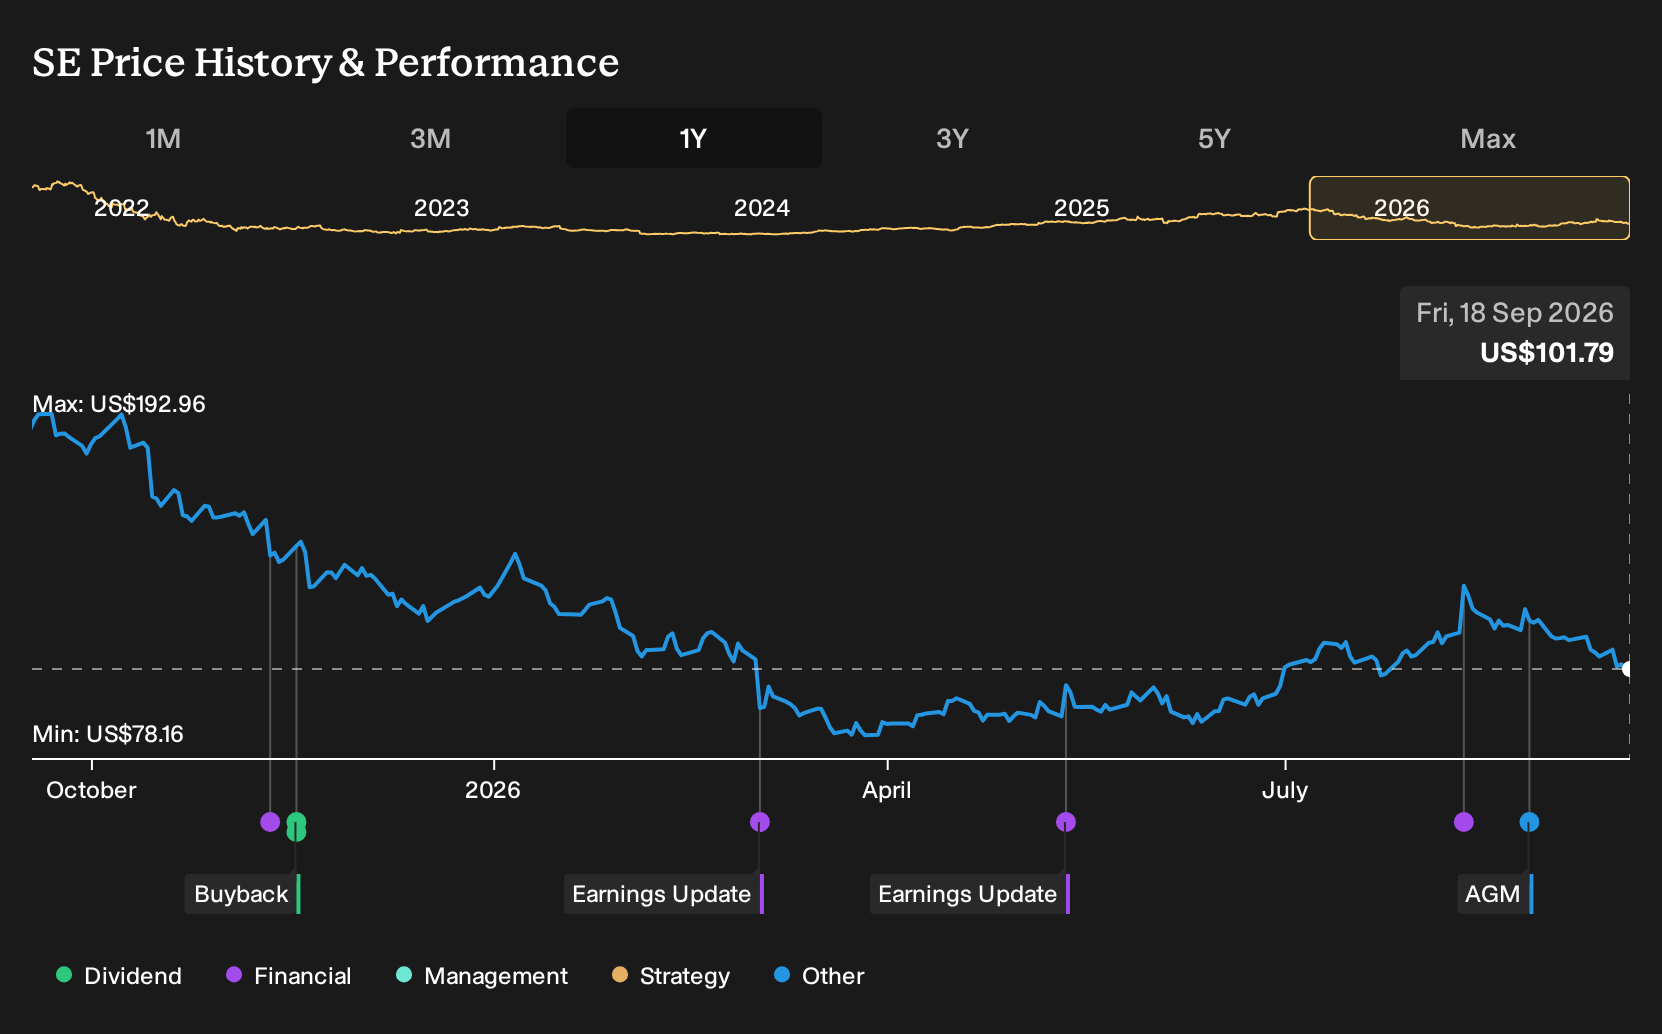
The key risk right now sits in whether Shopee and Monee can keep gaining scale while competition in Brazil and Southeast Asia stays intense. The recent share price drift and volatility look uncomfortable but do not materially change those core questions around profitability, credit quality and Garena reliance.
The recent pre planned sale of 40,000 shares by COO Gang Ye gets a lot of attention, yet the bigger operational signal is that he still holds an estimated US$2.18b stake. That level of exposure keeps management heavily aligned with how Sea performs over the next few years.
For you as a shareholder, the more relevant link to catalysts is how leadership allocates capital across Shopee, Garena and Monee while the stock trades on a premium P/E multiple. Execution on logistics, credit risk and new game content will matter far more to Sea's earnings path than this single insider transaction.
Sea's narrative projects US$47.5b revenue and US$4.1b earnings by 2029. This implies 19.7% yearly revenue growth and an earnings increase of about US$2.5b from US$1.6b today.
Uncover why Sea's fair value suggests a 54% potential upside to its current price before that gap begins to close.
Exploring Other Perspectives
One alternate view leans hard into Sea’s fintech catalyst. The most optimistic analysts were already penciling in revenue climbing to about US$50.7b and earnings of US$5.0b by 2029, before this latest earnings setup and insider sale. You can treat that as a high bar and explore how new information might shift those expectations.
Explore 5 other Sea fair value estimates, including one that suggests as much as 105% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sea research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sea's overall financial health at a glance.
Looking for more investment ideas beyond Sea?
If Sea has sharpened your focus on quality and valuation, the next step is to widen your opportunity set with a few targeted stock lists built around different risk and income profiles.
- For investors who want quality at a discount, start with a curated pool of businesses that pair robust fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- If capital preservation matters just as much as upside, consider screening for companies with more resilient profiles using the 30 resilient stocks with low risk scores.
- For those who prefer to get paid while they wait, focus on income opportunities by scanning a set of higher yielding payers through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com