
Why Trane Technologies (TT) Is Drawing Fresh Attention
Trane Technologies (TT) has drawn fresh attention after expanding Thermo King's all-electric EV series for urban cold chain transport across Asia Pacific, just as a discounted cash flow review flags potential undervaluation.
After a strong run over several years, Trane Technologies has seen momentum cool recently, with the share price falling 11.23% over the past 90 days and 5.79% over the last month. This comes even as the 3 year total shareholder return of 120.60% and 5 year total shareholder return of 149.38% point to substantial long term wealth creation.
Scan beyond Trane Technologies and see which peers also combine electrification themes with strong fundamentals using our curated list of 89 AI infrastructure stocks.
Trane Technologies now trades around $429.11, while one set of estimates clusters closer to $527 and DCF work points to smaller, yet still meaningful upside. Where does fair value really sit in that spread?
Most Popular Narrative: 18% Undervalued
Trane Technologies screens as undervalued on the most followed narrative, with a fair value estimate of $521.51 against the last close at $429.11, putting the spotlight on what might be driving that gap.
The strategic emphasis on innovation and a direct sales force enables Trane Technologies to consistently outgrow its end markets. This approach supports long-term revenue expansion and potential margin improvement due to enhanced market positioning and customer engagement.
See why 33 investors see Trane Technologies as 18% undervalued.
Result: Fair Value of $521.51 (UNDERVALUED)
Still, the bullish Trane Technologies narrative leans on continued strength in Commercial HVAC and effective price increases, both of which could be tested by weaker demand or tariff pressure.
Find out about the key risks to this Trane Technologies narrative.
Another View On Trane Technologies Valuation
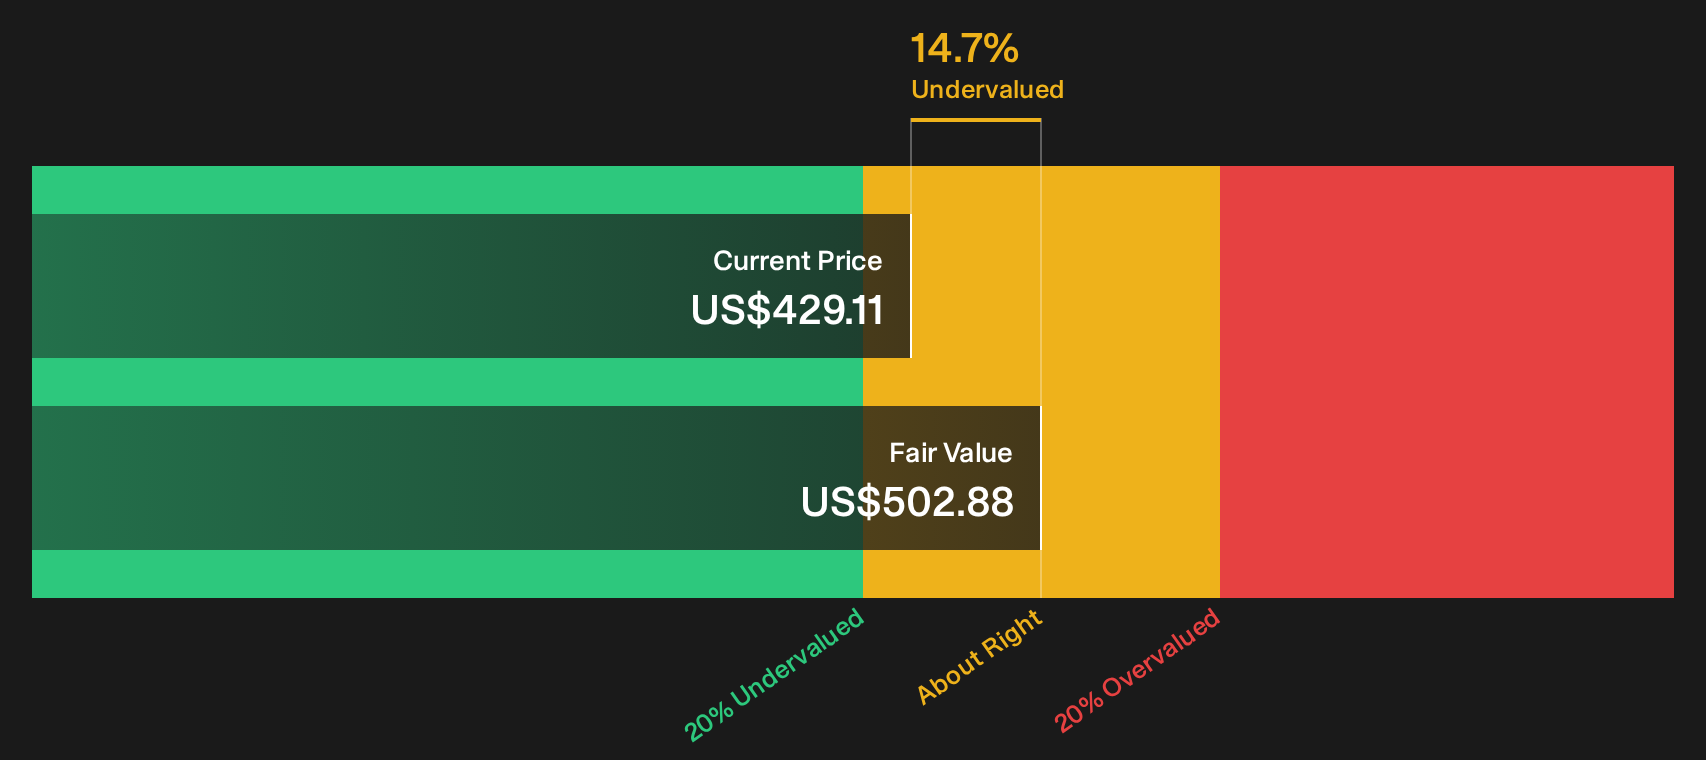
DCF work suggests Trane Technologies is trading around $429.11 against an estimated future cash flow value of $502.88, which points to undervaluation. That sits close to the $521.51 narrative fair value. If both models lean the same way, where might investors be misreading the risk?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the Trane Technologies story so far sounds optimistic, move quickly from headline takeaways to your own view by weighing the underlying data and assumptions. To see what optimism is grounded in, review the 4 key rewards
Looking for more Trane Technologies style investment ideas?
Do not stop at Trane Technologies. Use the Simply Wall St screener to uncover other opportunities that match your risk, income, and valuation preferences before they move away.
- Target resilient balance sheets and steady fundamentals with a diversified list of solid balance sheet and fundamentals (23 results) that keeps financial strength at the center of your watchlist.
- Zero in on mispriced opportunities by scanning the 33 high quality undervalued stocks that combine quality metrics with room for potential re-rating.
- Spot under-the-radar prospects by working through a curated 16 high quality undiscovered gems that many investors have not yet focused on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com