
Independence Realty Trust (IRT) Reaffirms Dividend, Is It A Bargain?
Independence Realty Trust (IRT) recently landed on investors’ radar after a joint M&A call with Centerspace and a fresh board decision affirming a quarterly dividend of $0.18 per share.
Despite the fresh corporate updates, Independence Realty Trust’s recent share price performance has been under pressure, with the stock down 11.01% on a 1 month share price return basis and 15.97% year to date. The 3 year total shareholder return of 13.15% points to a much stronger earlier phase of the story than the weaker momentum investors are seeing in 2026.
Scan how Independence Realty Trust compares with other income-focused real estate plays by reviewing the handpicked 6 dividend fortresses.For Independence Realty Trust, the recent slide could either be a blunt verdict on its apartment portfolio or a mood swing in sentiment. The valuation work starts by separating those two forces.
Most Popular Narrative: 23% Undervalued
Independence Realty Trust closed at $14.79, while the most widely followed narrative pegs fair value closer to $19.14. The gap between the trading price and that estimate is doing most of the talking.
Ongoing capital recycling selling older, higher CapEx assets to acquire newer, lower CapEx communities with higher growth profiles in high-demand regions allows IRT to enhance portfolio quality, capture operating synergies, and improve overall net margins and earnings growth potential.
Uncover how 0 investors see Independence Realty Trust as 23% undervalued.
Result: Fair Value of $19.14 (UNDERVALUED)
Still, the bullish Independence Realty Trust narrative weakens fast if Sun Belt oversupply keeps pressuring rents or if asset recycling fails to deliver the expected returns.
Find out about the key risks to this Independence Realty Trust narrative.
Another View: What Multiples Say About Independence Realty Trust
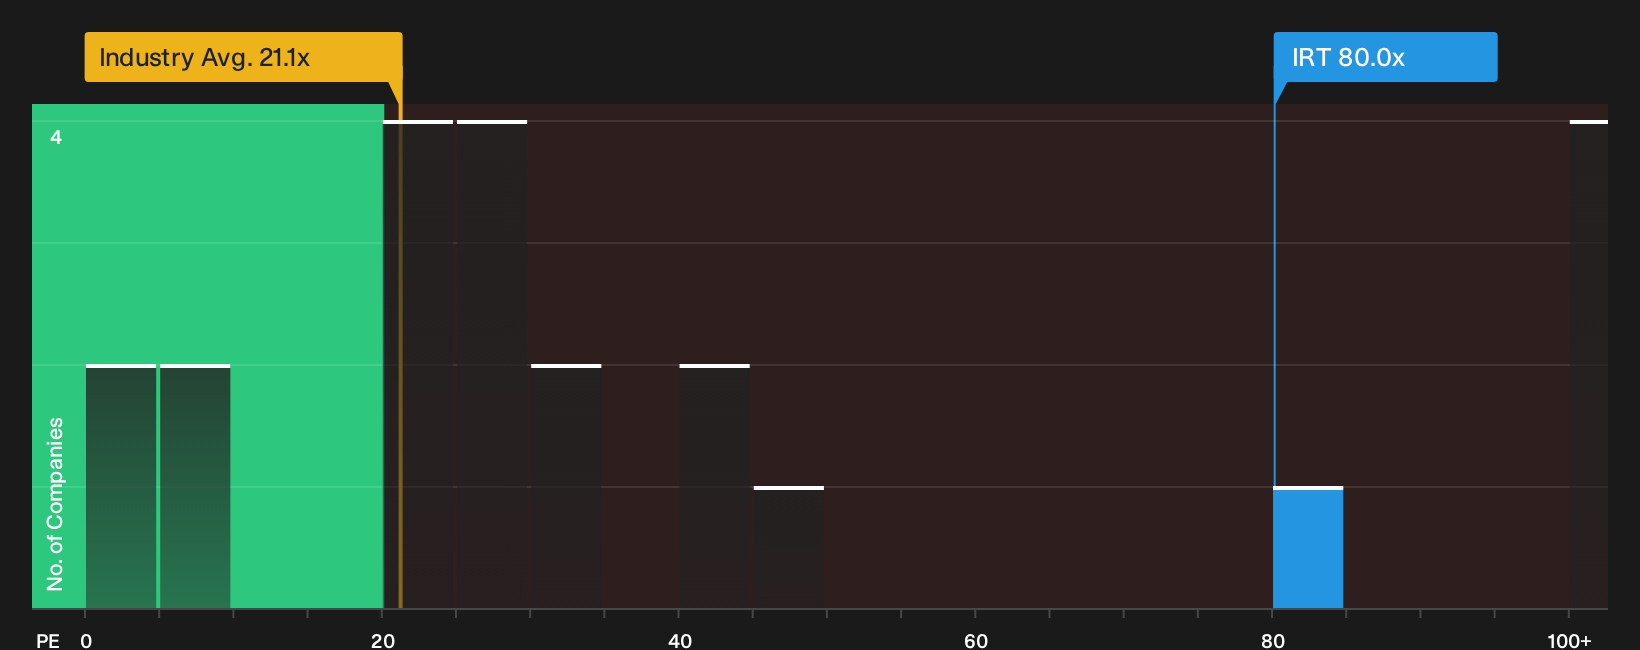
The discounted cash flow work points to upside for Independence Realty Trust, yet the market is asking investors to pay a rich P/E of about 80x. That compares with a fair ratio of 32.1x, the US Residential REITs group at 30x and peers at 32.7x, which suggests meaningful valuation risk if sentiment swings back toward sector norms.
Before leaning too hard on any one approach, it helps to see how these P/E gaps could close in practice, whether through price moves or changes in earnings, and what that might mean for your own risk tolerance See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Independence Realty Trust can easily pull you in opposite directions, so act promptly, review the underlying data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Independence Realty Trust?
If Independence Realty Trust has you rethinking your income and valuation mix, do not stop here. Fresh ideas often come from comparing different opportunities side by side.
- Target reliable income streams by scanning a curated set of higher yielding opportunities via the 6 dividend fortresses.
- Hunt for quality businesses priced below their assessed worth with the help of the 33 high quality undervalued stocks.
- Spot potential future leaders before the crowd pays attention by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com