
StoneX Group (SNEX), Why Is It Back In The Spotlight?
StoneX Group (SNEX) has moved into the spotlight after a strong fiscal third quarter and the rollout of a synthetic credit structure with DeltaTerra Investments tied to Agency mortgage bonds via credit default swaps.
Recent price action has been choppy, with a 1-day share price return of 1.32% after the latest quarterly update, but a 90-day share price move that is down 27.70% from earlier highs. Even so, StoneX Group still shows strong longer run momentum, with a year-to-date share price return of 54.81% and a 5-year total shareholder return of 418.95% that indicates meaningful long-term value creation.
Scan how StoneX Group compares to other financial stocks with strong momentum and recent catalysts by reviewing the hand picked 16 high quality undiscovered gems in this space.
After a sharp pullback, yet with analyst targets still sitting above the current US$67 share price, where does fair value for StoneX Group really land in that gap between recent trading levels and the range of estimates ahead?
Most Popular Narrative: 57% Undervalued
According to the most followed narrative, StoneX Group screens materially below its implied fair value of $155 per share compared with the last close at $67. This raises a simple question for investors about what has to go right for that gap to narrow.
The R.J. O’Brien acquisition, completed in July 2025, made StoneX the largest non-bank futures commission merchant in the United States and strengthened its listed derivatives, clearing, and commodity brokerage franchise. That matters because StoneX’s model benefits when clients need to hedge, trade, finance inventory, access liquidity, or manage risk.
See why 19 investors see StoneX Group as 57% undervalued.
Result: Fair Value of $155 (UNDERVALUED)
Still, the StoneX Group narrative can break if volatility cools and hedging volumes fade, or if the R.J. O’Brien integration adds cost and operational strain.
Find out about the key risks to this StoneX Group narrative.
Another View on StoneX Group Valuation
The first narrative leans on a fair value of $155 per StoneX Group share based on earnings power and book value. A second lens tells a different story. Our DCF model points to a future cash flow value of $22.08, which makes the current $67 price look expensive rather than cheap. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
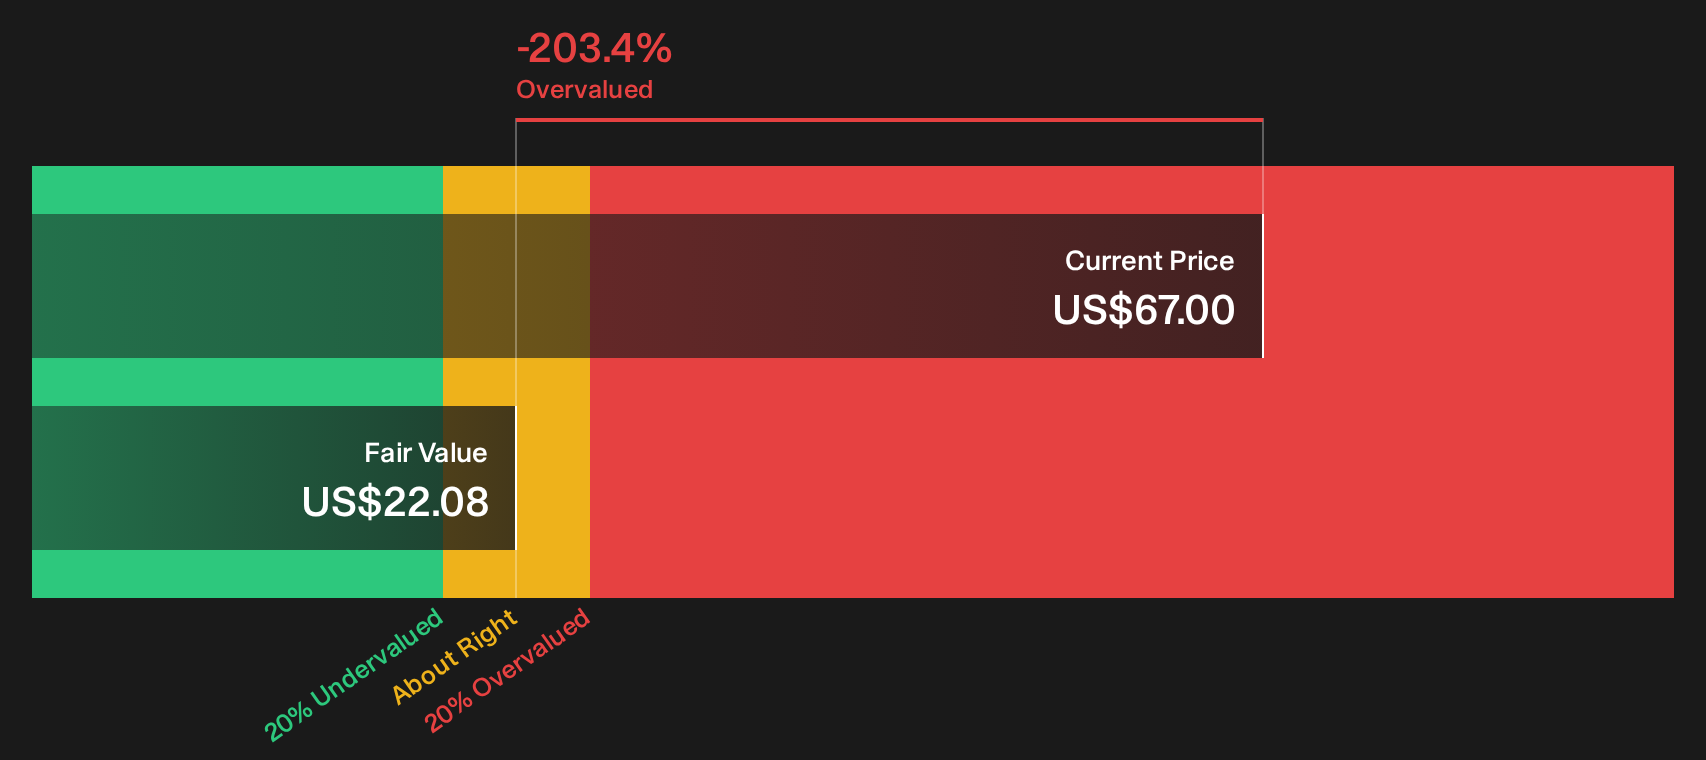
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out StoneX Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the StoneX Group story so far. Consider taking action while sentiment remains divided by weighing both sides of the data and reviewing the 3 key rewards and 1 important warning sign.
Looking for more StoneX Group style investment ideas?
Do not stop with StoneX Group. Use the Simply Wall Street Screener to surface fresh opportunities that fit your style before the market moves first.
- Target potential mispricing by scanning the 33 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying strength.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that could help you focus on sturdier businesses when conditions get tougher.
- Dial down volatility risk by filtering for a 30 resilient stocks with low risk scores so your watchlist is not dominated by the most unpredictable tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com