
American Water Works Company (AWK), Why Is It Back In The Spotlight?
American Water Works Company (AWK) has drawn fresh attention after Indiana American Water opened a new US$2.2 million training center in Gary, alongside broader workforce and infrastructure investments across Northwest Indiana.
For context, American Water Works Company shares have eased in the very short term, with the 1-day and 30-day share price returns down 1.69% and 2.03% respectively. However, the 90-day share price return of 8.66% and year-to-date gain of 4.28% point to rebuilding momentum. The 1-year total shareholder return of 3.37% and 3-year total shareholder return of 10.55% contrast with a 5-year total shareholder return that is down 14.38%, as investors reassess long-term value against ongoing operational and community-focused projects like the Gary training center and recent digital upgrades.
Scan beyond American Water Works Company and this latest Gary training hub by reviewing hand picked 30 resilient stocks with low risk scores that combine resilient operations with steadier return profiles.
American Water Works Company is investing substantial capital into long-term infrastructure and workforce development, yet the share price has only inched ahead over one year. Is that the sign of a resilient utility trading at a reasonable valuation today, or is it a premium narrative?
Most Popular Narrative: 2% Undervalued
On the most followed view, American Water Works Company screens as slightly undervalued, with a fair value of $138.73 against the latest $135.90 close. This perspective puts the Gary training build and broader capex program in a different light.
Heightened regulatory and societal focus on water quality and infrastructure modernization is accelerating rate case approvals and driving significant capital investment (e.g., $3.3 billion capital spend in 2025, requests for $111 million cumulative rate increases in CA by 2029). These factors enable predictable, above-inflation rate increases and support sustainable earnings expansion.
See why 32 investors see American Water Works Company as 2% undervalued.
Result: Fair Value of $138.73 (UNDERVALUED)
Still, if regulatory approvals in key states fall short of requests or planned debt funding becomes more expensive, the American Water Works Company fair value story could weaken.
Find out about the key risks to this American Water Works Company narrative.
Another View: American Water Works Company Looks Expensive On Earnings
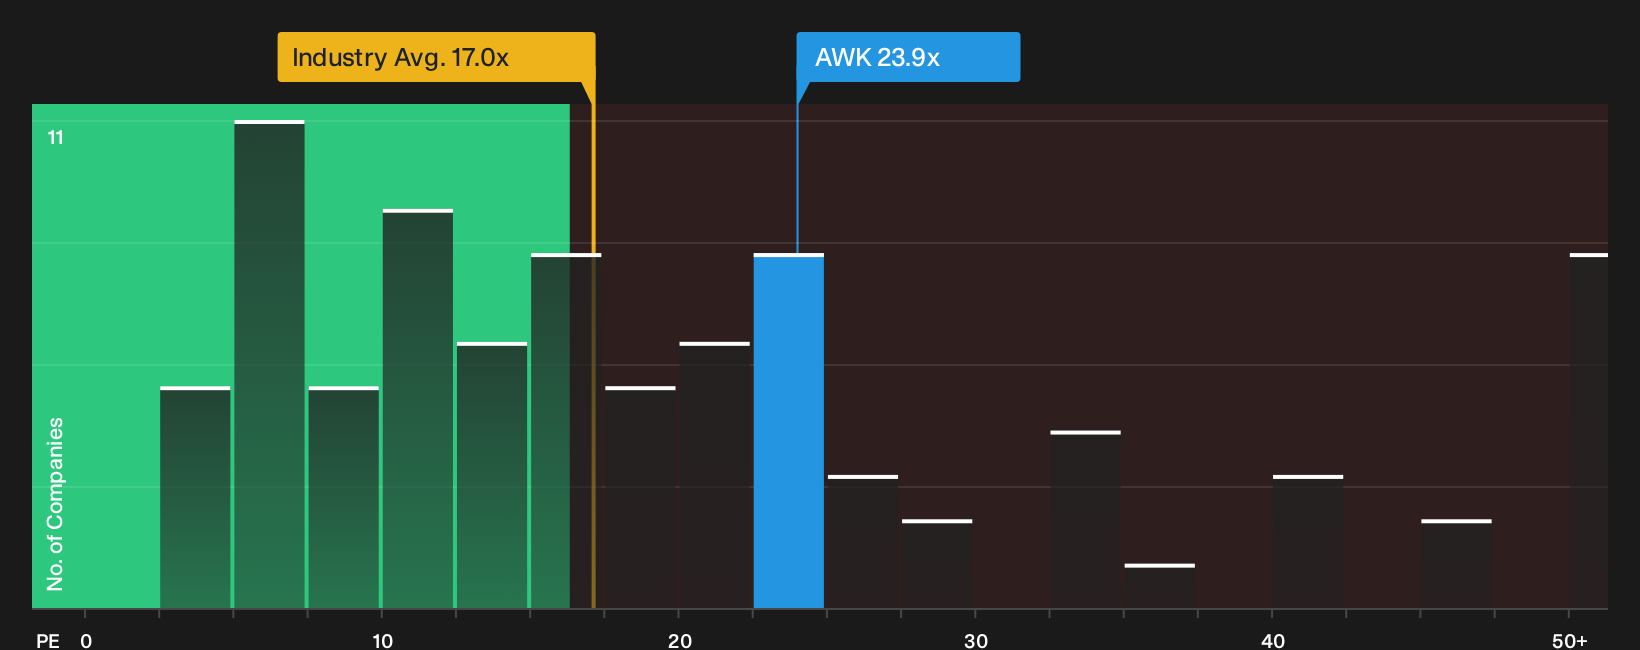
The narrative around American Water Works Company being 2% undervalued on fair value clashes with what its current P/E suggests. The stock trades on 23.9x earnings compared with a 17x average for the global water utilities group and a 22.1x fair ratio estimate.
That gap means investors are paying a richer price for each dollar of profit than the sector and even above where the fair ratio suggests the market could drift. This leaves less room for error if growth or regulation disappoints. The key question is whether that premium is the right price for perceived resilience or a margin of safety that has already been spent.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on American Water Works Company so far. Take a closer look at the full picture, weighing both the upside and the red flags through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond American Water Works Company?
Do not stop at American Water Works Company alone. Use fresh screeners to spot different types of opportunities that might fit your risk profile and income goals.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that can handle shocks without stressing the balance sheet.
- Hunt for potential mispricings through a focused search of 33 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Build a cash flow stream by reviewing a curated set of 6 dividend fortresses that concentrate on higher yielding, income focused businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com