
How Investors Are Reacting To Permian Basin Royalty Trust (PBT) Higher Cash Distribution
- Permian Basin Royalty Trust reported a past-month cash distribution of $0.019593 per unit, paid on October 15, 2026. Lower trust expenses more than offset weaker oil and natural gas volumes and softer oil pricing from Texas Royalty Properties, with some support from firmer natural gas prices.
- The payout excluded Waddell Ranch proceeds because August production costs exceeded gross revenue there, which highlights how rising field expenses can directly cap distributions even when other properties contribute cash flow.
- The focus now turns to how this higher distribution, driven mainly by reduced expenses, might influence the Permian Basin Royalty Trust investment narrative.
What Is Permian Basin Royalty Trust's Investment Narrative?
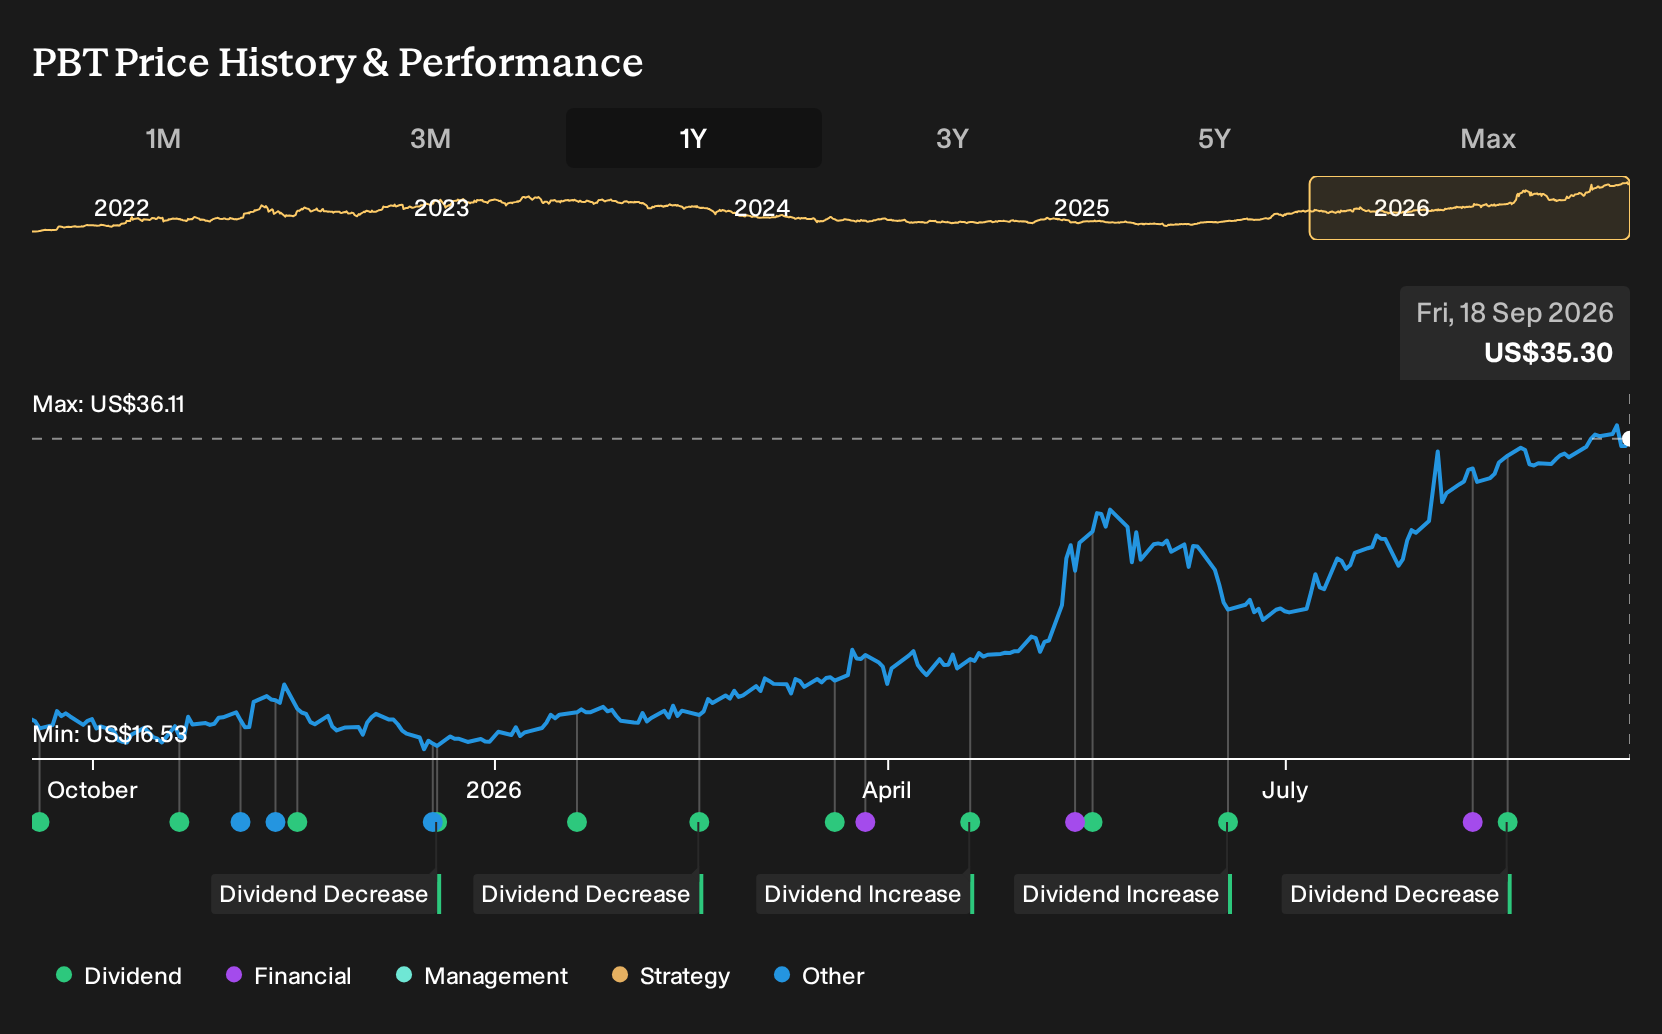
For Permian Basin Royalty Trust, the core belief is simple. You are buying exposure to oil and gas royalties, not an operating producer. That means no drilling decisions or capital spending at the trust level. The appeal lives in cash being passed through after operators recover their costs. The latest $0.019593 per unit payout, helped by lower expenses and without Waddell Ranch proceeds, underlines how sensitive near term cash flow is to field costs and production volumes.
In the short term, the key swing factors are commodity pricing, operating costs on the underlying properties, and how August excess costs at Waddell Ranch resolve. The proposed SoftVest combination into PBT Land and Minerals, Inc. adds an extra layer of execution and governance questions. Earnings have declined 2.6% per year over 5 years and the P/E of 101.5x looks full, so any sustained pressure on volumes or costs matters quickly for returns.
That said, sitting behind the recent distribution bump is a very different kind of risk that often gets far less attention than...
There's only one way to know the right time to buy, sell or hold Permian Basin Royalty Trust. Head to Simply Wall St's company report for the latest analysis of Permian Basin Royalty Trust's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Permian Basin Royalty Trust research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for Permian Basin Royalty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Permian Basin Royalty Trust's overall financial health at a glance.
Looking For More Permian Basin Royalty Trust Style Income Ideas?
If this latest distribution has you reassessing what you want from Permian Basin Royalty Trust, it can help to compare it with other income and quality focused opportunities using the Simply Wall St Screener.
- For investors who care most about durable income streams, start by scanning a curated group of 6 dividend fortresses that lean on consistent cash generation.
- If capital preservation and steadier profiles matter more to you than chasing every rally, review a selection of 30 resilient stocks with low risk scores that screen well on downside characteristics.
- When you want quality fundamentals without heavy crowding, widen your search to a focused pool of 16 high quality undiscovered gems that combine underlying strength with lighter attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com