
How Carrier Spending Cuts At SBA Communications Stock Have Changed Its Investment Story
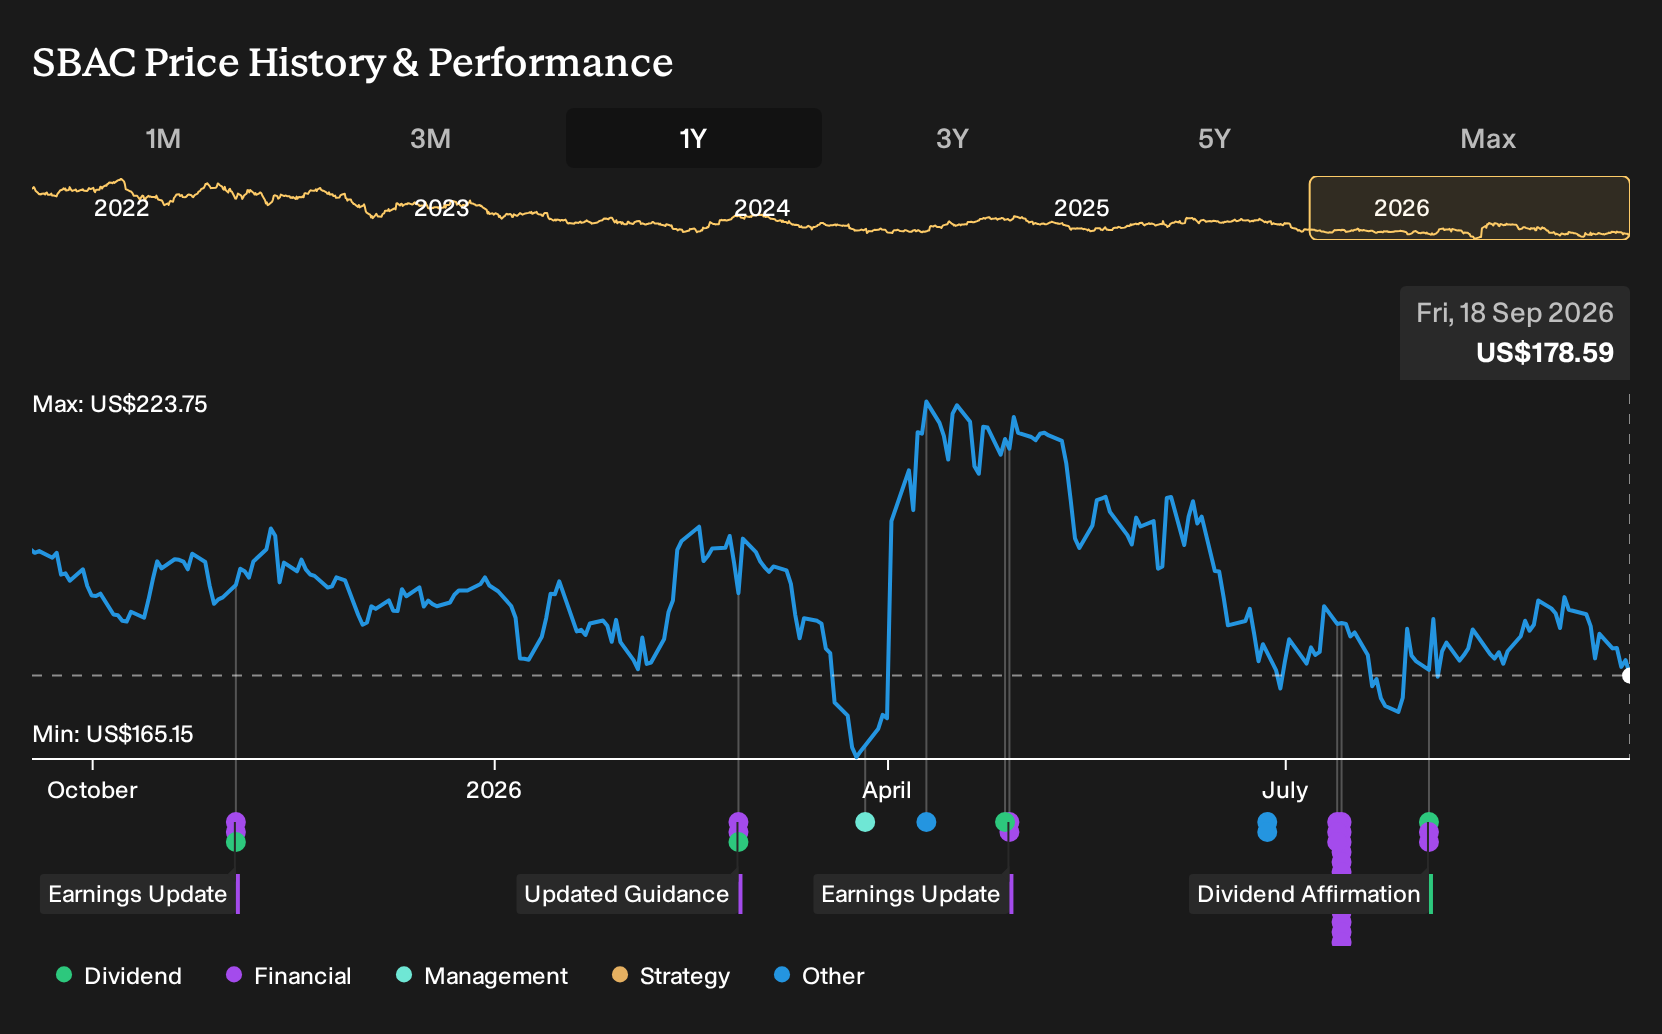
- SBA Communications has faced pressure in the past year as reduced capital spending by major U.S. wireless carriers and higher tenant churn from Sprint network consolidation weighed on performance, even as the business continued to lease space on nearly 40,000 towers under long term contracts.
- The combination of these industry headwinds, steady tower leasing activity, and ongoing international challenges has kept SBA Communications in focus for investors who are weighing resilient contracted revenue against carrier consolidation risks and foreign exposure.
- We will now look at how SBA Communications' investment narrative could be affected by carrier spending cuts and related tower leasing pressures.
Scan beyond SBA Communications and size up other tower and infrastructure landlords facing similar carrier spending pressures with a curated set of 89 AI infrastructure stocks.
SBA Communications Investment Narrative Recap
SBA Communications is still a bet on carriers needing dense, shared tower infrastructure for 5G and data growth, even while they pull back on near term capital spending. To stay comfortable as a shareholder, you need to believe that the long term demand for leasing space on those 46,000 towers outweighs current carrier churn and slower amendments.
The key short term catalyst is a stabilisation or pickup in U.S. carrier spending and churn, which would support leasing volumes and amendments. The biggest near term risk is further consolidation or network rationalisation by key tenants that could pressure pricing and tower utilisation. The recent underperformance mainly reinforces that risk rather than changing it.
The Q2 update is the most relevant recent data point for this story. SBA Communications reported funds from operations guidance for the year in a range of US$11.91 to US$12.36 per share. That guidance frames how much room the company has to keep investing in towers, manage debt and support dividends while carrier activity is subdued.
Beating Wall Street expectations in that quarter showed the existing tower portfolio and long term contracts are still converting into cash, even with carrier spending cuts and international churn. For you, the operational question is whether that earnings base can hold up as debt costs rise and as wireless customers keep optimising networks, since both directly affect how much financial flexibility SBA Communications retains for the next phase of infrastructure demand.
SBA Communications' current analyst narrative points to forecast revenues of US$3.1b and earnings of US$920.0m by 2029, based on revenue growth of 2.8% per year and a decline in earnings of US$80.0m from US$1.0b today.
Uncover how SBA Communications' fair value indicates a 29% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Community fair value estimates for SBA Communications from the Simply Wall St Community span roughly US$230 to US$263, based on two separate models. You are seeing private investors doing their own maths, not copying Wall Street. Set that beside carrier consolidation risk and tower-leasing reliance, and you get very different conclusions about future resilience.
Explore another SBA Communications fair value estimate, including one that suggests as much as 47% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SBA Communications research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SBA Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SBA Communications' overall financial health at a glance.
Looking for more investment ideas beyond SBA Communications?
Once you have formed a view on SBA Communications, it can help to compare that thesis with other opportunities that line up with your risk appetite, income needs, and time horizon using the Simply Wall St Screener.
- If capital preservation is a priority, start with a 30 resilient stocks with low risk scores that scores well on resilience and balance sheet strength.
- If you want income to play a bigger role in your portfolio, scan through a curated set of 6 dividend fortresses that combine yield with underlying fundamentals.
- If you prefer to hunt for less crowded opportunities, cast a wider net across a 16 high quality undiscovered gems that still show strong business quality but attract less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com