
BrightView Holdings (BV) Preferred Dividend Puts Fair Value Questions Back In Focus
BrightView Holdings (BV) just put preferred shareholders back in focus. The board approved a US$9.0 million cash dividend on its Series A preferred stock for the June to late September quarter.
Even with this preferred dividend in focus, BrightView Holdings’ common stock has been under pressure, with the share price down about 18% over the past 90 days and the year to date share price return down roughly 15% at around US$10.65. That short term weakness contrasts with a 3 year total shareholder return of about 38%. However, the 1 year total shareholder return is down roughly 20%, which suggests recent momentum has been fading as investors reassess both growth potential and risks.
Spot opportunities that echo or contrast BrightView Holdings’ recent swings by scanning a curated set of 33 high quality undervalued stocks that are poised for stronger sentiment shifts.With BrightView Holdings sliding despite the preferred payout, the real fork in the road is timing. Is this a reasonable entry point now, or does it make more sense to wait for a deeper pullback once valuation is unpacked?
Most Popular Narrative: 6.5% Overvalued
BrightView Holdings closed at $10.65, which sits above the $10.00 fair value pinned by the most followed valuation storyline that leans cautious on the current price.
The assumed bearish price target for BrightView Holdings is $10.0, which represents up to two standard deviations below the consensus price target of $16.05. This valuation is based on what can be assumed as the expectations of BrightView Holdings's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 0 investors see BrightView Holdings as 7% overvalued.
Result: Fair Value of $10.00 (OVERVALUED)
Still, if BrightView Holdings continues to improve customer and employee retention while achieving cost savings from fleet and technology upgrades, that bearish fair value view could be challenged.
Find out about the key risks to this BrightView Holdings narrative.
Another View on BrightView Holdings: Cash Flow Versus Narrative
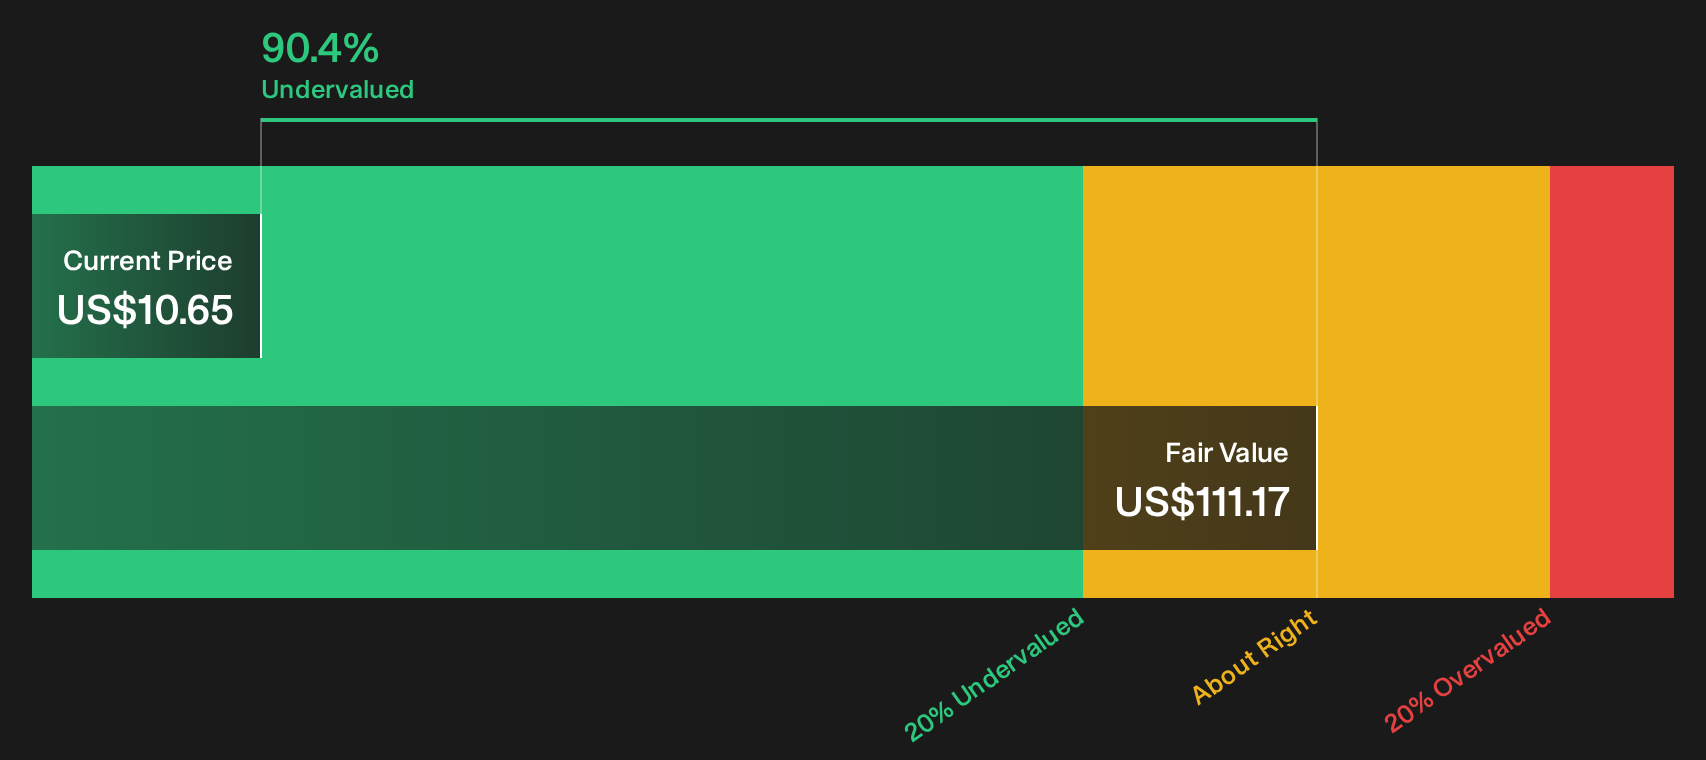
The bearish storyline pegs BrightView Holdings at a fair value of $10.00 and labels the current $10.65 share price as mildly rich. The SWS DCF model points in a very different direction, with an estimated future cash flow value of $111.17, which frames the stock as trading at a steep discount. Which lens feels more reasonable to you right now: the cautious narrative or the aggressive cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment looks split on BrightView Holdings, which means the window to weigh both caution and optimism is open right now if you want to shape your own view using 3 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond BrightView Holdings?
If BrightView Holdings has you thinking harder about risk, reward, and timing, do not stop at a single ticker when there are richer ideas on the table.
- Target potential mispricings by scanning a curated spread of 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to turn in your favor.
- Prioritize resilience in rough patches and sort for companies on our 30 resilient stocks with low risk scores so your capital leans toward sturdier balance sheets and steadier profiles.
- Hunt for tomorrow's quiet winners before the crowd catches on by running through the 16 high quality undiscovered gems, where smaller stories may still be flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com