
Ready Meals Partnership Could Matter For Pilgrim's Pride Stock (PPC)
- Pilgrim's Pride, through Pilgrim’s Europe Finance PLC, issued €500 million of 4.75% senior notes due 2034 and is partnering with Associated British Foods to produce Asian-inspired ready meals in the UK under the Patak’s and Blue Dragon brands.
- The tie-up with Associated British Foods positions Pilgrim's Pride to use its large Carrickmacross frozen meals facility to deepen its exposure to higher value prepared foods in Europe.
- We will now look at how Pilgrim's Pride's investment narrative could be influenced by this European ready meals partnership.
Scan other protein and prepared food businesses that may be positioned for similar shifts in mix by reviewing the curated list of solid balance sheet and fundamentals (23 results) alongside Pilgrim's Pride.
Pilgrim's Pride Investment Narrative Recap
For Pilgrim's Pride, the core belief is that a broad chicken and prepared foods platform can turn scale into steadier earnings, even as costs and commodity swings bite. The near term story rests on whether prepared foods, branded products and frozen meals can do more of the heavy lifting while fresh protein pricing stays choppy.
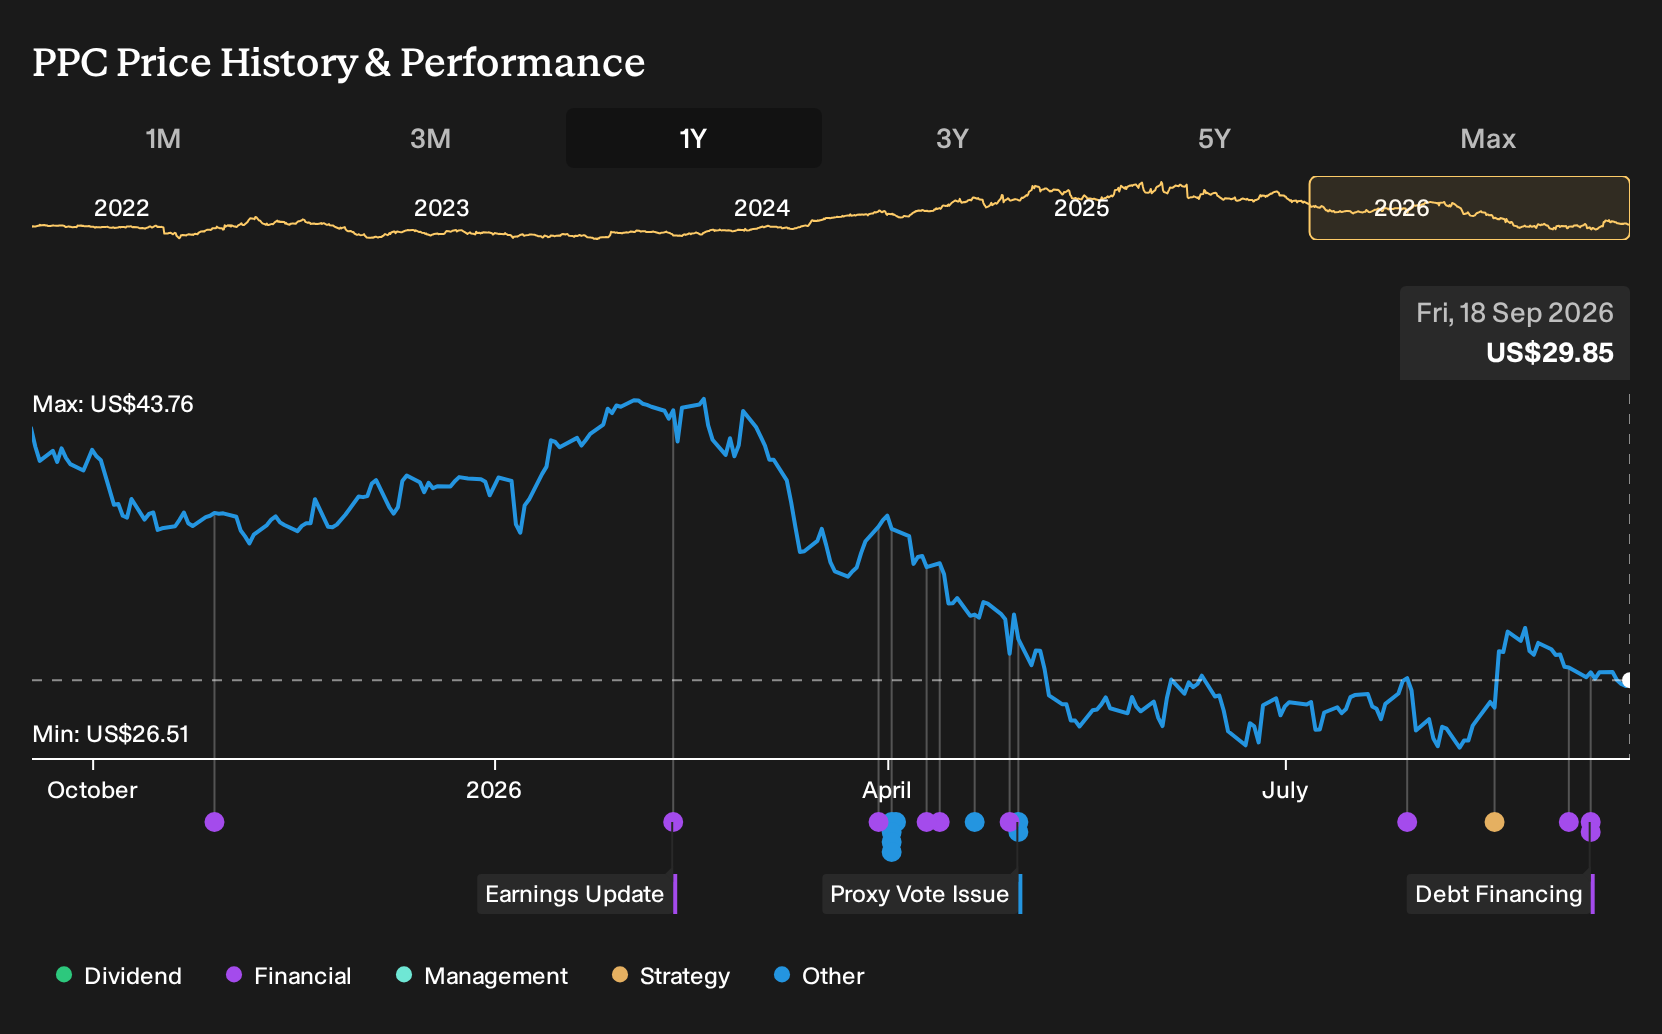
Recent debt issuance in Europe looks more like plumbing than a clear short term catalyst for shareholders. The bigger near term swing factor remains margin stability in chicken and pork, especially with current net profit margins at 3% versus 6.8% last year, while high leverage and higher customer concentration in borrowing keep financial risk on the radar.
The new €500 million 4.75% senior notes due 2034 matter because they connect directly to Pilgrim's Pride ramping up its European prepared foods push, including the Walkers Deli & Sausage acquisition and the ready meals partnership. Fresh debt increases fixed obligations, so execution on these capacity and product mix shifts needs to justify extra interest expense over time.
For you as an investor, the key question is whether this funding helps tip more of Pilgrim's Pride earnings toward value added products that are less exposed to grain price volatility and pure commodity chicken cycles. If prepared foods traction stalls, the group is left with higher debt, lower recent margins and the same exposure to input swings, which would keep the risk side of the equation front of mind.
Pilgrim's Pride's narrative projects $19.4b revenue and $937.4m earnings by 2029. This assumes 1.8% yearly revenue growth and an earnings increase of about $391.8m from $545.6m today.
Uncover why Pilgrim's Pride's fair value indicates a 12% potential upside to its current price before this discount gap starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Pilgrim's Pride accelerating its shift into prepared and case ready products. They were already pencilling in about €20.0b of revenue and $905.6m in earnings by 2029 before this European ready meals deal. This new partnership could push those expectations, or challenge them, once forecasts are refreshed.
Explore 2 other Pilgrim's Pride fair value estimates, including one that suggests up to 12% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pilgrim's Pride research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Pilgrim's Pride. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pilgrim's Pride's overall financial health at a glance.
Looking for more Pilgrim's Pride style ideas?
If the Pilgrim's Pride story has you thinking about balance sheets, income streams and risk, it can help to scan a wider set of businesses that share similar financial traits but play in different niches.
- If capital preservation is your priority, start with companies that score well on stability and risk, then review the 30 resilient stocks with low risk scores to see which profiles match your comfort level.
- For investors hunting for strong fundamentals at reasonable prices, widen the lens beyond Pilgrim's Pride by checking the curated 16 high quality undiscovered gems that combine quality metrics with less crowded ownership.
- If dividend income is central to your plan, focus on resilient payers that aim to balance yield with coverage and cash flow support and use the 6 dividend fortresses to spot candidates that fit that brief.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com