
Multi Price Gains Might Change The Case For Investing In Dollar Tree Stock (DLTR)
- Dollar Tree has shifted permanently to a multi price model, with products now offered at tiers like $3, $5, and up to $7, and recent results show 7.0% sales growth alongside a 3.3% larger average ticket.
- This move broadens Dollar Tree’s product range and mix, but it also forces budget focused shoppers to watch price labels more carefully to avoid surprises at checkout.
- We will explore how Dollar Tree's confirmed traction with its higher multi price tiers could reshape the longer term investment narrative.
Scan beyond Dollar Tree and see how other discount-focused retailers are positioned for multi price momentum through our hand picked 33 high quality undervalued stocks.
Dollar Tree Investment Narrative Recap
The big picture for Dollar Tree is simple. You need to believe the multi price model can keep pulling in value focused shoppers while still protecting the brand promise of low everyday prices. The recent confirmation that higher price tiers are sticking, with 7.0% sales growth and a 3.3% larger ticket, points to healthier near term store economics rather than a dramatic reset.
In the short term, the key catalyst is execution on this broader assortment without letting price confusion eat into traffic. The biggest risk sits in the same place. If tariffs, labor and shrink pressure margins at the same time as customers feel “sticker shock,” the multi price strategy could become more of a cost offset tool than a growth engine.
With no new company specific announcements tied directly to this multi price update, prior commentary on focus and footprint feels most relevant. Management has been concentrating resources on the Dollar Tree banner after exiting Family Dollar, which gives more room to refine assortments at $3, $5 and $7 while working on supply chain efficiency.
For you as an investor, that combination creates a clear execution test. Dollar Tree is leaning into value and convenience, using the wider price ladder to widen baskets and support margins, while also managing higher operational complexity and cost inflation. The story from here revolves less around new promises and more around whether current store level results can stay consistent as the rollout matures.
Dollar Tree's current narrative points to forecast 6.0% yearly revenue growth, with consensus expectations for earnings to rise from US$1.3b today to US$1.5b by 2029. This implies an earnings increase of about US$0.2b on projected revenues of US$23.5b in that same year.
Uncover why Dollar Tree's fair value indicates an 18% potential upside to its current price before that discount closes.
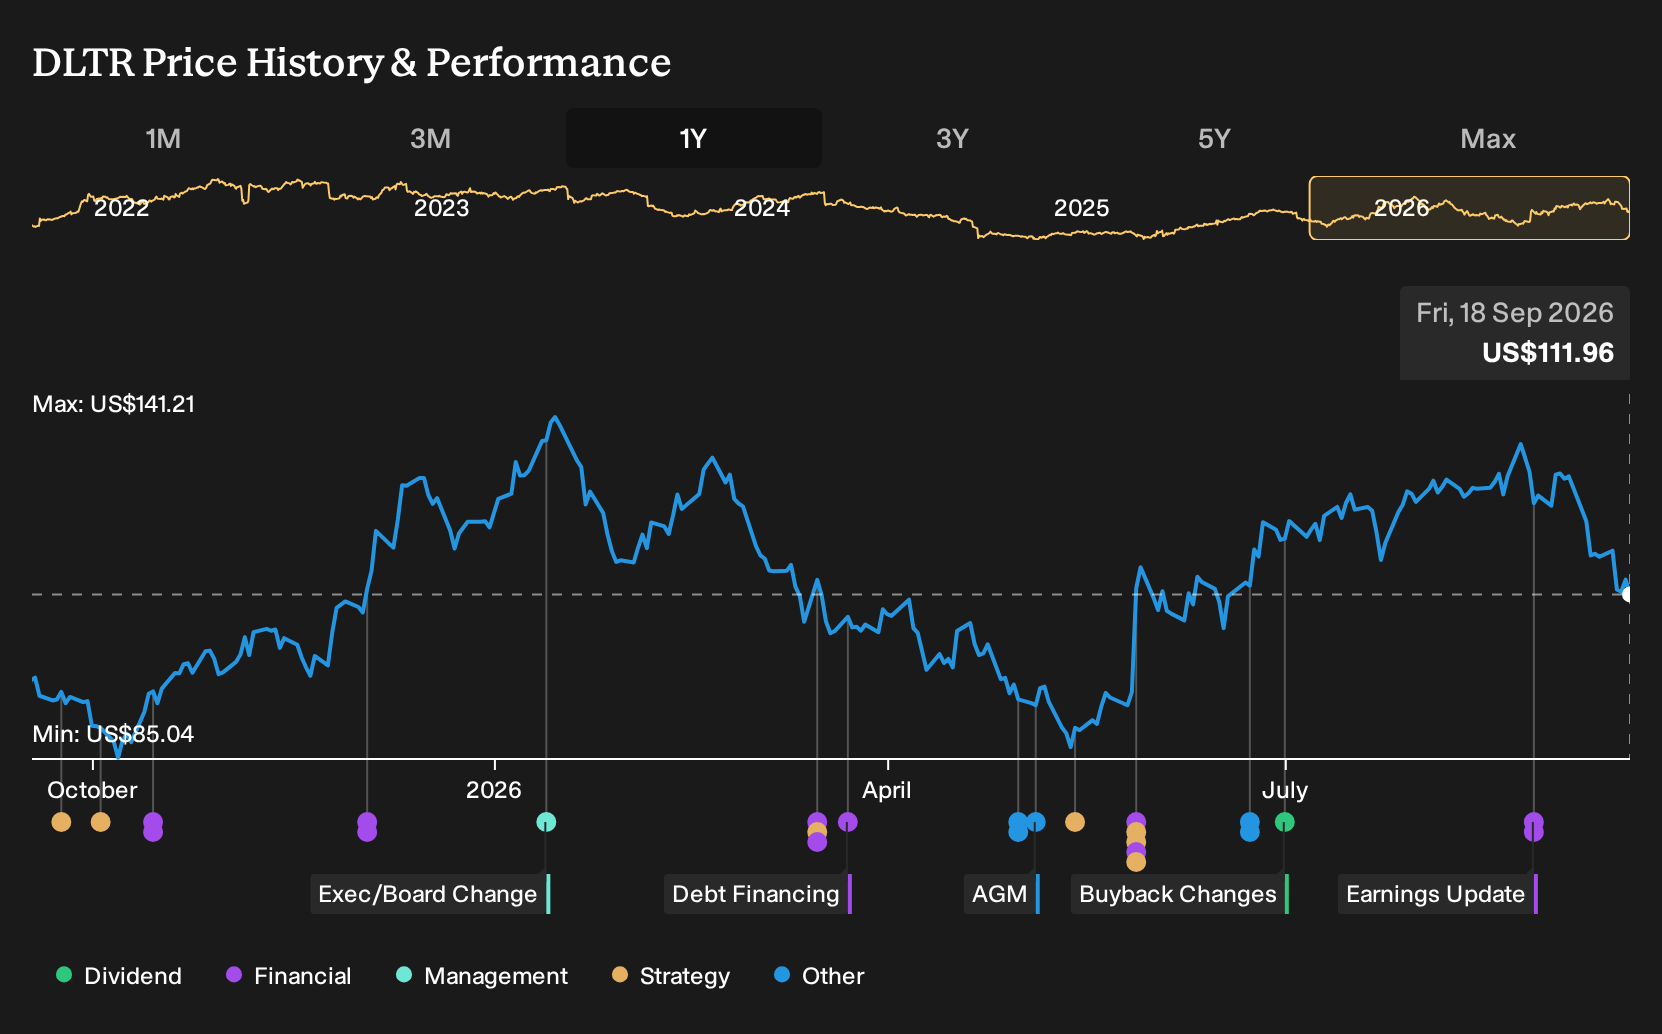
Exploring Other Perspectives
Some of the lowest Dollar Tree analysts focus less on multi price upside and more on tariff and wage pressure risk. Before this news, they were sketching out a margin squeeze story, with revenue growth assumptions closer to 5.2% a year and earnings drifting toward about US$1.1b by 2029. That is a much more cautious narrative than the consensus view. Use this new multi price update as a trigger to compare those competing stories and decide which assumptions you find more convincing.
Explore 5 other Dollar Tree fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Dollar Tree research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dollar Tree. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollar Tree's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dollar Tree?
Once you have a view on Dollar Tree, it can help to widen the lens and see how other businesses line up on quality, value, and resilience using the Simply Wall St Screener.
- If you want companies that combine financial strength with solid fundamentals, start with this curated list of solid balance sheet and fundamentals (23 results) that can help you focus on sturdy balance sheets first.
- For those who prefer a margin of safety on price, filter for potential bargains through a targeted 33 high quality undervalued stocks that zeroes in on quality and valuation together.
- If you are hunting for opportunities that the market may not be paying close attention to yet, scan a carefully built 16 high quality undiscovered gems and see which tickers deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com