
Is Blackbaud (BLKB) Trading At A Discount To Its Earnings?
Blackbaud shares have fallen back, with the stock closing at US$42.85 and posting a series of declines in recent periods. This puts fresh focus on whether that valuation is still supported by the company’s earnings power. After a run of negative returns, the key issue for investors is whether the current price properly reflects what the business is earning today.
- Over the past 5 years the share price has fallen 40.9%, which raises the question of whether the market is reassessing what Blackbaud’s earnings are worth.
- The business model leans heavily on software and services sold to mission driven organisations. The durability and growth of those revenue streams can shape how much investors are willing to pay for each dollar of earnings.
- Your read on Blackbaud is one view; the desks covering it have another. See what analysts think Blackbaud's shares could be worth.
The issue now is whether Blackbaud’s current share price is justified by the level and quality of its earnings.
If you want a wider lens on valuation, a focused stock screen built around 33 high quality undervalued stocks can be a useful next step in your research.
Is Blackbaud Still Cheap on Earnings?
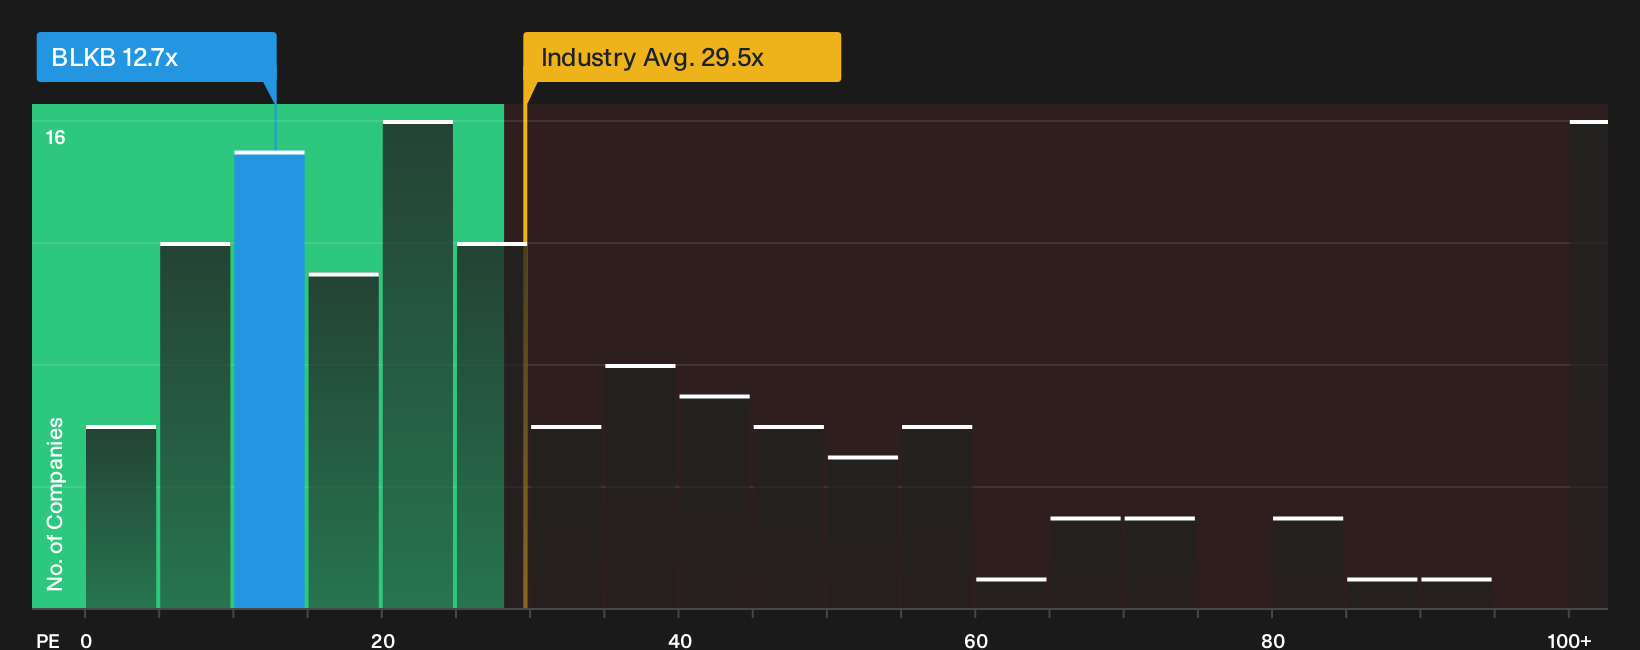
P/E works well for Blackbaud because earnings are a core focus for how the business is priced today. On this measure, Blackbaud trades on a P/E of 12.7x, which is far below the broader Software industry average of 29.5x and also well under the peer group on about 40.2x. For a company built around recurring software and services to nonprofits, that is a wide gap in how each dollar of profit is being valued.
The fair multiple implied by the stock’s own profile suggests a higher P/E than where Blackbaud currently trades, so the shares screen as undervalued on this specific yardstick. That points to the market applying a sizable discount to the earnings that the business is already generating, relative to what similar software companies typically command. Explore the numbers behind Blackbaud's P/E valuation.
The Blackbaud Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Blackbaud valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or materially less than today’s price, and they sit on the platform’s Community page. Instead of a single ratio or model output, these scenarios show the underlying future that figure relies on, so you can watch over time whether that story is actually playing out.
One of the top community narratives on Blackbaud: 16% undervalued
"The company's unique ability to connect its nonprofit fundraising solutions with corporate employee engagement platforms is creating a network effect..."
Discover why this Narrative puts Blackbaud at 16% undervalued.
One more thing about Blackbaud that could change the story
Before you stop your research on Blackbaud, it is worth asking whether the people in charge and the way they are rewarded push them to build long term value in the same way you would. See who runs Blackbaud and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com