
Elevance Health (ELV) Stock May Be Undervalued On Reaffirmed 2026 Guidance
Elevance Health has had a solid run over the past year, and the stock is now trading with recent news about its earnings outlook fresh in investors' minds. The core question is whether the current share price is warranted by the healthcare insurer's ability to keep converting its profit story into sustainable earnings per share.
- The stock has gained 33.6% over the past 12 months, which puts more weight on whether that move is supported by the underlying earnings power of the business.
- Management recently reaffirmed longer term earnings targets and cost discipline, which can support the case that Elevance Health's profitability profile is central to how investors assess its earnings based valuation today.
- There is a second opinion on Elevance Health worth weighing. See what analysts think Elevance Health's shares could be worth.
The issue now is whether Elevance Health's current market price is justified by the earnings the company is generating today and is expected to deliver in the years ahead.
If you want to apply this same earnings-focused valuation approach beyond Elevance Health, you can compare it against 33 high quality undervalued stocks.
Does Elevance Health Look Undervalued on Earnings?
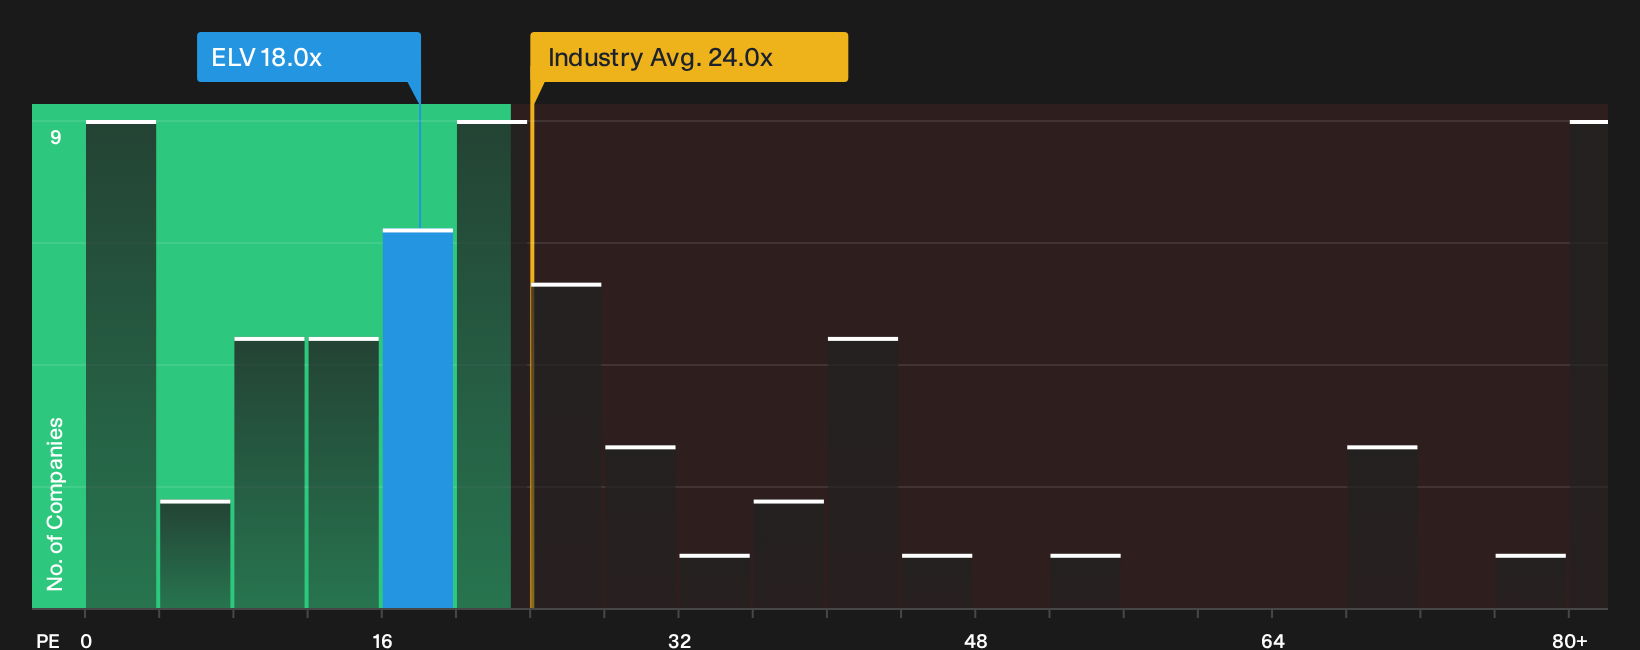
P/E fits Elevance Health because earnings per share sit at the center of how investors judge a mature insurer's profit engine. On this measure, the stock trades at a P/E of 18.0x, which is below both the broader healthcare industry average of 24.0x and the peer group on roughly 26.8x. That gap means the market is currently paying a lower price for each dollar of Elevance Health earnings than it pays for similar businesses in the sector.
The fair-value framework, which adjusts for factors like Elevance Health margins, growth profile, scale and risk, points to a higher P/E than where the shares currently change hands. Because management recently reaffirmed 2026 earnings and cost guidance, this lower multiple comes despite fresh confirmation of the profit targets that underpin analyst models. For investors, the setup is that the stock screens undervalued on earnings compared with what this tailored benchmark would suggest. Explore the numbers behind Elevance Health's P/E valuation.
The Elevance Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Elevance Health pick up where the valuation puzzle leaves off. They map out the earnings, margin and growth paths that would need to play out for Elevance Health's share price to look meaningfully higher or lower than today, and they sit on the stock's Community page so you can see the future story that sits behind each ratio or model and watch whether real world results keep matching it.
Community views on Elevance Health split between those who see more upside in the current setup and those who see the stock as closer to fully priced.
Bull case: 8% undervalued
"Strategic investments in digital consumer engagement and Carelon's diversified health services are accelerating revenue growth and providing higher-margin, recurring income streams..."
Discover why this Narrative puts Elevance Health at 8% undervalued.
Bear case: roughly fairly valued
"Elevated costs in government-backed plans and greater reliance on value-based care could compress margins despite operational improvements and diversification strategies..."
Explore why this Narrative puts Elevance Health at roughly fairly valued.
One more Elevance Health factor worth checking before you move on
Price tags and earnings only tell part of the story, because the people steering Elevance Health and the way their pay is structured can strongly shape future decisions and risk. See who runs Elevance Health and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com