
Should Raised 2026 Outlook Require Action From Quanta Services (PWR) Investors?
- Quanta Services recently raised its 2026 outlook, pointing to contributions from acquisitions like Phalcon, Enerfab, Percheron, and PSD, alongside a record US$53b backlog tied to power infrastructure projects.
- The updated guidance highlights how Quanta Services is leaning on acquired capabilities in electrical, mechanical, civil, and fabrication work to serve rising power and AI-related infrastructure demand.
- Next, the focus will be on how Quanta Services' raised 2026 outlook reshapes the investment narrative around its power-infrastructure backlog.
Scan beyond Quanta Services and compare its power and AI buildout story with hand-picked 38 power grid technology and infrastructure stocks shaping the next phase of grid and data center infrastructure.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to believe that its role in power infrastructure, grid modernization, and data center buildouts can keep translating into steady project flow and disciplined execution. The raised 2026 outlook and US$53b backlog speak to visibility, while the immediate catalyst remains how reliably that work converts into margin and cash generation.
The biggest near term risk still sits in execution and integration across many acquired platforms, layered on top of tight labor markets and complex, politically sensitive projects. The Ellen Rubin appointment does not materially change those near term drivers, but it slightly tilts board oversight further toward AI and cloud centric end markets.
The most relevant update here is Quanta Services adding Ellen Rubin to its board. Her background spans AI software, hybrid cloud storage, and a current role at Glasswing Ventures, which focuses on AI and frontier technologies. That experience lines up closely with Quanta’s push into power infrastructure serving data centers and AI related loads.
For you as an investor, this board addition mainly matters as Quanta tries to align its execution with AI heavy demand from cloud and technology customers. The catalyst to watch is whether the business uses that domain expertise to win and deliver complex grid and data center projects, while still managing acquisition risk, high debt levels, and cost pressure on skilled labor.
Quanta Services Forecasts And Valuation Check
Quanta Services' narrative projects US$46.7b revenue and US$2.4b earnings by 2029. This assumes 15.7% yearly revenue growth and roughly a US$1.3b earnings increase from the current US$1.1b level.
Uncover how Quanta Services' fair value indicates a 20% potential upside to its current price that could narrow quickly if sentiment shifts.
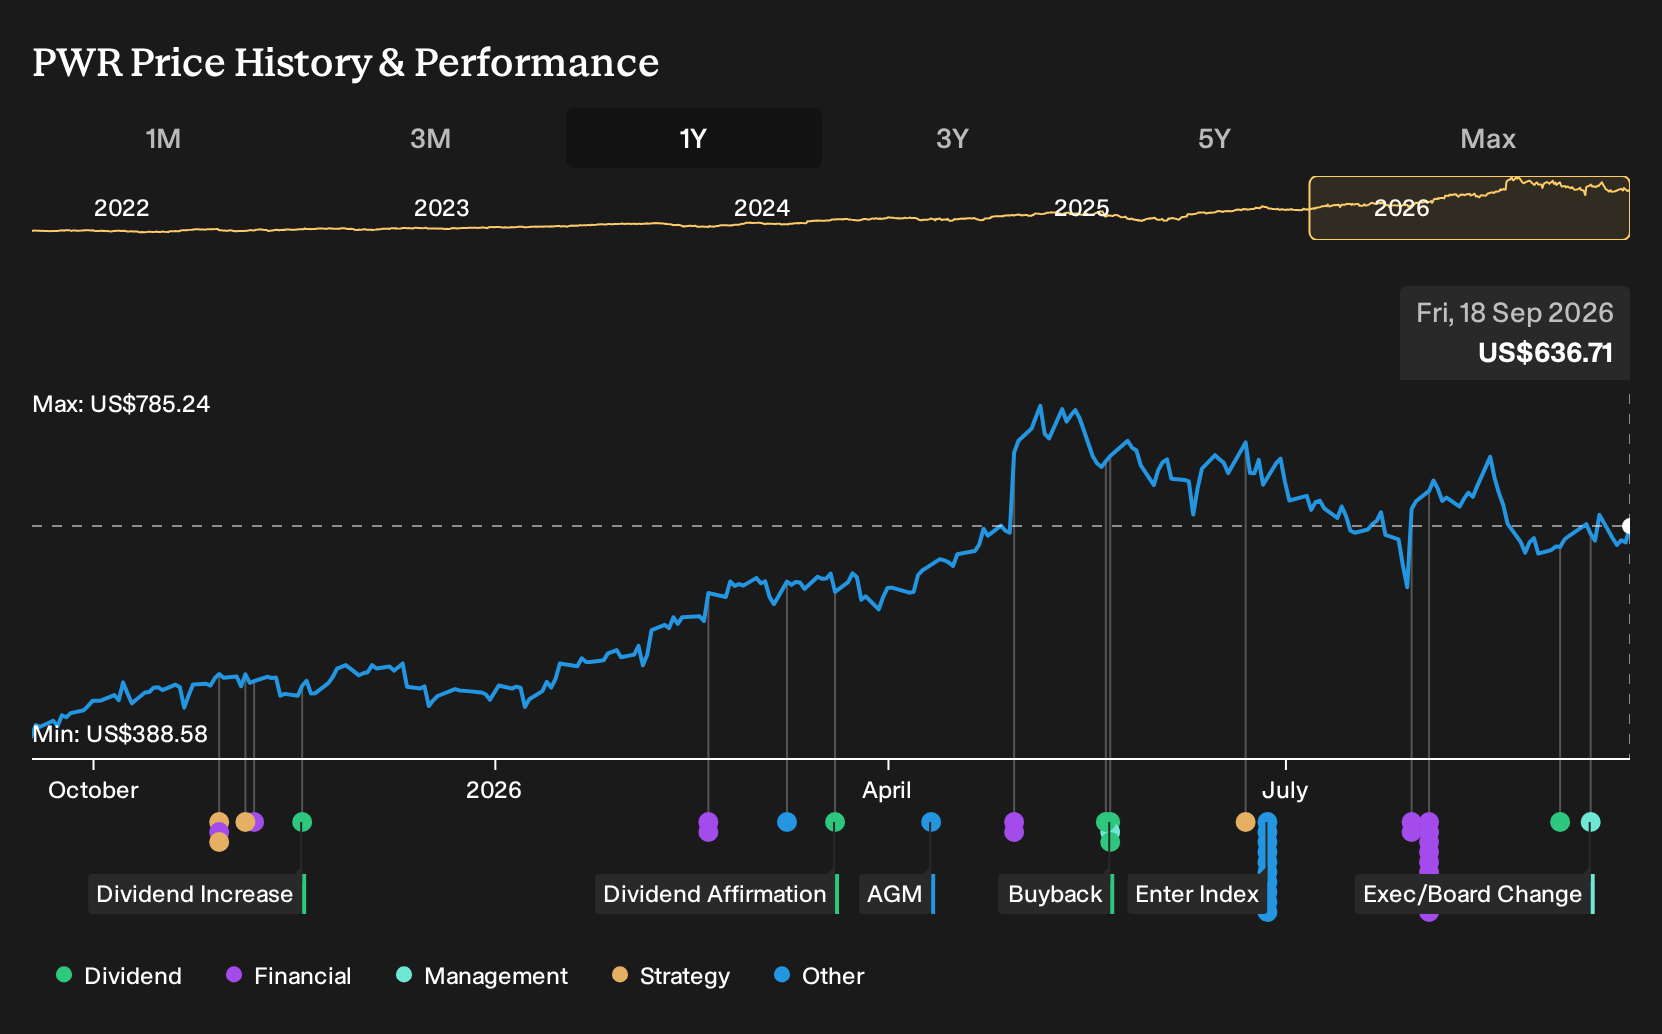
Exploring Other Perspectives
One alternate view puts project concentration risk at the center of the Quanta Services story. That bearish camp worries that a few delayed mega projects could unsettle earnings, even though it was still penciling in about US$50.5b of revenue and US$2.5b of earnings by 2029. Those pre news estimates show how far analyst opinions can stretch, so you may want to compare several narratives and decide which feels closest to your own expectations.
Explore 5 other Quanta Services fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Quanta Services Style Investment Ideas?
If the Quanta Services story has you thinking about where else large projects, strong balance sheets, or lower volatility might show up, the Simply Wall St Screener can help you scan the wider market using the same kind of filters that underpin this analysis.
- For investors hunting for potential value opportunities with solid fundamentals, start with a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- If dependable income is a priority, you can focus on payouts and stability through a collection of 6 dividend fortresses that might suit a more income focused approach.
- For those who care most about resilience and capital preservation, narrow your search to 30 resilient stocks with low risk scores and see which businesses fit a more defensive profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com