
Is Panasonic Holdings (TSE:6752) Fairly Valued Following Battery And Supercapacitor Demand Forecasts?
Panasonic Holdings (TSE:6752) is back in focus after fresh projections for the global battery pack and supercapacitor markets highlighted rising demand for electrification, energy storage and advanced power components.
Recent trading has been choppy for Panasonic Holdings, with the share price edging higher over the past week but easing over the past quarter, even as fresh battery and supercapacitor headlines keep the electrification story front and center. Across a longer window the picture looks very different, with a year to date share price return of 106.25% and a 1 year total shareholder return of 180.70% suggesting strong momentum. Meanwhile, the 3 year and 5 year total shareholder returns of 166.27% and 241.76% respectively point to a thesis that has been rewarded over time.
Scan beyond Panasonic Holdings and see which electrification suppliers are already pricing in the next wave of demand with our hand picked 38 power grid technology and infrastructure stocks.
The market has already rewarded Panasonic Holdings in a big way this year, yet the latest analyst and intrinsic value estimates still sit above the current ¥4,287 price. How wide is the real gap between enthusiasm and fair value?
Most Popular Narrative: 10.4% Undervalued
On the most followed view, Panasonic Holdings carries a fair value of ¥4,782.79 against a last close of ¥4,287. This puts the current enthusiasm slightly behind that narrative estimate of worth and brings the underlying growth drivers into sharper focus.
Demand for industrial energy storage systems is accelerating beyond initial expectations due to large-scale data center investment driven by generative AI adoption. This is likely to support revenue growth and improve recurring earnings quality in the Energy segment.
Despite a near-term EV slowdown in North America from policy headwinds (IRA tax credit termination, tariffs), Panasonic's locally produced, IRA-compliant battery cells and new high-capacity cell technology are sustaining customer demand. This is positioning the company for volume growth and higher net margins as electrification resumes its long-term trend.
See why 23 investors see Panasonic Holdings as 10% undervalued.
Result: Fair Value of ¥4,782.79 (UNDERVALUED)
Still, the story for Panasonic Holdings can change quickly if EV demand in North America stays weak or if trade policies and tariffs have a stronger impact than expected.
Find out about the key risks to this Panasonic Holdings narrative.
Another View: Panasonic Holdings Through The P/E Lens
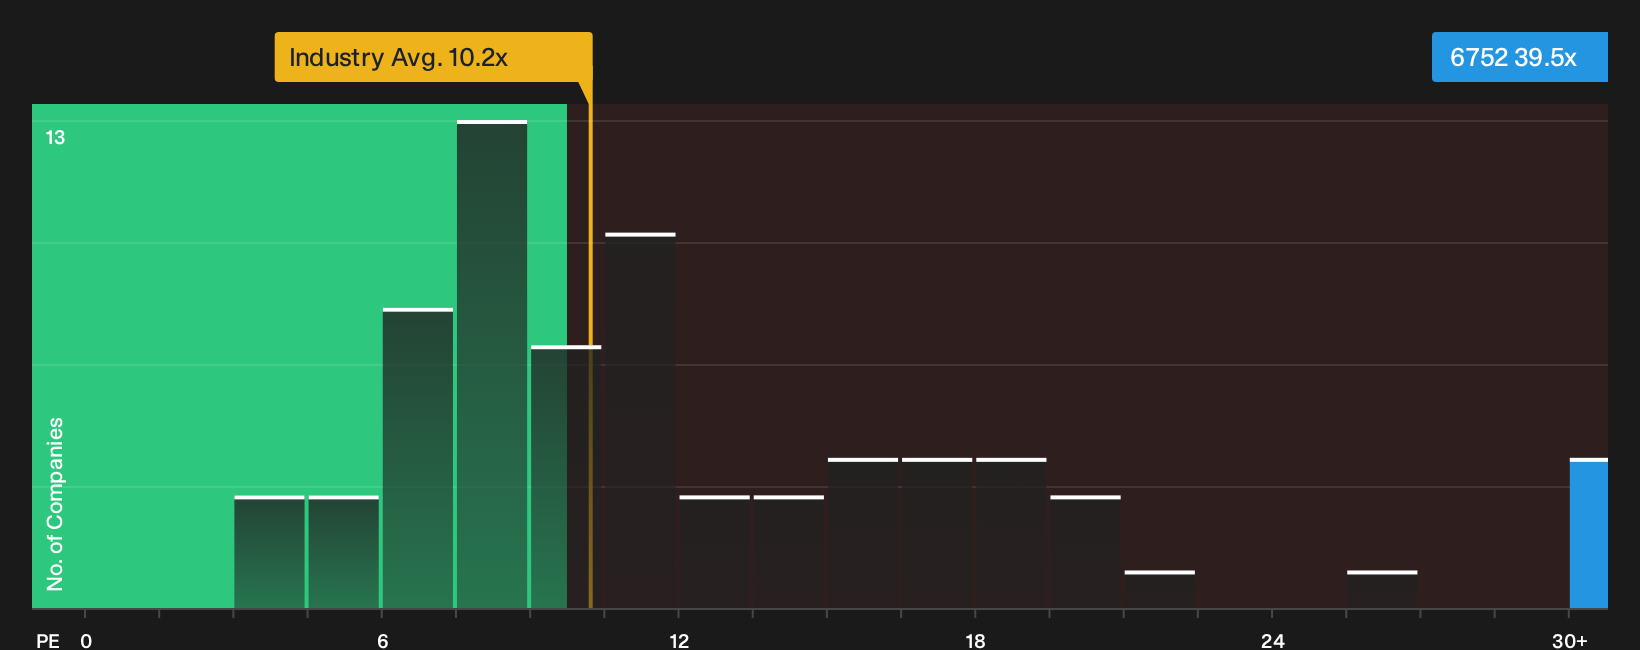
The SWS DCF model points to Panasonic Holdings trading below an intrinsic value estimate, yet the simple P/E picture is far less forgiving. At 39.5x earnings, the stock is almost 4x the JP Consumer Durables average of 10.2x and above a 34.6x fair ratio. This raises the question of how much optimism is already in the price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Panasonic Holdings can be a useful prompt rather than a verdict. Use the full data set, move quickly, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Panasonic Holdings?
If Panasonic Holdings has your attention, do not stop there. Fresh ideas often come from scanning outside your comfort zone, and the Screener makes that fast.
- Hunt for quality at a discount by zeroing in on companies that look attractively priced with the help of 17 high quality undervalued stocks.
- Build steadier income potential by focusing on businesses that combine higher yields with resilience using the 14 dividend fortresses.
- Prioritise resilience over drama and concentrate on financially robust candidates through the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com