
Data Centre Demand Might Change The Case For Investing In Hubbell Stock (HUBB)
- Hubbell's CEO Gerben W. Bakker recently presented at Morgan Stanley's 14th Annual Laguna Conference, highlighting strong, supply constrained demand for the group’s data centre solutions and outlining pricing and productivity measures intended to offset raw material and tariff cost inflation.
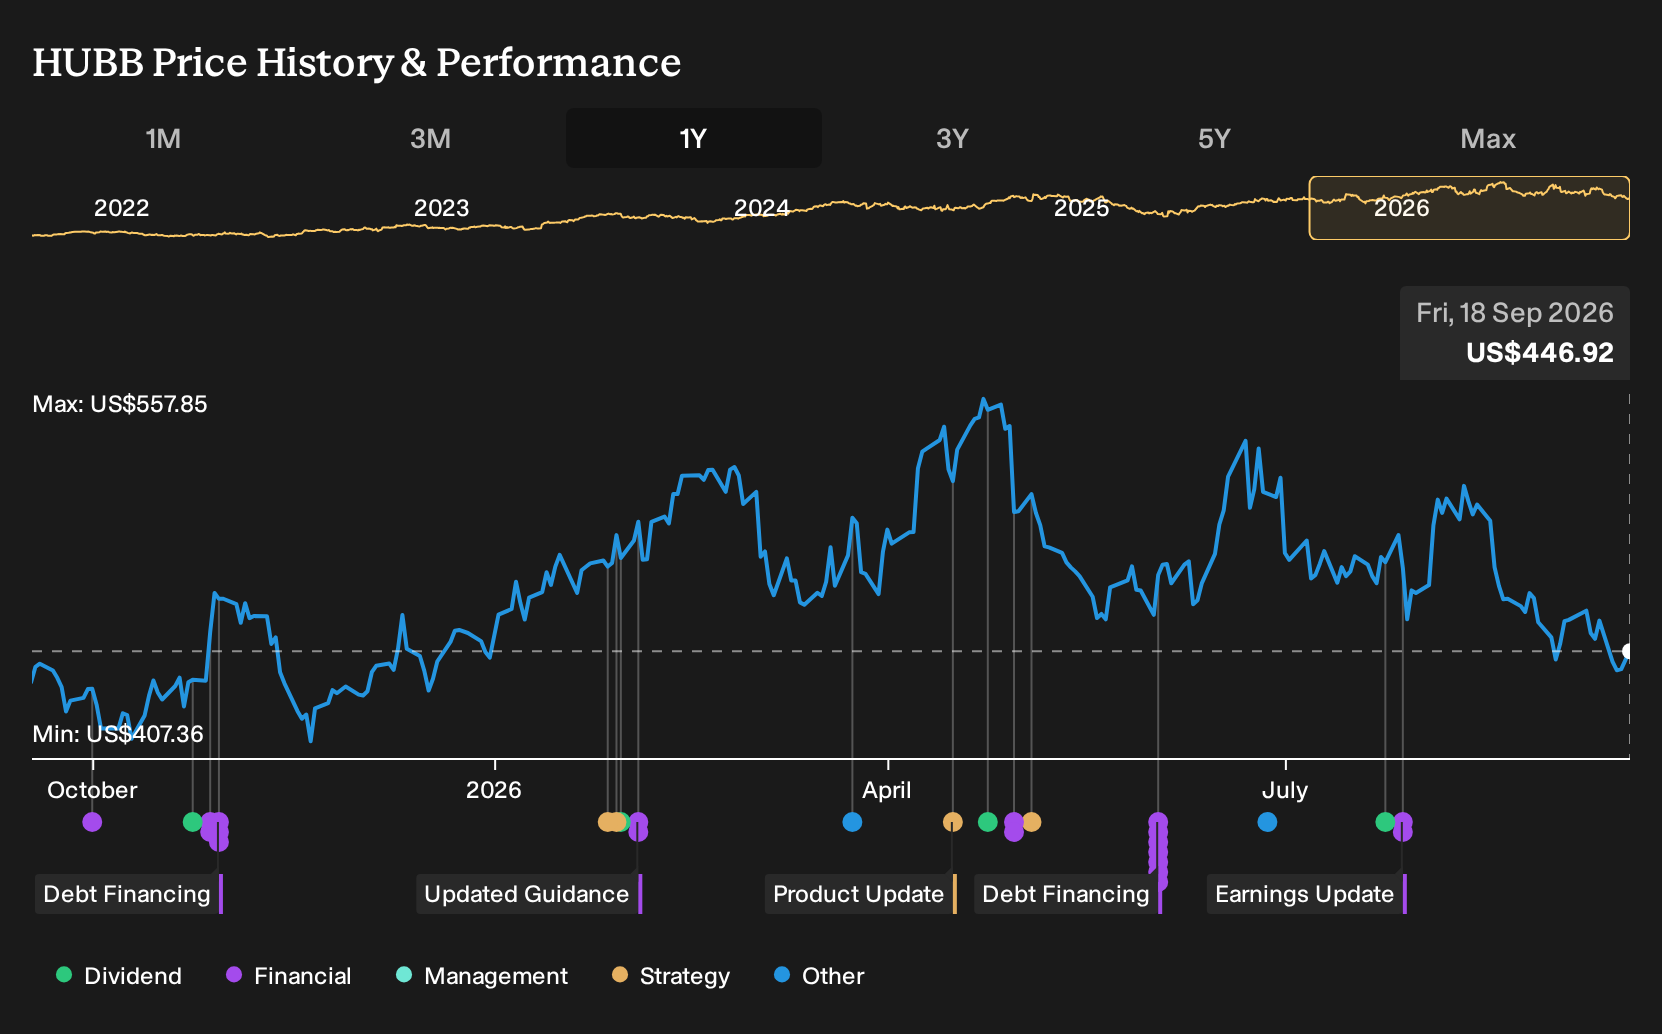
- The June 2026 US$1.9b senior notes linked to the NSI Electrical Buyer Inc. acquisition show Hubbell leaning on its balance sheet to expand its electrical portfolio in areas that connect directly to data centre and grid spending.
- We will look at how Hubbell's investment narrative is shaped by management's emphasis on backlog driven, supply constrained data centre demand.
Hubbell Investment Narrative Recap
To own Hubbell, you need to trust that demand for data centre and grid infrastructure turns into durable orders, healthy pricing and solid cash conversion. The Laguna commentary leans into that belief. Management is talking about backlog-driven, supply-constrained data centre demand, plus pricing and productivity actions that are intended to neutralise raw material and tariff cost pressure by 2025.
The near-term swing factor is execution on those price and productivity levers while keeping volumes flowing in grid and data centre projects. Margin risk sits on the other side. Cost inflation, tariffs and any slowdown in grid automation or data centre orders could squeeze profitability and make the current capital intensity harder to justify.
The NSI Electrical Buyer Inc. acquisition, funded in part with US$1.9b of senior notes maturing in June 2026, ties directly into what you heard at Laguna. Hubbell is leaning into areas connected to data centre and grid spending, effectively widening the toolkit it can sell into those projects as capacity comes online and backlogs convert.
That extra scale also raises the bar on execution. The debt layer needs to be supported by operating cash flow, and the acquired assets need to slot cleanly into Hubbell’s pricing, productivity and integration discipline. For you as a shareholder, the catalyst is simple: evidence that the enlarged portfolio supports margins while cost and tariff pressures remain manageable.
Hubbell's narrative projects US$8.6b revenue and US$1.3b earnings by 2029. That implies 11.4% yearly revenue growth and an earnings increase of about US$399m from current earnings of US$900.6m.
Uncover why Hubbell's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into backlog and acquisition upside. The most optimistic Hubbell analysts were pencilling in about 12.8% yearly revenue growth to roughly US$8.9b by 2029 and earnings per share near US$24.79, before this Laguna Conference update. You can treat that as a stretch case and compare it with your own expectations.
Explore 3 other Hubbell fair value estimates, including one that suggests as much as 41% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hubbell research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hubbell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hubbell's overall financial health at a glance.
Looking for more Hubbell investment ideas?
If the Hubbell story has you thinking about how to broaden your watchlist, the Simply Wall St Screener can help you quickly sort through other companies with traits that fit your approach. You can start with a few targeted angles that line up with how you think about risk, balance sheets and income.
- If you want a focus on value with quality fundamentals, review the 33 high quality undervalued stocks that currently pass these filters.
- If capital preservation sits high on your list, filter for companies with steadier profiles using the 30 resilient stocks with low risk scores to see which ones meet that bar.
- If financial resilience matters most to you, start with the list of solid balance sheet and fundamentals (23 results) and see which businesses pair cleaner balance sheets with sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com