
China Jinmao Holdings Group (SEHK:817) Reports Fresh Sales And Raises The Question Of Value
China Jinmao Holdings Group (SEHK:817) has released preliminary unaudited sales data that gives investors fresh insight into current trading. The update covers contracted sales for August 2026 and the eight month period to 31 August.
Despite the August sales update, China Jinmao Holdings Group’s HK$1.23 share price sits after a 1 month share price return that is down 19.34% and a 1 year total shareholder return that is down 19.65%. However, the 3 year total shareholder return is up 24.70%, suggesting longer term holders have seen a very different experience to recent momentum.
Spot fresh ideas by comparing China Jinmao Holdings Group's recent move with our hand picked list of 180 high quality undervalued stocks.China Jinmao Holdings Group has sizeable contracted sales and a long list of projects, yet the share price has dropped sharply in recent weeks. Do those two stories line up on valuation today?
Price-to-Earnings of 37.3x: Is it justified?
On valuation, the key data point for China Jinmao Holdings Group right now is its P/E multiple of 37.3x, which looks steep against both peers and its own fundamentals at a last close of HK$1.23.
The P/E ratio compares the share price with earnings per share, so a higher figure usually implies investors are paying more today for each unit of profit. For a property developer and related services group like China Jinmao Holdings Group, that often reflects expectations for future earnings recovery or relatively resilient profitability compared with sector trends.
The broader context is more mixed. Earnings over the past 5 years have declined 36.8% per year and return on equity currently sits at a low 1.8%, so the rich 37.3x P/E points to the market assigning a high price to relatively thin profitability. The estimated fair P/E of 18.2x is far lower than the current level. This signals a valuation that could move closer to that fair ratio if expectations cool or if earnings do not track the current optimism.
China Jinmao Holdings Group also trades on a much higher P/E than the Hong Kong Real Estate industry average of 8.9x and the peer average of 20.6x. That sharp gap means investors are paying a premium multiple versus both the sector and similar stocks, despite the low return on equity and past earnings decline.
Explore the SWS fair ratio for China Jinmao Holdings Group.
Result: Price-to-Earnings of 37.3x (OVERVALUED)
Still, China Jinmao Holdings Group carries clear risks, including a low 1.8% return on equity and annual earnings contracting 36.8%. This combination could challenge such a rich valuation.
Find out about the key risks to this China Jinmao Holdings Group narrative.
Another View on China Jinmao Holdings Group’s Value
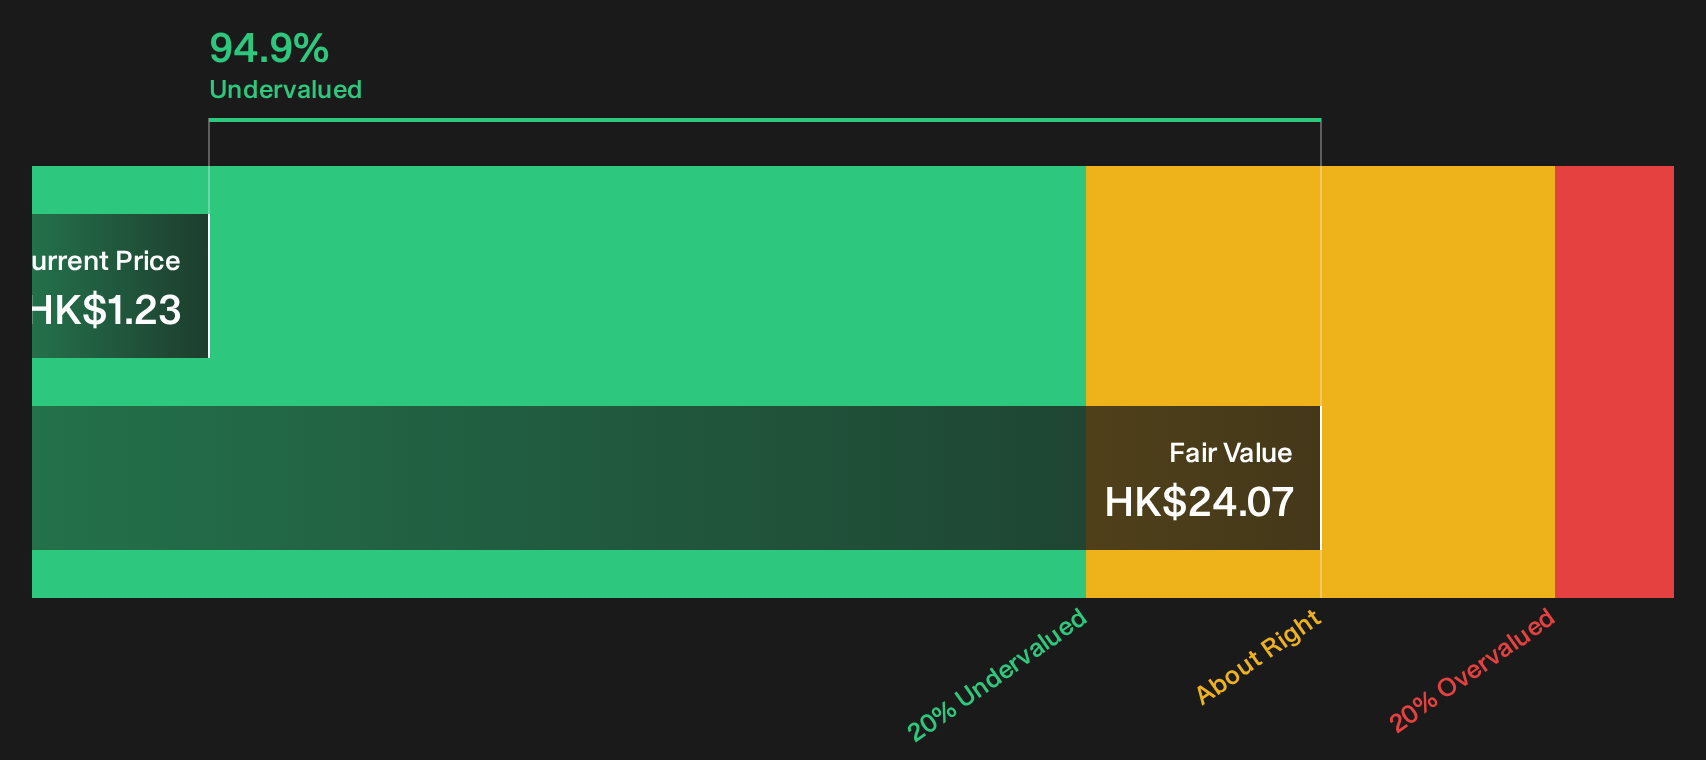
The P/E looks rich, yet the SWS DCF model points the other way. At a share price of HK$1.23, China Jinmao Holdings Group is assessed as trading 94.9% below an estimated future cash flow value of HK$24.07, which presents the stock as heavily undervalued according to this method. Which story do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Jinmao Holdings Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 180 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With such mixed signals around China Jinmao Holdings Group, it makes sense to move quickly and stress test the data against your own expectations. Before drawing any conclusion, weigh both sides of the story by reviewing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Jinmao Holdings Group?
If China Jinmao Holdings Group has you rethinking your next move, broaden your watchlist and pressure test your thesis against fresh ideas from the Simply Wall St screener.
- Target potential mispricing by scanning our 180 high quality undervalued stocks and compare these candidates with how China Jinmao Holdings Group is priced today.
- Prioritise resilience and peace of mind by reviewing a 227 resilient stocks with low risk scores that focuses on companies with more measured risk profiles.
- Hunt for under-the-radar potential by checking a 613 high quality undiscovered gems that filters for strong fundamentals before the crowd turns its attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com