
Sandoz Group (SWX:SDZ) Expands Biosimilars And GLP1 Reach, Is The Upside Already Priced In?
Sandoz Group (SWX:SDZ) just packed two key updates into a single week, pairing a global emicizumab biosimilar collaboration with mAbxience and fresh Health Canada approval for Sandoz Semaglutide in type 2 diabetes.
The stock has been volatile in recent weeks, with a 7.4% decline over the past 30 days even as the year-to-date share price return is 19.9% and the 1-year total shareholder return is 45.7%. This suggests momentum has been building as Sandoz Group rolls out new biosimilar deals, GLP-1 approvals and fresh bond financing.
Scan for other pharma and biosimilar plays that show similar deal flow and regulatory catalysts by reviewing the list of solid balance sheet and fundamentals (198 results) alongside Sandoz Group.
Sandoz Group now trades well above its spin price yet has just given back 7.4% in a month. Do the current numbers still compensate you for that volatility, or has the easy upside already been used up?
Most Popular Narrative: 8% Undervalued
Sandoz Group closed at CHF68.62 compared with a narrative fair value of CHF74.95, which frames the recent pullback against expectations for stronger earnings power over time.
Regulatory streamlining and investments in advanced in-house manufacturing (notably Slovenia expansion and Just-Evotec acquisition) are expected to lower production costs and speed up time-to-market for new biosimilars, driving margin expansion and higher net earnings. Strong commercial execution and leading market share in biosimilars (now 30%+ of net sales and growing) improves Sandoz's revenue mix towards higher-margin products, supporting overall profitability and long-term earnings leverage.
See why 39 investors see Sandoz Group as 8% undervalued.
Result: Fair Value of CHF74.95 (UNDERVALUED)
Still, the bullish Sandoz Group story clashes with persistent pricing pressure in generics and with ongoing execution risk around large manufacturing expansions and partner-heavy biosimilar projects.
Find out about the key risks to this Sandoz Group narrative.
Another View: Sandoz Group Looks Expensive On Earnings
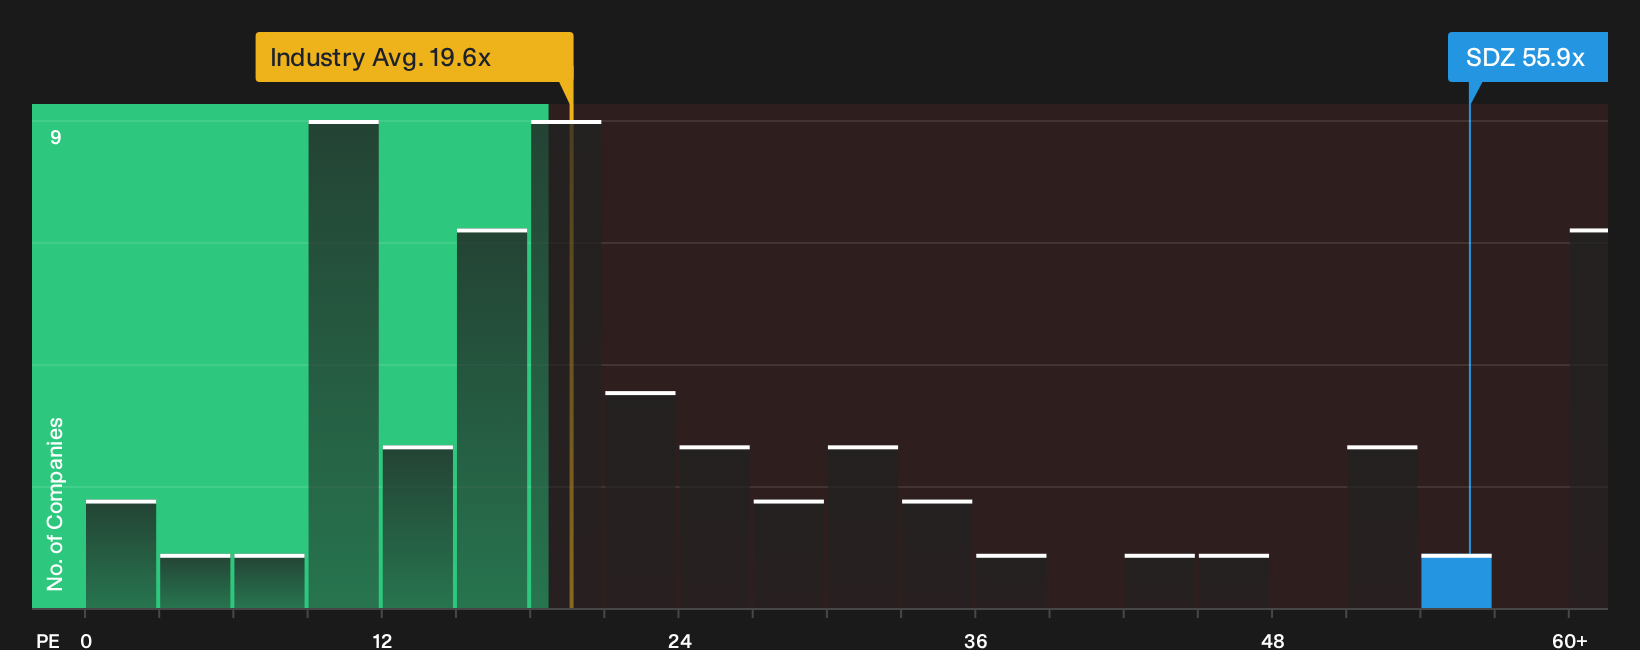
On the headline narrative, Sandoz Group appears 8% below fair value at CHF74.95. Using earnings-based yardsticks, the picture changes. The stock trades on a P/E of 55.9x, versus 32.6x for peers and 19.6x for the wider European pharma industry. The fair ratio is 38.6x, which implies limited room for disappointment.
That kind of gap can work as a tailwind if earnings ramp quickly, or it can compress fast if sentiment cools. Which scenario you consider more realistic will depend on your portfolio objectives and risk tolerance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between cautious valuation and optimistic earnings potential feels sharp, move quickly. Check the underlying data yourself so the conviction is yours, then weigh those views against the 3 key rewards.
Looking for more Sandoz Group style investment ideas?
If Sandoz Group has sharpened your focus on pricing, risk and catalysts, do not stop here. Broaden your watchlist now using targeted screeners before opportunities move on.
- Target potential mispricing by scanning a curated set of quality businesses that still look out of favour with the 180 high quality undervalued stocks.
- Prioritise resilience by reviewing a 227 resilient stocks with low risk scores that may better match a cautious risk profile.
- Get ahead of the crowd by filtering for 613 high quality undiscovered gems before broader attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com