
3 British Founder Led Stocks With Revenue Growth Over 10%
Global bond yields have surged to multi decade highs as governments and companies face steeper borrowing costs, which puts pressure on heavily indebted businesses and passive index trackers. Founder led British companies with high insider ownership and solid balance sheets can look relatively better positioned when money is no longer cheap. This article highlights three stocks from this group that show how owner operators handle this tougher funding backdrop.
The three founder led businesses highlighted below are only a sample, with the full screen surfacing 6 more companies with similarly tight insider alignment and balance sheet strength that are not covered here. If you want to identify and analyze those additional opportunities with the same filters, head straight to the Top Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Overview: Fevertree Drinks develops and sells premium branded mixer beverages worldwide, with founder James Lamdin’s ongoing ownership closely tying leadership to outcomes.
Operations: Fevertree Drinks generates revenue primarily in the United Kingdom at £109.8 million, Europe at £102.3 million, and the United States at £94.9 million.
Market Cap: £946 million
Fevertree Drinks fits this founder-led screener because the person who helped build the premium mixer brand still has real skin in the game, which matters when the business leans on disciplined execution and careful capital allocation across international markets.
"The partnership with Molson Coors is intended to secure U.S. profit growth, but an overreliance on one strategic partner may expose Fevertree to unfavorable contract renegotiations, possible margin dilution if guaranteed royalties fail to match rising costs, and slower than expected U.S. market penetration, all of which could weigh on future profits."
What happens to Fevertree Drinks’ future appeal depends heavily on how one unresolved pressure ultimately flows through to earnings resilience.
That pressure point is exactly where Fevertree Drinks could either stall or accelerate, and the full narrative for Fevertree Drinks explains how management, margins and capital discipline might decouple from those risks.

Computacenter (LSE:CCC)
Overview: Computacenter runs large scale IT sourcing, support, and managed services for corporate and public sector clients, guided by founder linked leadership with meaningful insider ownership.
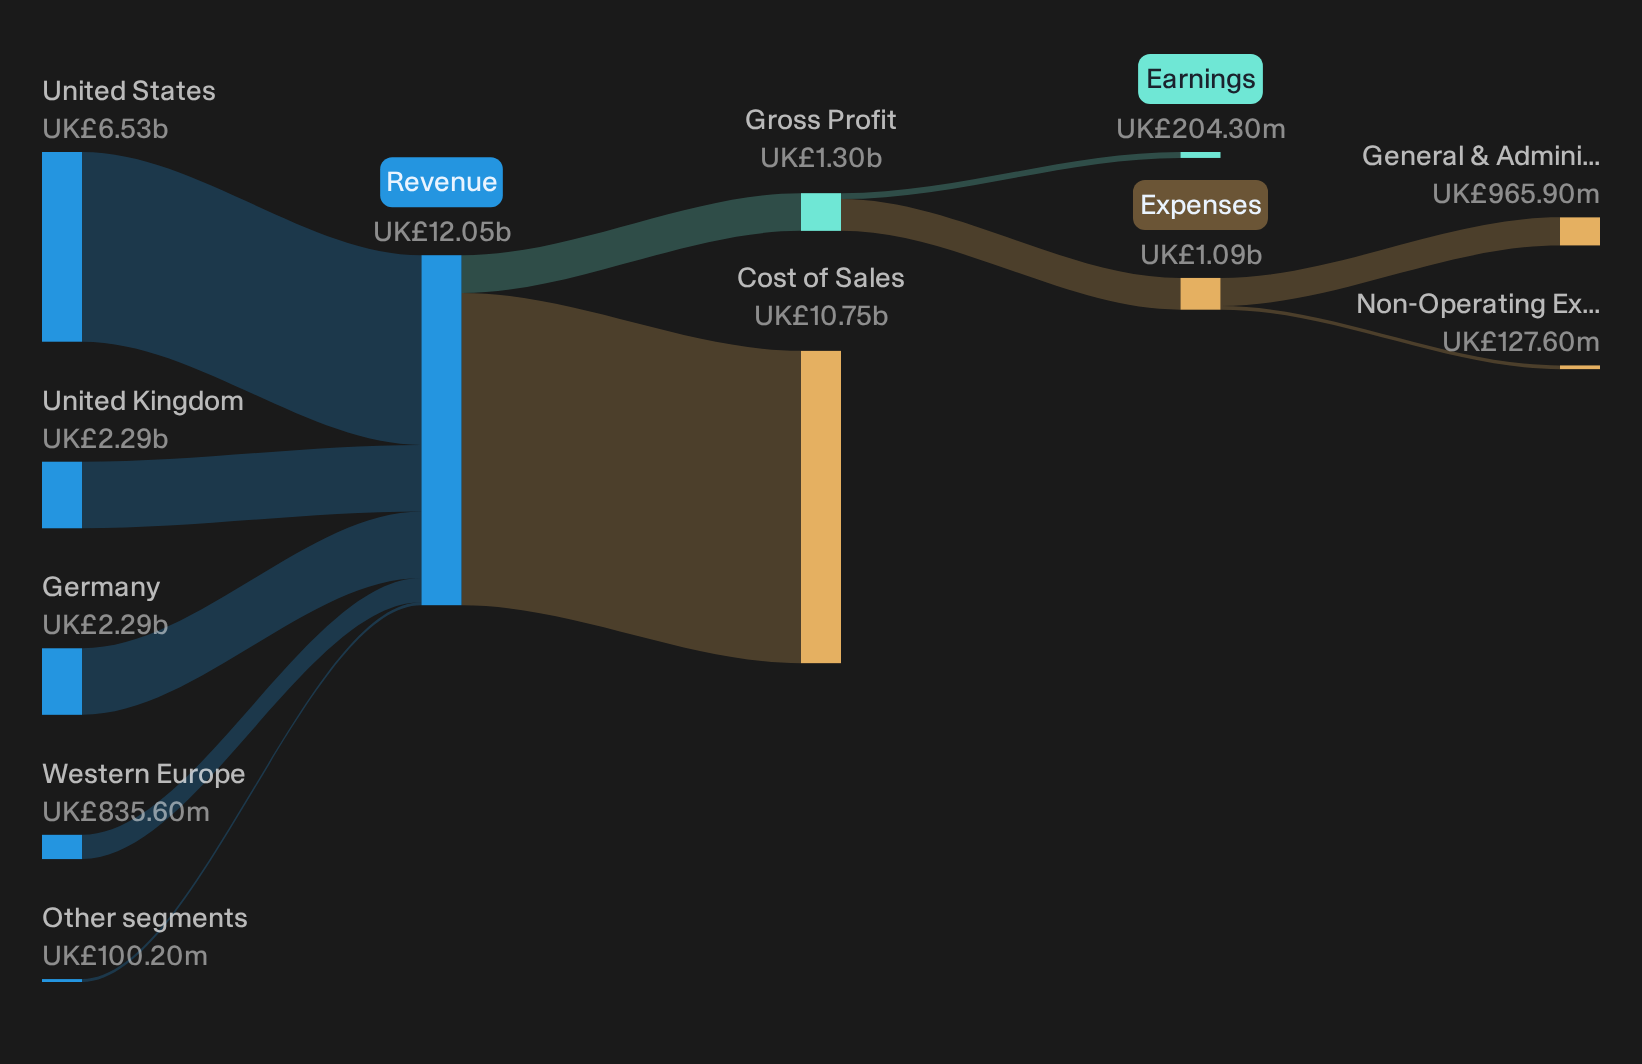
Operations: Computacenter generates £12.1b from Computer Services, supported by major markets in the United Kingdom at £2.3b, Germany at £2.3b, and the United States at £6.5b.
Market Cap: £5.7b
Computacenter brings together founder family ownership, long serving executives, and a managed services model that depends on durable, multi year client contracts. Earnings growth of 27.9% over the past year and high historical ROE sit against modest 1.7% margins. As a result, even small changes in funding costs and contract economics can have a meaningful impact on returns.
Those tight margins make the contract economics worth watching, so tap into the analysis report for Computacenter to see how Computacenter’s model could convert operating leverage into potential upside.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is a founder-influenced asset manager running long-dated infrastructure, renewable energy and private equity funds for global clients.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, with £126.4 million earned in the United Kingdom.
Market Cap: £488 million
Foresight Group Holdings fits the founder-led theme because meaningful insider ownership sits behind long-term capital locked into infrastructure and private equity mandates, so the people calling the shots commit to the same multi-year outcomes as outside shareholders.
That alignment matters most when the firm recycles cash into new funds and buybacks, which is where one recent narrative focuses.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really decides how rewarding that looks for long-term holders is how one unseen pressure ultimately feeds through to fee margins and payout capacity.
That unseen pressure is exactly what the full narrative for Foresight Group Holdings lays bare, showing where Foresight Group Holdings might see accelerating fee power and dividend headroom.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities move fast as capital chases the next breakout, while early momentum can be caught or missed in days. Scan these under the radar lists before the window drops and consider acting promptly.
- Spot potential turnarounds with strong balance sheets by scanning the list of solid balance sheet and fundamentals (11 results) and keep an eye on businesses that may handle tougher funding conditions more comfortably.
- Track early momentum in future facing themes by using the 88 AI infrastructure stocks and see which enablers of AI demand are still under the radar for now.
- Review recurring income opportunities by exploring the 1 dividend fortresses and focus on companies where higher yields meet more resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com