
Ardelyx (ARDX) Stock Still Looks Undervalued After Its 161% Five Year Run
Ardelyx has seen its share price swing sharply in recent years, and the latest pullback puts the focus squarely on what investors are paying for the company’s current sales base. With sentiment shifting after a strong multi year move, the question now is how well the stock price lines up with the revenue it is already generating.
- Over the past 5 years Ardelyx has delivered a gain of 161.1%, which puts a lot of past optimism on the line when you ask whether the present valuation can still be explained by its sales.
- Tenapanor, marketed as XPHOZAH, now has US approval for hyperphosphatemia in adults on dialysis. This can shape how investors think about Ardelyx’s future sales mix and the timing of any revenue expansion from the broader chronic kidney disease market.
- Your read on Ardelyx is one view; the desks covering it have another. See what analysts think Ardelyx's shares could be worth.
The issue now is whether Ardelyx’s current share price around US$3.42 is adequately supported by the company’s sales when judged against the Fair Ratio benchmark.
To see how Ardelyx stacks up on this theme of sales versus price, it can help to compare it with other businesses in the same bucket of 33 high quality undervalued stocks
Is Ardelyx a Bargain on Sales?
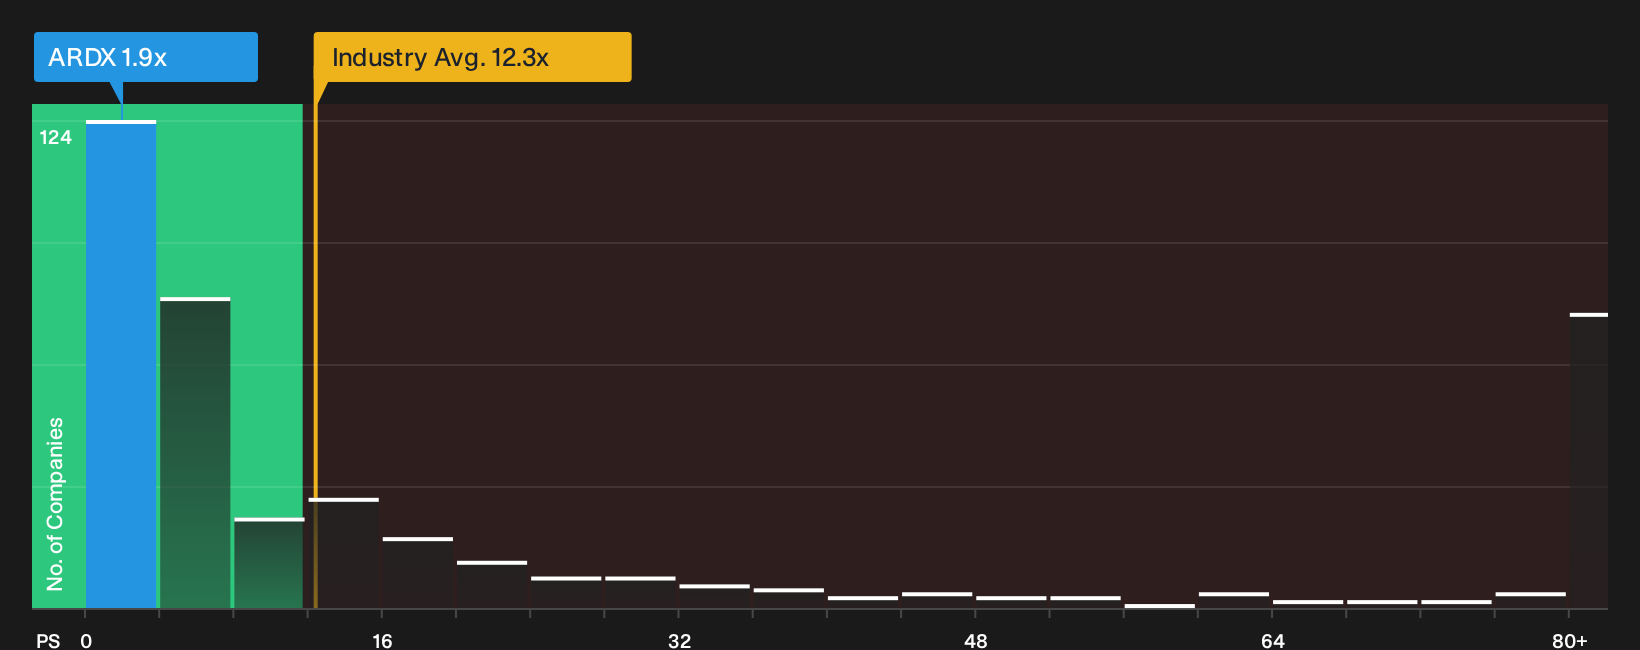
P/S works reasonably well for Ardelyx because investors are mostly weighing the value of its current and potential product revenues rather than today’s earnings. On this metric, the stock trades on a P/S of about 1.9x, which is far below the Biotechs industry average of roughly 12.3x and also well under peers at about 17.1x.
Because the Fair Ratio framework looks at Ardelyx’s growth prospects, margins, size and risk profile, it points to a higher P/S than where the shares change hands today, which flags the stock as undervalued on this measure. Approval of tenapanor for hyperphosphatemia in adults on dialysis has sharpened attention on future revenue potential, yet the current multiple still sits at a marked discount to the level implied by that Fair Ratio benchmark. Explore the numbers behind Ardelyx's P/S valuation.
The Ardelyx Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Ardelyx valuation puzzle leaves off. They spell out which assumptions on future growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today's price on the market. Each scenario then focuses on the drivers behind its view of fair value so you can weigh those inputs against the actual results as they come through.
One of the top community narratives on Ardelyx: 73% undervalued
"Strategic partnerships and licensing deals, including existing international collaborations and potential future EU partnerships, provide non-dilutive capital through milestones and royalties."
Discover why this Narrative puts Ardelyx at 73% undervalued.
One more Ardelyx check that belongs beside the valuation work
Price to sales and peer comparisons only tell part of the Ardelyx story, because the internal risk checks still flag specific concerns that deserve your attention before you lean on any valuation signal. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com