
CVS Health (CVS) Stock Still Looks Reasonable On Its 40% 3 Year Return
CVS Health has delivered a solid multi‑year return while the share price has recently pulled back, which puts fresh attention on whether the current valuation is still supported by its earnings power. With new initiatives in areas like oncology care and behavioral health in the mix, the key issue for you is how much of that story is already reflected in today's price.
- Over the past 3 years CVS Health has returned about 40.0%, which raises the question of how much of its earnings strength is already embedded in the share price.
- Aetna's expansion of bundled oncology prior authorizations and CVS Health's participation in broader chronic care programs may influence expectations for future profit quality and the timing of cash flows from its insurance and care management operations.
- The analysts covering CVS Health have run their own numbers. See what analysts think CVS Health's shares could be worth.
For investors, the debate is whether CVS Health's current share price is adequately justified by the earnings it is generating today and what the business can reasonably earn over time.
If you want to stress test whether CVS Health's current earnings story feels rich or reasonable, compare it with a wider set of 33 high quality undervalued stocks.
Is CVS Health a Bargain on Earnings?
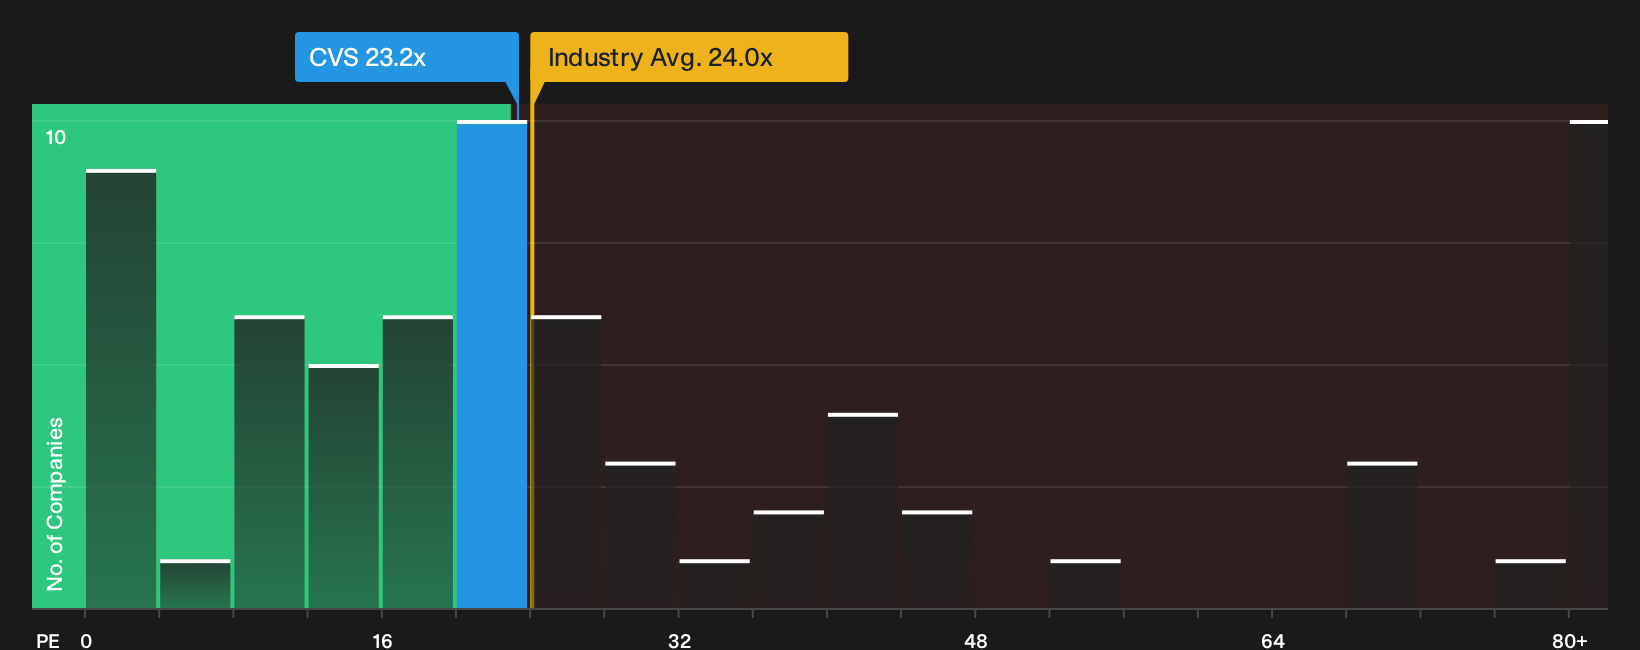
The P/E ratio suits CVS Health because earnings remain a central yardstick for how investors judge large, diversified healthcare groups. CVS Health currently trades on a P/E of 23.2x, compared with a Healthcare sector average of about 24.0x and a peer group closer to 19.3x. Because the fair multiple model adjusts for factors like growth profile, profitability, size and risk, the present P/E comes in below what that tailored yardstick implies.
Because Aetna is expanding bundled oncology prior authorizations and CVS Health is aligning with new behavioral health programs, the market is weighing fresh expectations for the quality and timing of future profit streams without fully closing that gap. For you, the takeaway is that the stock still prices in a lower earnings multiple than the custom benchmark suggests, so the current valuation assumes a more cautious outlook on the business than the model itself points to. Explore the numbers behind CVS Health's P/E valuation.
The CVS Health Narrative: What Would Justify Today's Price?
Narratives for CVS Health sit on the Community page and act as a bridge from the P/E puzzle above by spelling out which combinations of growth, margins and earnings would need to occur for the stock to be worth materially more or less than today. Each scenario ties a fair value estimate to a clear set of potential catalysts and risks so you can track over time which version of CVS Health's story appears to be playing out.
One of the top community narratives on CVS Health: 15% undervalued
"CVS is no longer trying to be a faster pharmacy. It’s trying to be a more complete healthcare system…"
Discover why this Narrative puts CVS Health at 15% undervalued.
One more cross check for CVS Health before you stop at the P/E
There is another reference point that sits outside today's multiples. It sits in how professionals currently map out CVS Health's earnings a few years from now, and it can be a useful comparison beside your own expectations. Explore where analysts expect CVS Health to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com