
Earnings Outlook Upgrade Might Change The Case For Investing In Nutex Health Stock (NUTX)
- Nutex Health recently reported a sharply stronger earnings outlook, with the Zacks Consensus Estimate for current year earnings improving 21.4% over the last 60 days and expected earnings growth for the year now projected at more than 100%.
- This rapid shift in Nutex Health’s profit expectations highlights how the company’s physician-led, tech-enabled micro hospitals and population health operations are beginning to translate operating momentum into a materially different earnings profile.
- We will explore how Nutex Health's investment narrative around micro hospitals and value-based care is reshaped by this sharply upgraded earnings outlook.
Scan how Nutex Health’s upgraded earnings outlook compares to other potential breakouts by reviewing the hand picked 33 high quality undervalued stocks that are moving on quality and value right now.
Nutex Health Investment Narrative Recap
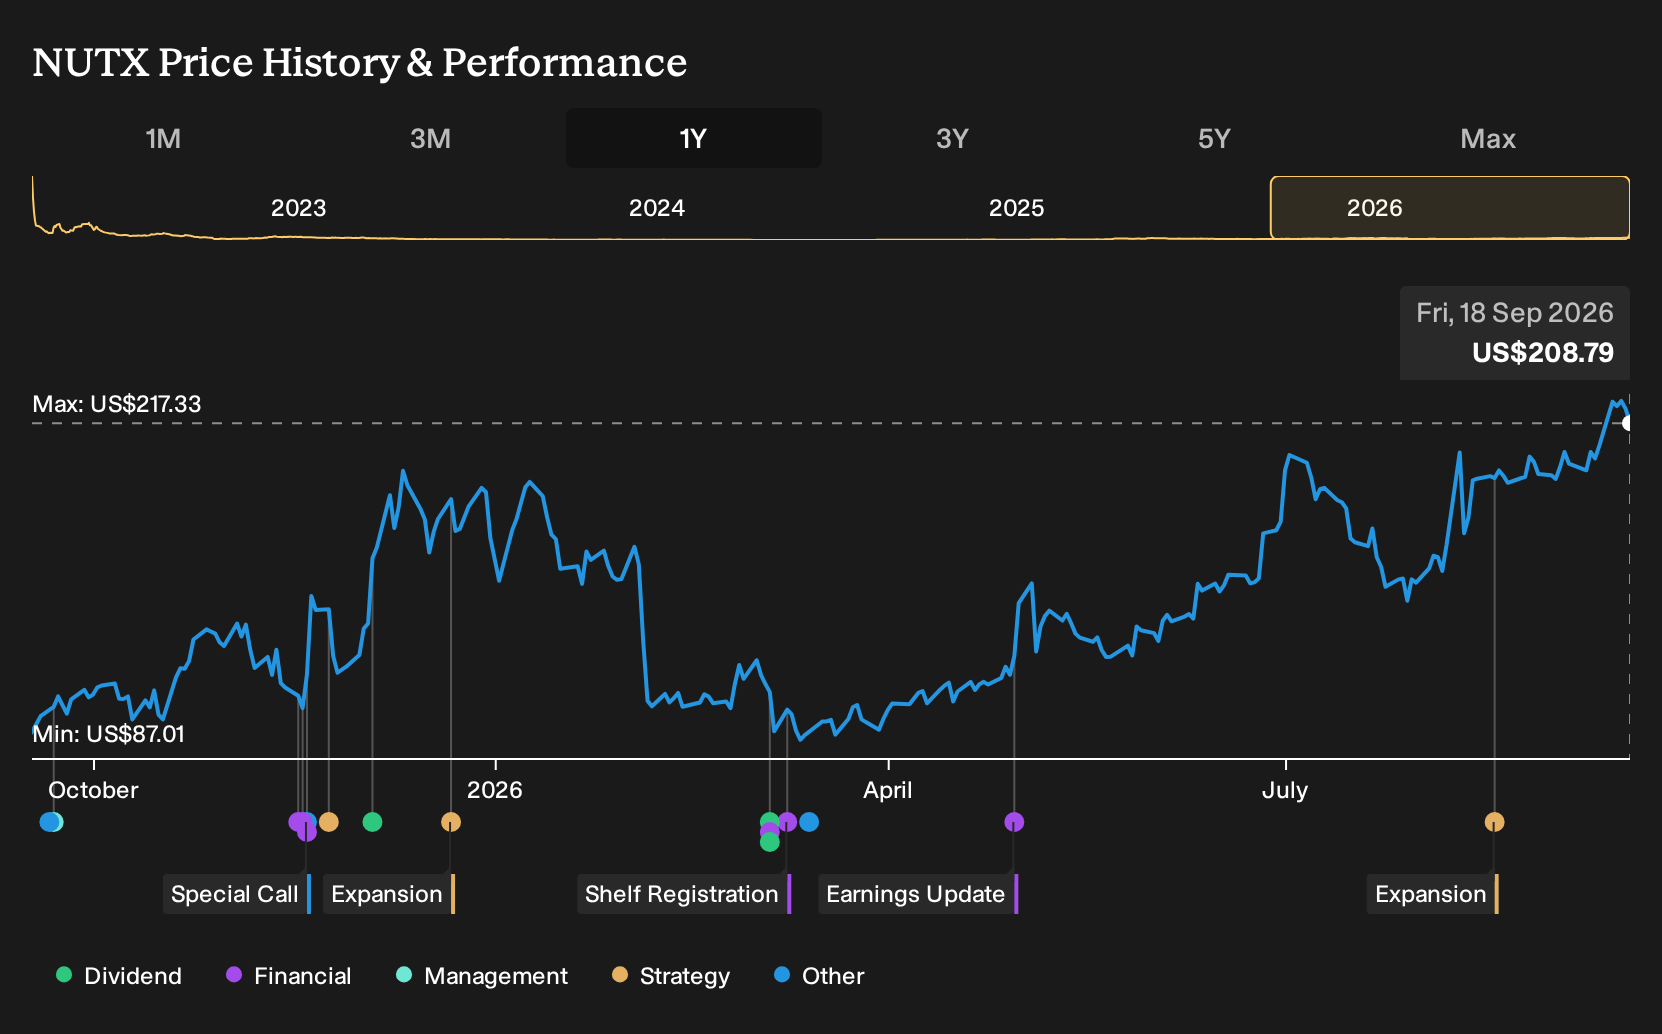
For Nutex Health, the big picture you need to buy into is that its physician-led micro hospitals and population health platform can keep converting strong patient demand and value-based contracts into durable earnings, not just arbitration driven windfalls. The recent 14.8% four week share move and sharply higher earnings outlook put more weight on execution around micro hospital ramp up and population health scale as the key near term catalyst.
The biggest risk still sits with concentration in No Surprises Act arbitration and the cash collection that follows. Those regulatory and payment uncertainties have not changed with this earnings upgrade. If IDR rules, insurer behavior, or award collection weaken from here, the story around high reported profitability could look more fragile, even with better short term forecasts.
The most relevant recent data point is the expected earnings growth rate of more than 100% for the current year, alongside a 21.4% improvement in the Zacks Consensus Estimate over 60 days. That kind of step change lines up with Nutex Health’s reported jump in net profit margins to 21.2% and the move from one off losses toward a cleaner earnings base.
For investors, the link back to potential catalysts is straightforward. Stronger profit expectations raise the bar on Nutex Health’s ability to keep margins supported as IDR volumes, new facility openings and population health contracts mature. The risk side is that large one off items and arbitration heavy revenue still cloud how repeatable this earnings run rate is if policy, payer behavior, or facility level performance soften.
Nutex Health Earnings and Revenue Assumptions
Nutex Health's long term story in the analyst models revolves around moderate top line expansion and only a modest squeeze on profitability. Forecasts call for revenue to grow by 8.1% each year over the next 3 years while profit margins edge down from 21.2% today to 20.6% over the same period. Consensus projections point to earnings of $220.6 million by 2029 compared with $179.9 million today. This implies an earnings increase of about 23% in dollar terms that needs to materialize as the micro hospital and population health platform scales.
Nutex Health's narrative projects $1.1b revenue and $220.6 million earnings by 2029. This requires 8.1% yearly revenue growth and an earnings increase of about $40.7 million from $179.9 million.
Those same analyst expectations underpin the current fair value debate around Nutex Health. The group of covering analysts has settled on a consensus price target of $283.0, anchored on the idea that by 2029 the business could be generating $1.1b of revenue and $220.6 million of earnings and trading on a P/E of 9.8x. That prospective multiple sits below the cited 25.0x P/E for the broader US Healthcare industry in the report. This signals that the bullish case here relies more on solid cash generation from a lower multiple rather than a premium valuation story.
At a share price of $193.24 as of the report, the $283.0 target sits 31.7% higher. The spread between the most optimistic analyst at $325.0 and the most cautious at $200.0 shows that views on Nutex Health remain highly split, especially given that some analysts still frame parts of the underlying business as in decline. For you as an investor, the key step is to check whether the assumed 8.1% annual revenue growth, slight margin compression, and lift in earnings to $220.6 million by 2029 feel realistic once you factor in arbitration exposure, facility rollout pacing, and the traction in population health contracts.
Uncover why Nutex Health's fair value indicates a 36% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
You can read Nutex Health very differently if you fixate on one alternate risk. The most cautious analysts focus on out of network arbitration staying fragile, which is why they only penciled in revenue growth of 7.9% a year and earnings of about US$215.3 million by 2029. Their US$200.0 price target tells you opinion spread is wide, and this fresh earnings news could easily shift both narratives.
Explore 5 other Nutex Health fair value estimates, including one that suggests as much as 84% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nutex Health research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nutex Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nutex Health's overall financial health at a glance.
Looking for more Nutex Health sized opportunities?
If Nutex Health has you rethinking where the next inflection point could come from, broaden the watchlist using the Simply Wall St Screener so you can compare this story with other potential candidates on your radar.
- If you want potential upside with more balance sheet resilience, start with a list of solid balance sheet and fundamentals (23 results) that align with stricter financial health filters.
- For investors who care most about valuation support, scan a curated 33 high quality undervalued stocks that combine earnings power with disciplined pricing.
- When stability and income matter more than price swings, focus on cash return potential through a targeted 6 dividend fortresses that offer higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com