
How $1b Buyback At AerCap Holdings Has Changed Its Investment Story
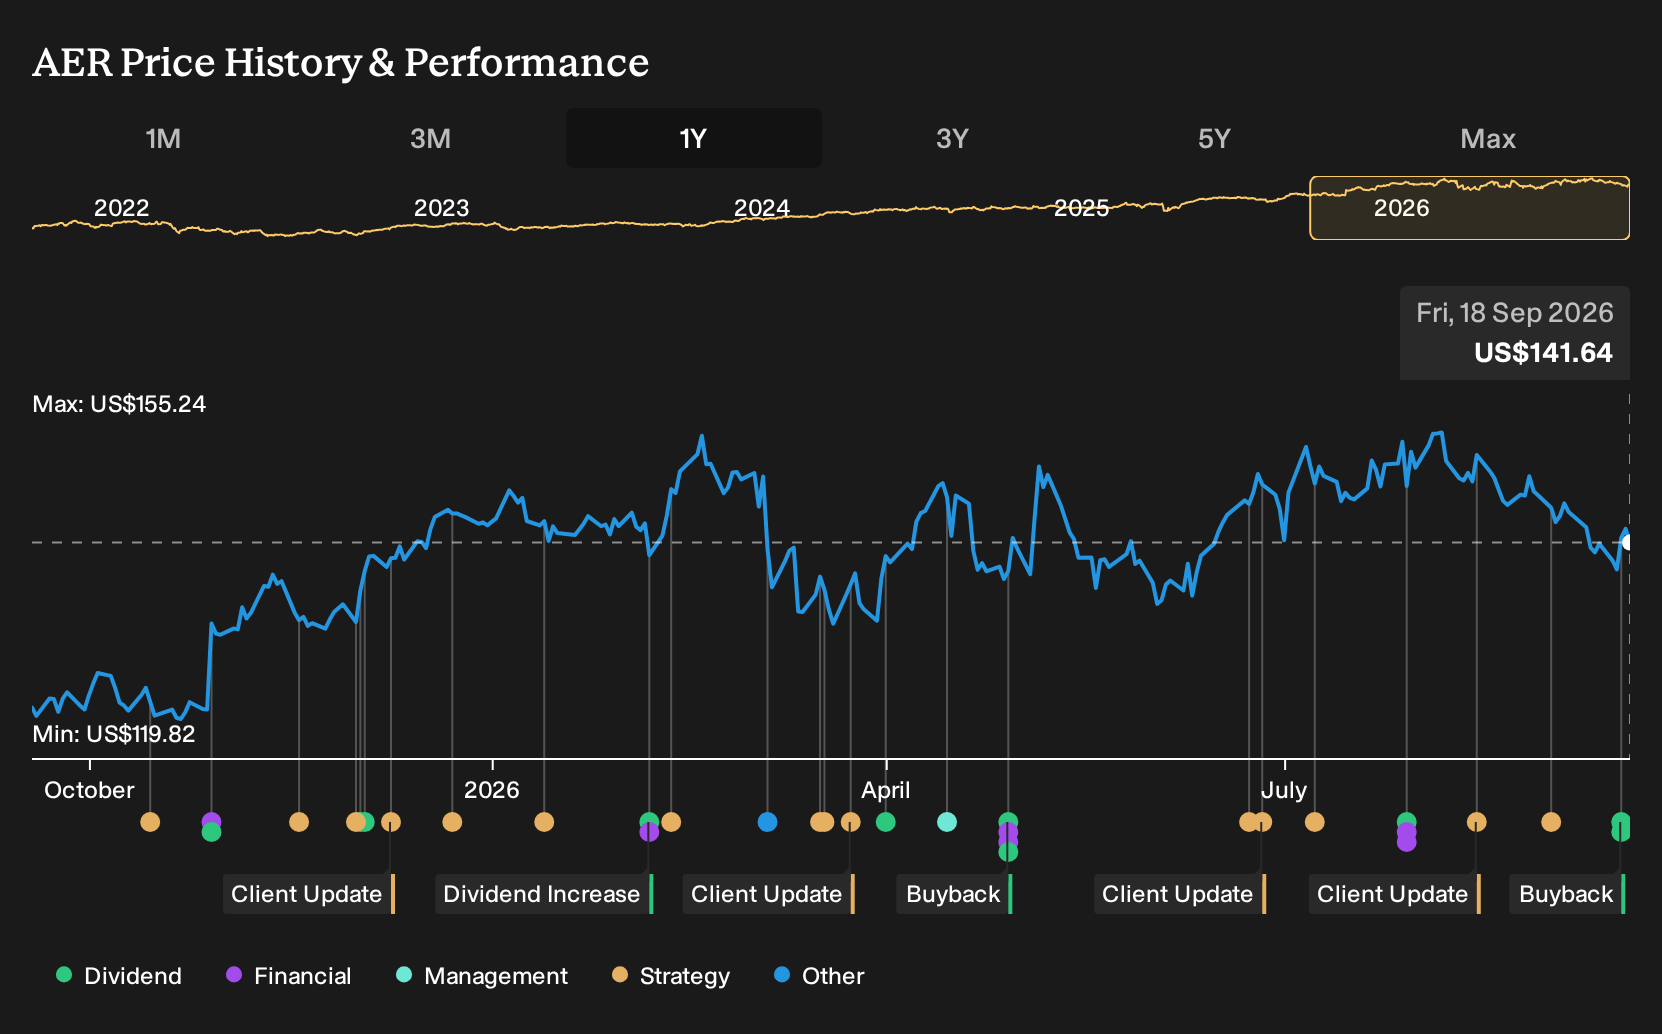
- AerCap Holdings announced that its board authorized a share repurchase program on 16 September 2026, allowing the company to buy back up to US$1.0b of its stock through 30 June 2027. The program will be funded by cash on hand and cash generated from operations.
- The new buyback plan indicates that AerCap Holdings is comfortable using ongoing operating cash flows for capital returns. This is relevant for investors who are weighing future balance sheet flexibility against potential benefits from a smaller share count.
- We will now assess how AerCap Holdings' US$1.0b repurchase authorization might influence the existing investment narrative built around tight aircraft supply.
Scan how AerCap Holdings' buyback fits alongside other capital return stories by reviewing a curated set of 33 high quality undervalued stocks that also combine strong cash generation with active repurchase programs.
AerCap Holdings Investment Narrative Recap
To own AerCap Holdings, you need to be comfortable with an aircraft leasing model that relies on tight supply, high utilization and long contracts to turn a large asset base into cash flow. The new US$1.0b buyback authorization does not change that core thesis. The more immediate swing factor still sits in lease yields and remarketing outcomes as OEM deliveries and airline health evolve.
The biggest risk remains overcommitting capital into aircraft and repurchases if lease rates soften or credit issues emerge among key airline customers. Using cash on hand and operating cash to fund the buyback keeps leverage optics in focus, so execution on funding costs and interest coverage remains critical over the next year.
The new share repurchase plan, announced on 16 September 2026, is the most recent signal to watch. It runs through 30 June 2027 and is sized at up to US$1.0b. For shareholders, this links directly to the existing narrative that AerCap Holdings is willing to return capital while the aircraft market is supported by tight supply and high extension rates.
That decision aligns with the main catalysts and risks already in view. Analysts expect revenue and earnings to decline over the next three years, while the stock trades on a P/E of 6.4x compared with an estimated fair P/E of 15.1x. Progress on lease renewals, asset sales and credit quality will matter even more now that management has committed additional cash to reducing the share count.
How AerCap Holdings' Forecasts Frame the Buyback
AerCap Holdings' current analyst narrative points to revenue of US$8.3b and earnings of US$2.4b by 2029, off a base of US$3.4b in earnings today. That path assumes a 2.6% yearly decline in revenue and an earnings reduction of US$1.0b from current levels to the 2029 consensus figure.
Uncover why AerCap Holdings' fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$179 to US$345 per share, so retail views on AerCap Holdings already cover a wide valuation gap. Those opinions pre date the US$1.0b buyback announcement. You should weigh them against future shifts in aircraft supply, lease demand and customer credit health.
Explore another AerCap Holdings fair value estimate, including one that suggests as much as 143% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AerCap Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AerCap Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AerCap Holdings' overall financial health at a glance.
Looking for more AerCap Holdings style investment ideas?
If the AerCap Holdings story has you thinking about where else disciplined capital allocation and solid fundamentals might show up, the Simply Wall St Screener can help you widen the search without losing focus on quality.
- For those who want income potential backed by sturdier balance sheets, scan a curated set of 6 dividend fortresses that aim to pair yield with resilience.
- If capital preservation sits high on your list, filter for a 30 resilient stocks with low risk scores and compare how their risk profiles line up with your comfort zone.
- When you want ideas that have not yet drawn broad attention, start with a 16 high quality undiscovered gems and see which fundamentals catch your eye.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com