
Does MillerKnoll (MLKN) Trade At A Discount To Its Earnings?
MillerKnoll has seen its share price move around over the years, and the current US$20.66 level puts a fresh spotlight on what investors are really paying for its earnings power. With the stock showing mixed returns across different time frames, the question now is how well the current P/E lines up with the profitability of the business.
- The share price declined 40.5% over the past 5 years, which puts extra weight on whether the earnings story today supports a different outcome over the next stretch.
- The business depends heavily on converting design demand into steady profits, so the durability of margins and cash conversion can shape how much investors are prepared to pay for each dollar of earnings.
- The analysts covering MillerKnoll have run their own numbers. See what analysts think MillerKnoll's shares could be worth.
The issue now is whether MillerKnoll's current price is adequately supported by its earnings profile when set against the Fair Ratio benchmark.
If you want more context on whether MillerKnoll's current P/E feels fair, it can help to compare it with other companies screened for 33 high quality undervalued stocks.
Does MillerKnoll Look Undervalued on Earnings?
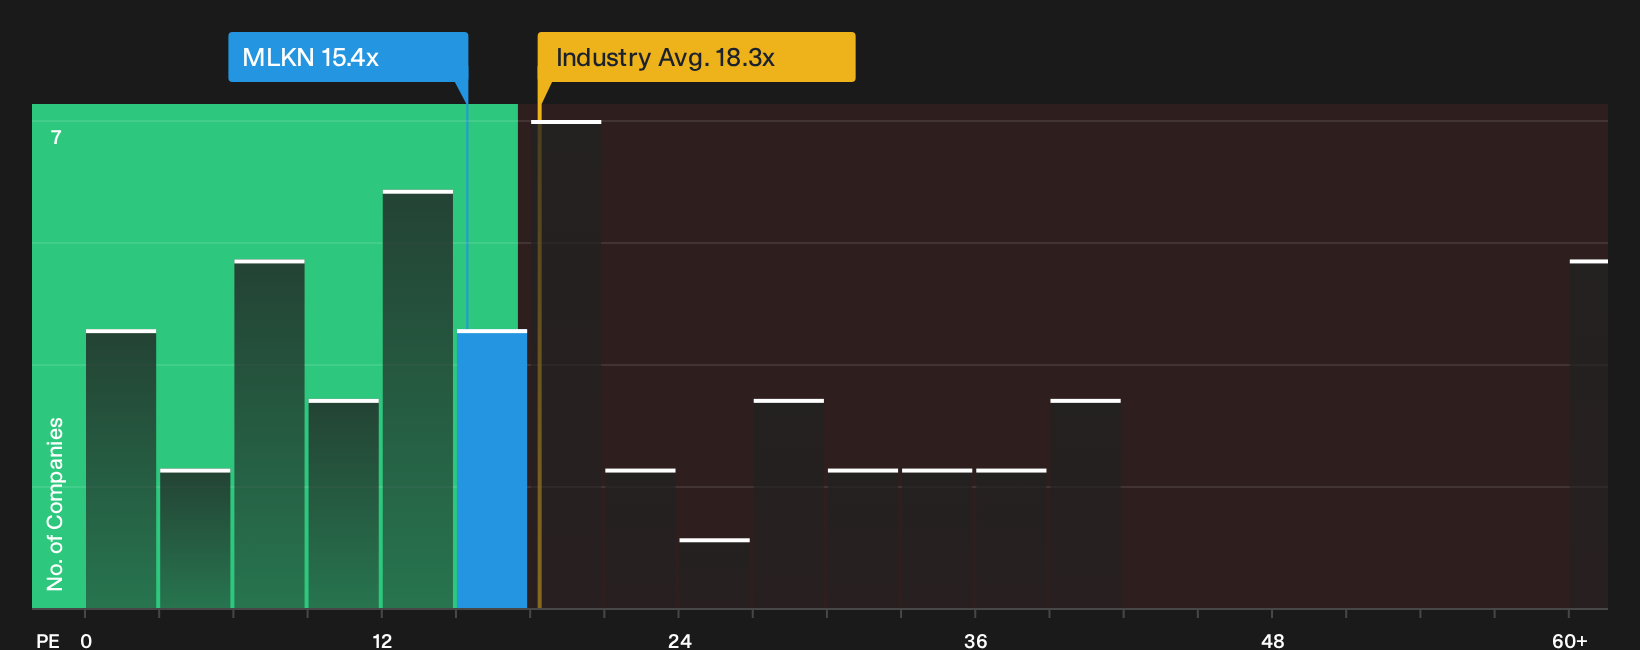
The P/E ratio suits MillerKnoll because earnings are a core reference point for how investors value a mature design led business. At the current share price, MillerKnoll trades on a P/E of 15.4x, which is below both the Commercial Services industry average of 18.3x and the peer group on 13.4x. That puts the stock in a space where it is cheaper than the broader sector benchmark on this measure, yet still priced at a small premium to closer peers.
The Fair Ratio model, which blends factors such as MillerKnoll’s profitability profile, scale and sector risks into a tailored benchmark, points to a higher multiple than the one the market is assigning today. This gap suggests investors are paying a lower P/E than the company specific characteristics might justify, so the share price embeds a degree of caution around future earnings delivery. For anyone tracking how much they are paying for each dollar of profit, that tension between the simple P/E and the Fair Ratio benchmark is where the real work starts. Explore the numbers behind MillerKnoll's P/E valuation.
The MillerKnoll Narrative: What Would Justify Today's Price?
Narratives pick up where valuation ratios leave off for MillerKnoll. They spell out which paths for growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than today. Each scenario links a specific fair value estimate to a clear mix of potential catalysts and risks, so you can later compare those storylines with what actually happens in the business. These sit on Simply Wall St's Community page.
One of the top community narratives on MillerKnoll: 41% undervalued
"The restructuring of MillerKnoll's reporting segments to better align with strategic goals could improve operational clarity and facilitate growth..."
Discover why this Narrative puts MillerKnoll at 41% undervalued.
One more angle on MillerKnoll that could shift how you see the valuation
Price multiples tell you what the market pays today, while analyst models sketch where earnings and business momentum might be projected a few years from now. Explore where analysts expect MillerKnoll to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com