
Viasat (VSAT) On New Satellite And Equatys Deal Has Valuation Back In Focus
Viasat (VSAT) has just completed a major step in its satellite roadmap, with the ViaSat-3 F2 satellite entering service across the Americas and the Equatys joint platform with Space42 moving forward for global direct-to-device connectivity.
The recent ViaSat-3 milestone and Equatys partnership arrive during a period of strong investor interest in Viasat, with the share price at $76.38 after a 1-day share price return of 4.60% and a year-to-date share price return of 102.98%. The 1-year total shareholder return of 157.95% and 3-year total shareholder return of 282.09% point to momentum that recent satellite and direct to device announcements are likely reinforcing rather than creating from scratch.
Spot similar satellite and connectivity plays showing strong momentum and infrastructure build out by scanning our curated list of 88 AI infrastructure stocks.The question now is whether Viasat’s surge reflects a business that is catching up to its new satellite and D2D ambitions, or a valuation that has simply rerated on sentiment ahead of the numbers.
Most Popular Narrative: 27% Undervalued
Viasat's most followed valuation story pegs fair value at $103.94 versus the last close at $76.38. The current share price sits well below the narrative anchor and places significant focus on how the satellite and spectrum thesis plays out.
Viasat is poised to benefit from growing global demand for secure connectivity and resilient communications, driven by heightened geopolitical instability and increased threats to network and data center security, which is fueling double-digit growth in its Defense and Advanced Technologies segment and should drive sustained revenue expansion.
See why 30 investors see Viasat as 27% undervalued.
Result: Fair Value of $103.94 (UNDERVALUED)
Still, the Viasat story hinges on heavy ViaSat-3 and Inmarsat spending and on regulatory outcomes around spectrum that could slow or dilute the cash flow upside.
Find out about the key risks to this Viasat narrative.
Another View on Viasat’s Valuation
The analyst narrative points to Viasat trading below a fair value of $103.94. The SWS DCF model presents a different picture. On that framework, the shares at $76.38 are above an estimated future cash flow value of $55.93, which leans toward overvaluation. So which story do you trust more: cash flows or narrative targets?
For a closer look at how those cash flow assumptions are built and where they could be wrong, review the Look into how the SWS DCF model arrives at its fair value..
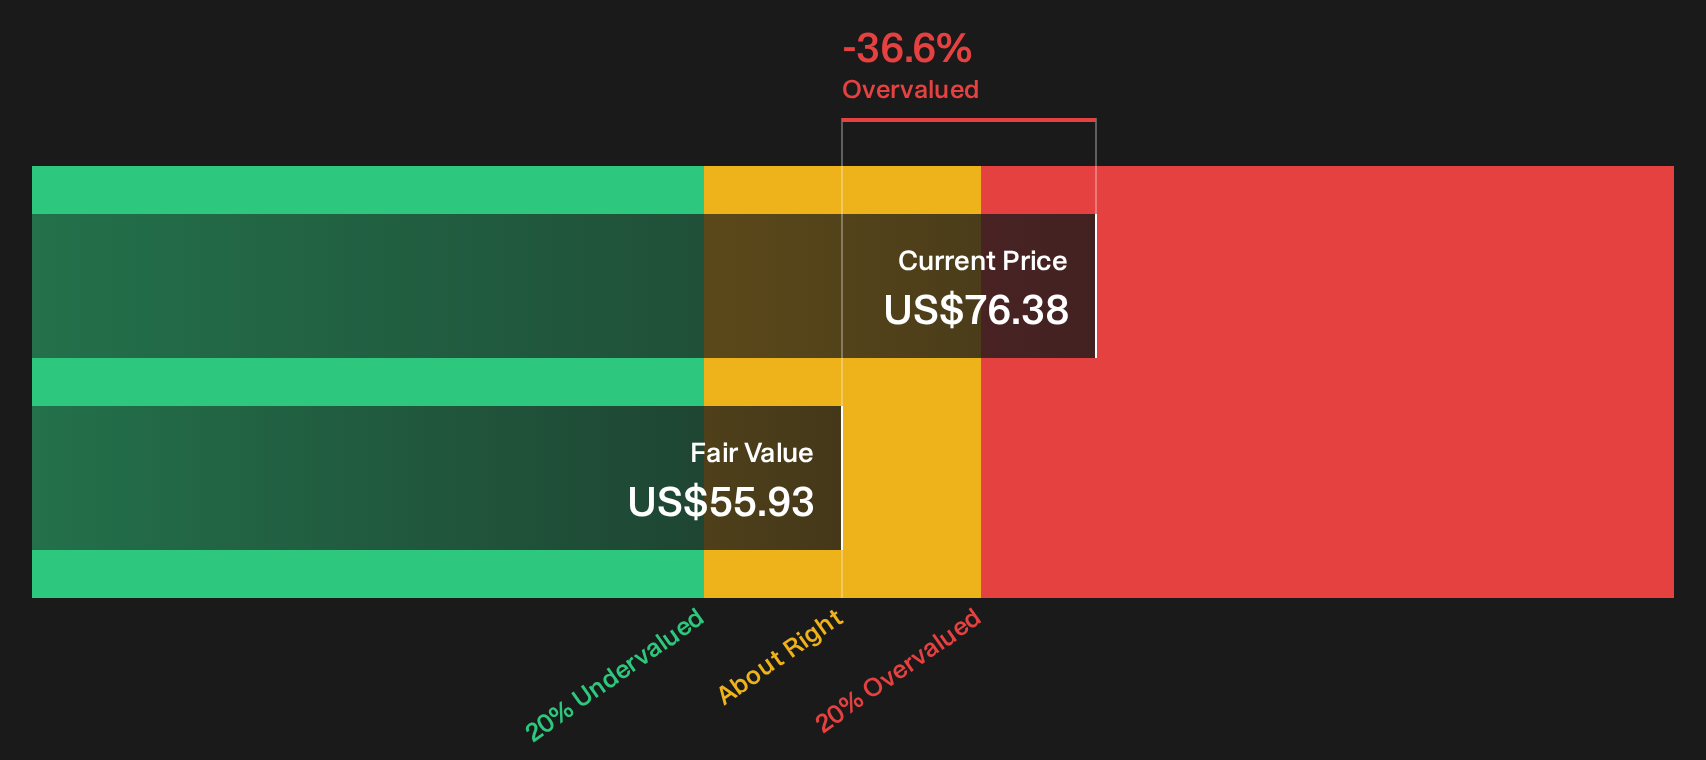
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Viasat for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between cash flow models and narratives on Viasat feels sharp, that is the point. Act quickly, examine the numbers directly, and weigh them against the 4 important warning signs.
Looking for more Viasat investment ideas?
Broaden your watchlist now by scanning other potential opportunities on Simply Wall Street’s Screener, so you do not miss the next setup that fits your approach.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by checking the 16 high quality undiscovered gems.
- Focus on stability and capital preservation by filtering for the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com