
WPIL Heads These 3 Indian Undervalued Stocks To Watch
Rising global bond yields and higher borrowing costs are forcing investors to think harder about where every rupee goes. In that kind of market, Indian companies that generate solid cash in the here and now yet trade below what detailed cash flow models suggest can look especially interesting. This article highlights three such stocks from a discounted cash flow based screener that may appeal to patient value seekers.
The three stocks covered next are only a sample of what this cash flow focused screen throws up, since the full list also flags 3 more companies with similarly interesting stories that are not discussed in the article. To go straight to the source and identify your own high conviction ideas, analyze the full Undervalued Stocks Based On Cash Flows list using the Undervalued Stocks Based On Cash Flows screener.
WPIL (BSE:505872)
Overview: WPIL designs, manufactures and services irrigation, municipal and industrial pumping systems that support long term water infrastructure cash flows.
Operations: WPIL generates about ₹10,710 million from Pumps and Accessories and ₹9,055 million from Project works, with revenue skewed toward international markets.
Market Cap: ₹42.3 billion
WPIL appeals to cash flow focused investors because its engineered pumps and water projects can produce ongoing project and service income that underpins discounted cash flow value.
"Rising global focus on water infrastructure, including river linking, wastewater and municipal water projects, is feeding into WPIL's consolidated project and product order backlog of about ₹5,200 crores."
What happens to those projected cash flows if a single key assumption on project execution timing and margins starts to slip?
If that execution risk is what you keep circling back to, read the full narrative for WPIL to see how WPIL's order book, capital needs and cash returns could be decoupling.
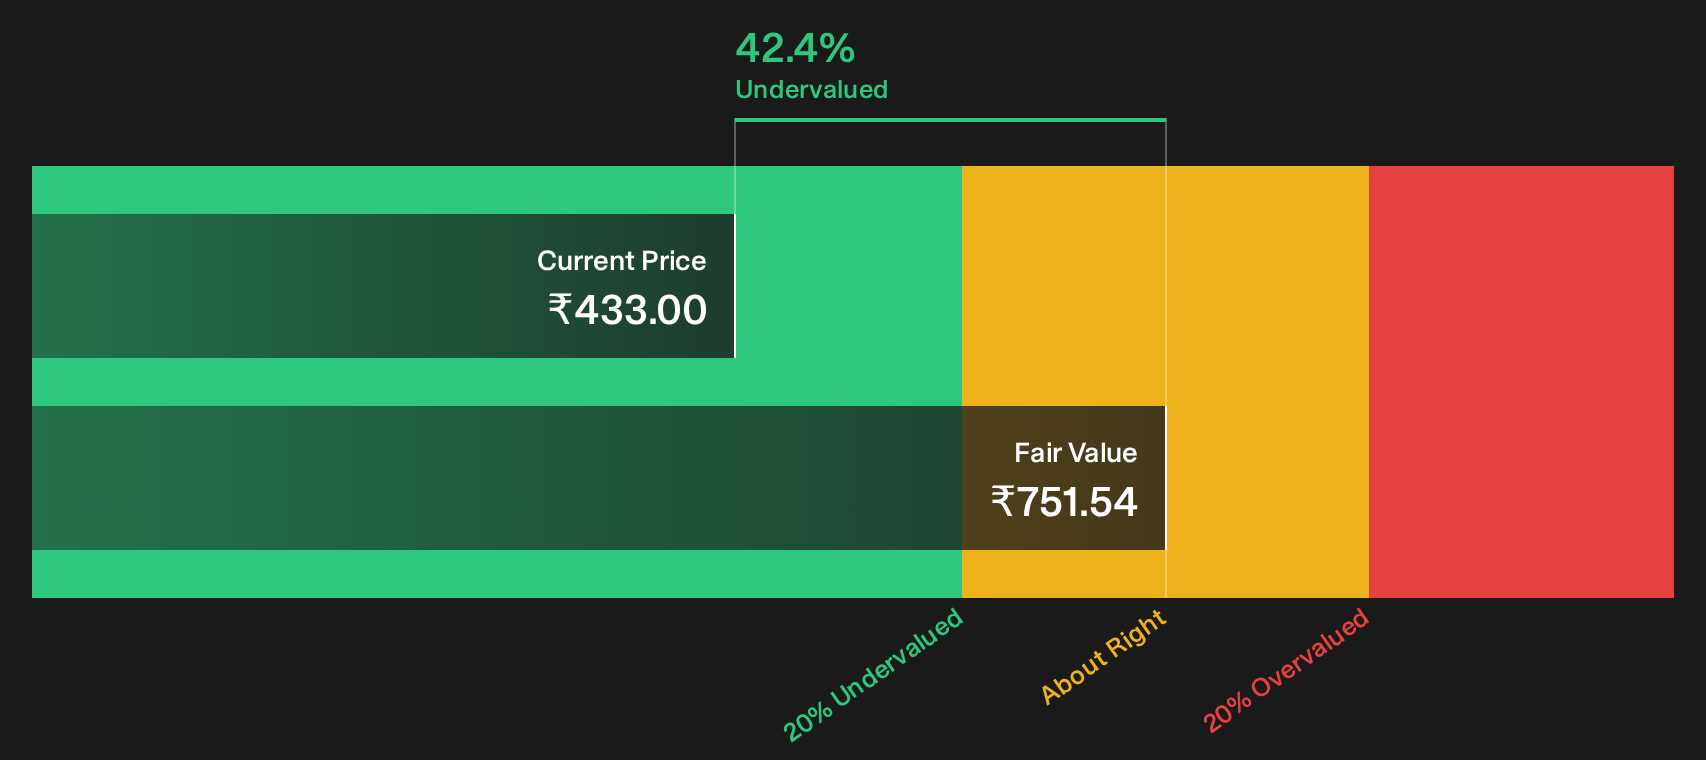
Flair Writing Industries (NSEI:FLAIR)
Overview: Flair Writing Industries designs and sells pens, creative stationery and houseware, with pen and stationery cash flows central to its DCF story.
Operations: Flair Writing Industries generates about ₹12,808 million in revenue from its Writing Instruments & Other Allied(s) segment that anchors group cash inflows.
Market Cap: ₹24.8 billion
Flair Writing Industries matters for this cash flow focused screen because its everyday pens and school supplies spin off recurring earnings that can be priced against detailed DCF work rather than hope.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
The real swing factor is how that shift in mix filters through working capital and free cash flow if demand ever cools suddenly.
If that cooling risk is what you are testing, read the full narrative for Flair Writing Industries for how Flair Writing Industries’ mix shift could still accelerate cash generation.
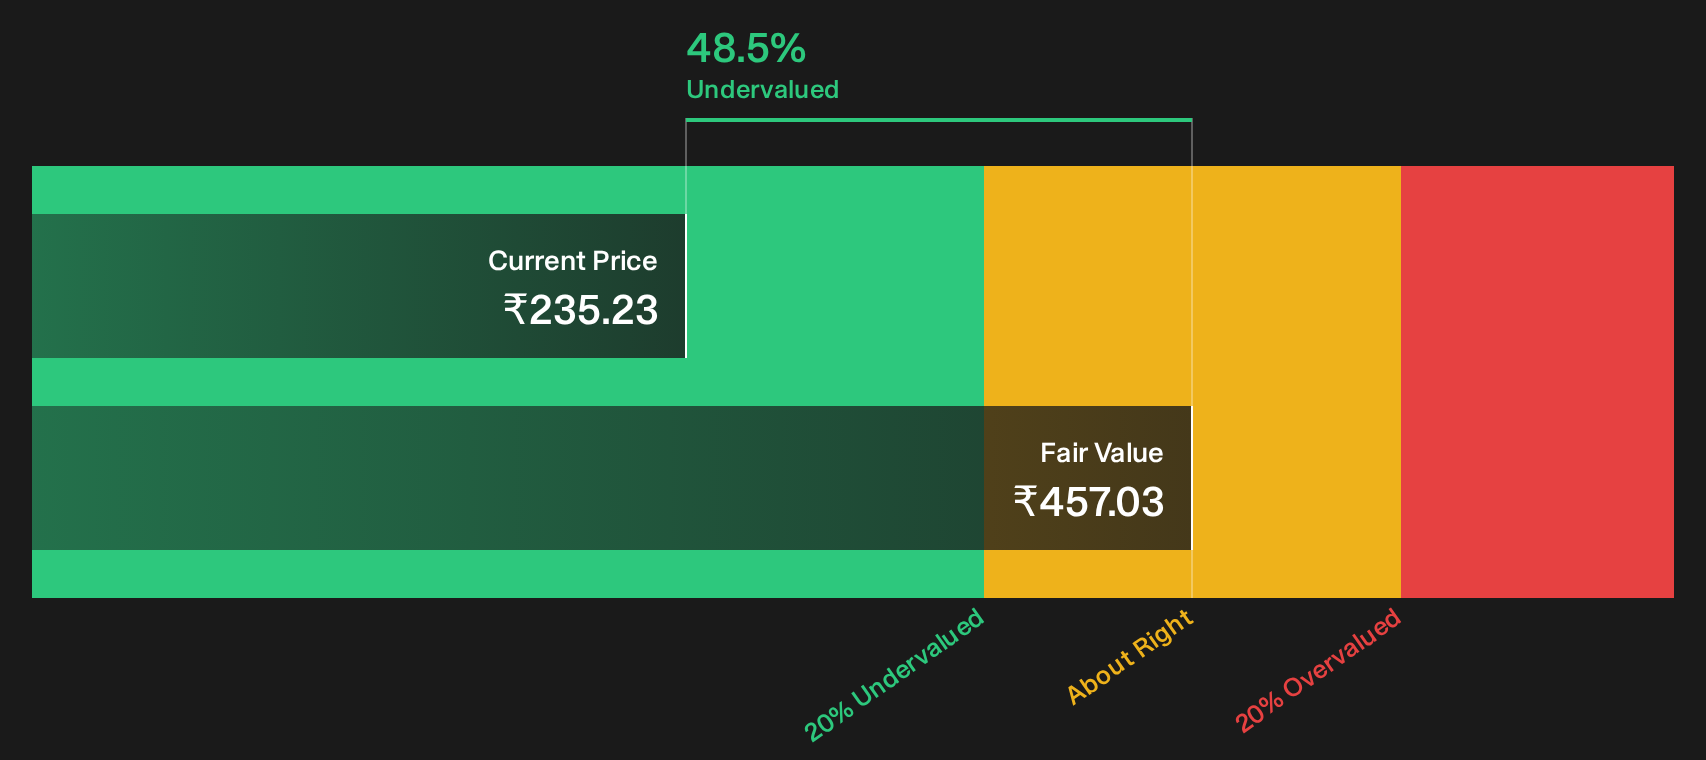
TeamLease Services (NSEI:TEAMLEASE)
Overview: TeamLease Services runs large scale contractual and temporary staffing, payroll and HR solutions for employers across multiple sectors in India.
Operations: TeamLease generates about ₹110.07b from General Staffing, ₹7.02b from Specialised Staffing and ₹2.47b from Other HR Services.
Market Cap: ₹20.4b
For the Undervalued Stocks Based On Cash Flows theme, TeamLease Services matters because its long term staffing and payroll contracts convert workforce outsourcing into steady service fees and recurring cash generation that can be priced through discounted cash flow work rather than short term sentiment.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
What could really move margins and cash yields from here is how one still underpriced driver in that broader shift ultimately plays out.
That underpriced driver is exactly what the full narrative for TeamLease Services unpacks, revealing how apprenticeship growth and HR services could be masking a much bigger cash story.

Seeking Fresh Alternatives Before They Fly
Markets move fast. Breakout stories gain momentum, tired ideas get dropped and quiet winners stay under the radar for now. Scan fresh line ups before the crowd and consider opportunities early.
- Identify resilient cash generators that still price in caution by scanning the curated 227 resilient stocks with low risk scores while the gap between quality and valuation remains a factor.
- Explore the potential infrastructure and electrification wave by working through a hand picked set of 38 power grid technology and infrastructure stocks before grid upgrades are fully priced in.
- Assess opportunities ahead of a possible nuclear build out by tracking curated 19 nuclear energy infrastructure stocks that could benefit if long term demand for low carbon power accelerates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com