
Is Upstart Holdings (UPST) Trading At A Premium Or About Right?
Upstart Holdings has seen its share price come under heavy pressure in recent years, and that slide puts a spotlight on a simple question for you as an investor. Is the current valuation of Upstart stock still supported by what the business is earning today and what those earnings suggest it could deliver over time.
- Over the past 5 years, the share price has fallen about 92.4%, which puts a lot of weight on whether the remaining market value lines up with the company’s earnings power.
- The business relies on turning its lending and credit decision platform into sustained, profitable volume, which can influence how durable its earnings are and how much investors are willing to pay for them.
- The analysts covering Upstart Holdings have run their own numbers. See what analysts think Upstart Holdings's shares could be worth.
The stock’s next move may depend on whether today’s price looks in line with what Upstart earns now and what those earnings suggest about its future potential.
If you want to stress test whether Upstart Holdings' valuation question shows up in other opportunities too, scan a wider field of 33 high quality undervalued stocks.
Does Upstart Holdings Look Fairly Valued on Earnings?
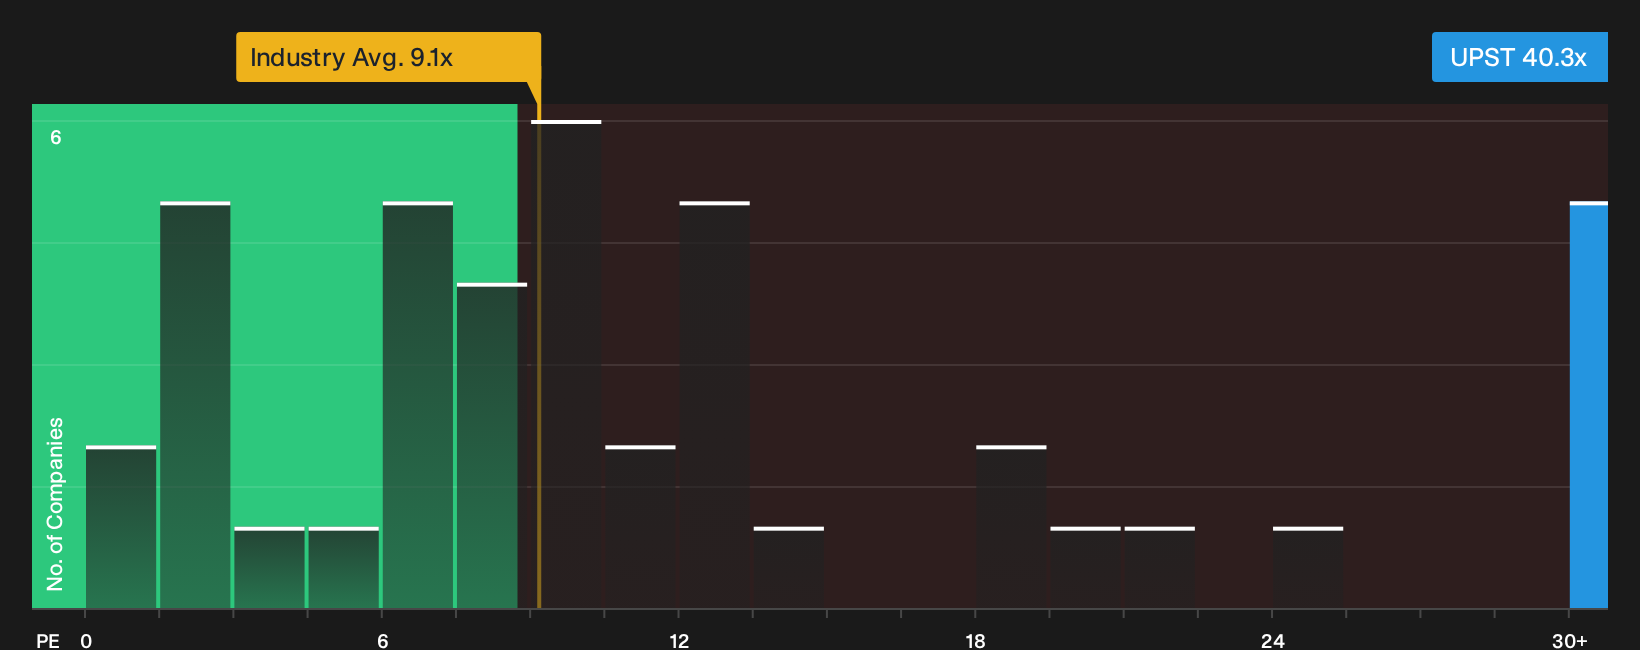
The P/E ratio is a useful measure for Upstart Holdings because investors often focus on how much they are paying for each dollar of earnings in a lending and credit platform business. Upstart trades on a P/E of 40.3x, which is far above the Consumer Finance industry average of 9.1x and the broader peer group near 12.0x. That kind of step up means the market is attaching a much richer earnings tag to this stock than to many other lenders and finance platforms.
The Fair Ratio framework, which adjusts the P/E you might expect for Upstart based on its projected profitability, growth profile, scale and risk, puts the current multiple close to the level that model would suggest. So while the stock carries a premium P/E against sector and peer benchmarks, the tailored fair value yardstick sees today’s pricing as roughly in line with what those fundamentals imply. Explore the numbers behind Upstart Holdings's P/E valuation.
The Upstart Holdings Narrative: What Would Justify Today's Price?
Narratives for Upstart Holdings on Simply Wall St’s Community page act as a bridge from the valuation puzzle by spelling out which expectations on growth, profitability and earnings would need to play out for the stock to be worth markedly more or less than today’s price. Each scenario connects its figures to a specific view on how Upstart Holdings' growth, margins and risk profile might evolve, giving you something concrete to revisit as fresh information comes through.
The community is split on Upstart Holdings, with one camp seeing meaningful upside and another arguing that expectations already stretch too far.
Bull case: 38% undervalued
"Enhanced lending partner confidence, due to strong platform performance and capital market engagements, strengthens funding capabilities and sets the stage for increased origination volume…"
Discover why this Narrative puts Upstart Holdings at 38% undervalued.
Bear case: 19% overvalued
"Increasing data privacy regulations and AI oversight threaten Upstart's model accuracy, differentiation, and may drive up compliance costs and operational risks…"
Explore why this Narrative puts Upstart Holdings at 19% overvalued.
One more angle on Upstart Holdings that could shift how you see the stock
Everything so far has focused on what Upstart Holdings looks like today, but there is a separate lens in the form of professional forecasts that gives you another reference point to compare with the current price. Explore where analysts expect Upstart Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com