
W. P. Carey (WPC) Stock Looks Undervalued On Its 40% Three Year Run
W. P. Carey has delivered solid long term gains for holders, even as more recent trading has been choppy. That puts a spotlight on whether the earnings behind the stock now justify the current price. With real estate investors also watching fresh company updates, the question is how much of the underlying profit story is already reflected in that US$66.26 closing level.
- Over the past 3 years the stock has returned 40.2%, which raises the stakes on whether the current earnings profile can support that kind of share price progress.
- Recent company updates flag over US$1.9b of potential investment activity and near full rent recapture on key re leased Hellweg stores, which can shape expectations for future cash generation and the earnings base that supports valuation.
- The analysts covering W. P. Carey have run their own numbers. See what analysts think W. P. Carey's shares could be worth.
The issue now is whether W. P. Carey's present share price is adequately supported by the earnings that investors are paying for today.
If you are considering W. P. Carey based on its earnings and want a broader earnings-led watchlist, you may wish to explore a focused screen of 33 high quality undervalued stocks.
Is W. P. Carey a Bargain on Earnings?
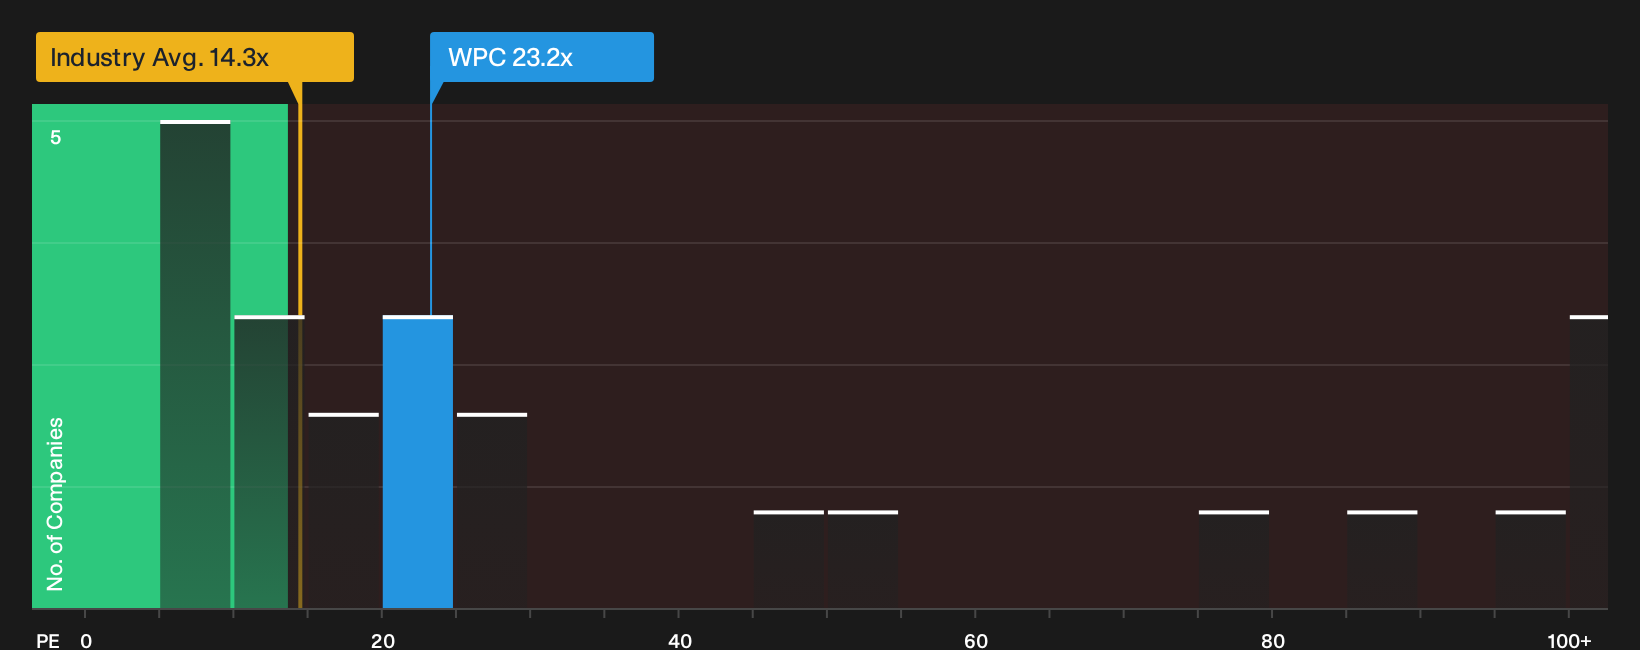
The P/E ratio is a useful lens for W. P. Carey because earnings are a core focus for many REIT investors assessing what they are paying for each dollar of profit. At a P/E of about 23.2x, the stock trades above the broader REIT industry average of roughly 14.3x, yet meaningfully below a peer group that clusters closer to 74.3x. That places the valuation in a middle ground where the market is paying a premium to the sector overall but not pricing W. P. Carey at the same level as the most highly rated peers.
The Fair Ratio model, which looks at factors such as growth profile, margins, size and risk, points to a higher P/E than where W. P. Carey changes hands today. As a result, the current multiple screens as undervalued on this framework. Because management recently highlighted strong visibility on more than US$1.9b of prospective investment activity and solid tenant credit progress for 2026, the fact that the P/E still sits below this tailored benchmark suggests investors are not fully paying up for that pipeline on earnings multiples alone. Explore the numbers behind W. P. Carey's P/E valuation.
The W. P. Carey Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for W. P. Carey leaves off by spelling out which earnings, margin and growth paths would need to play out for the stock to be worth materially more or less than today’s price, and they sit on Simply Wall St’s Community page. Each storyline anchors its number to a concrete view on how W. P. Carey’s growth, profitability and risk profile could evolve, giving you something specific to revisit as fresh information comes through.
One of the top community narratives on W. P. Carey: 17% undervalued
"Active balance sheet management, including high spreads between disposition and investment cap rates, allows accretive reinvestment from non-core asset sales…"
Discover why this Narrative puts W. P. Carey at 17% undervalued.
One more angle on W. P. Carey that could change how you see the stock
Everything so far has focused on what W. P. Carey looks like today, but professional analysts have mapped out where they think this business could be a few years from now, which gives you a different yardstick to compare with the current valuation. Explore where analysts expect W. P. Carey to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com