
What Artisan Partners Asset Management AUM Decline Means For Shareholders
- Artisan Partners Asset Management has faced pressure from sluggish 2.8% annualized revenue growth, a 1.3% annual decline in EPS, and a recent month-on-month drop in assets under management.
- The combination of softer long term fundamentals and fresh AUM weakness points to business headwinds that go beyond short term market noise.
- The focus now turns to how this weaker earnings and assets under management profile could reshape Artisan Partners Asset Management's investment narrative.
Balance that weaker Artisan Partners Asset Management profile by scanning a curated 33 high quality undervalued stocks that combine steadier cash flows with stronger fundamentals.
Artisan Partners Asset Management Investment Narrative Recap
To stay invested in Artisan Partners Asset Management, you need to believe the firm can translate its expanded set of 27 strategies and 11 teams into steady asset inflows despite softer long term trends. The challenge is that recent AUM slippage, a 2.8% revenue growth rate, and a 1.3% annual EPS decline point to pressure on that thesis.
The key near term catalyst is whether investment performance and distribution into the intermediated wealth and private wealth channels can stabilize flows. The biggest current risk is that weaker AUM, combined with higher distribution and operating costs, erodes margins faster than management can adjust its expense base.
The most relevant operational data point here is the reported month on month drop in August assets under management at Artisan Partners Asset Management. That figure goes straight to the engine of the business, since fees are tied to client balances and revenue sensitivity to AUM is high.
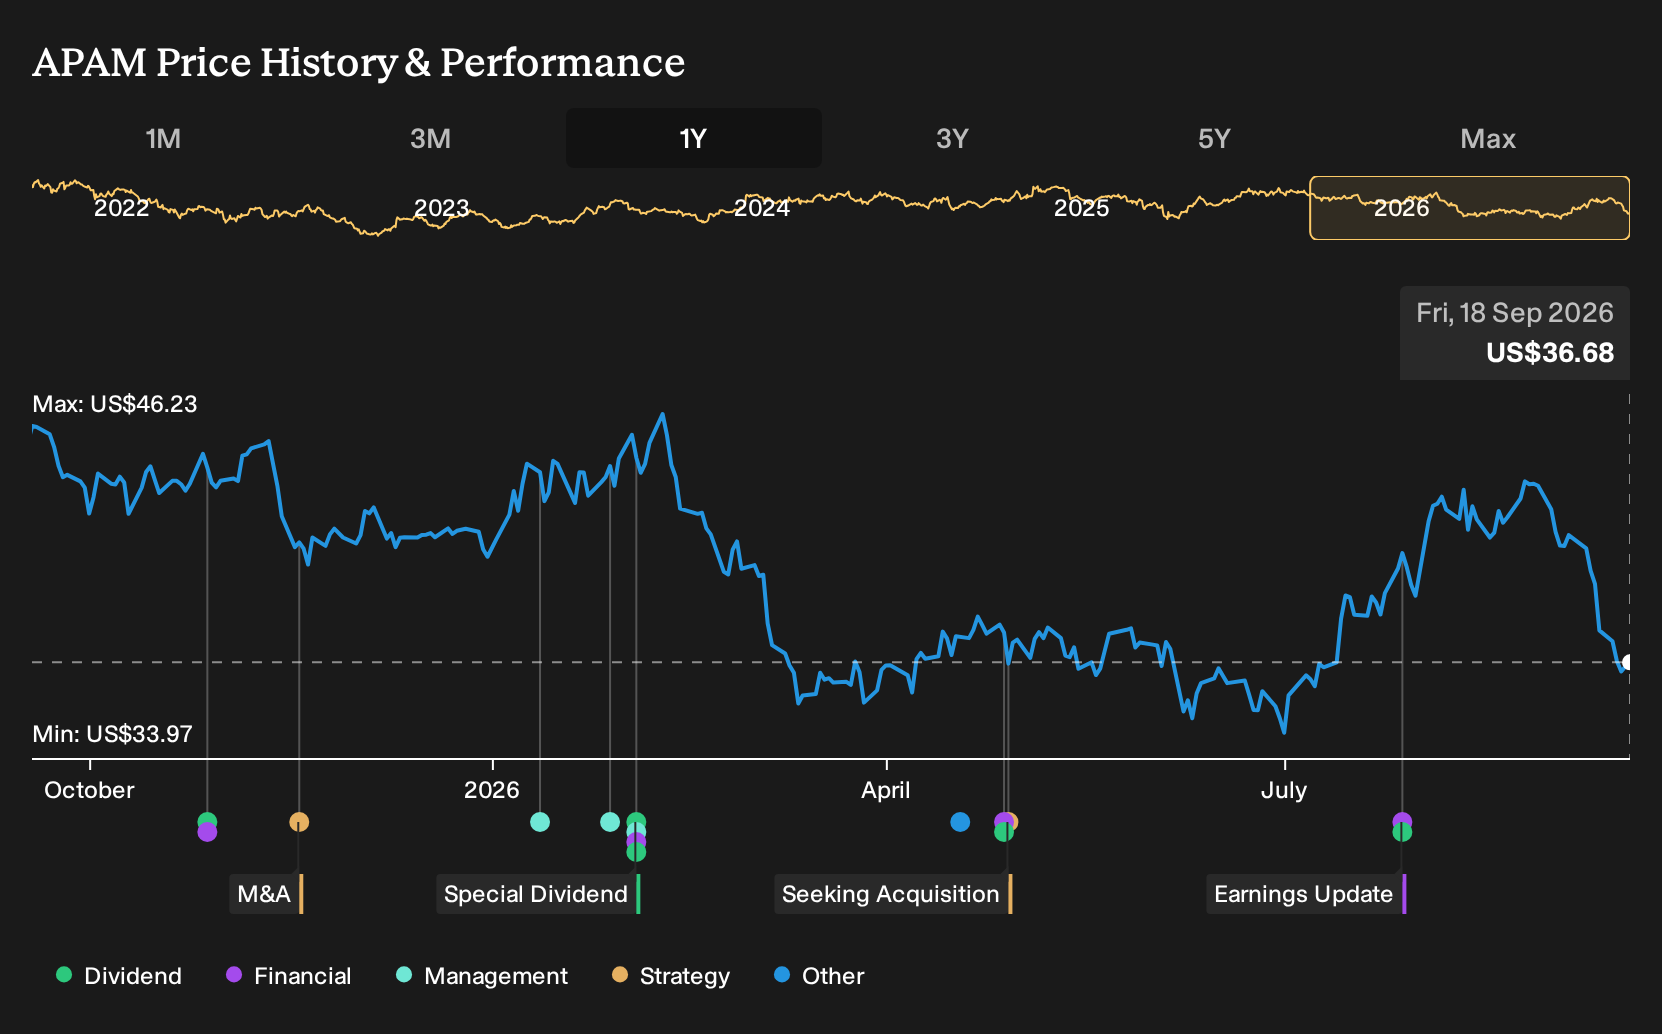
The roughly 12% share price decline over the last month, together with the proximity to the 52 week low, frames how much room investors are giving management to steady flows. Any sign that AUM pressure persists while marketing and platform costs remain elevated would keep the risk around earnings, dividend coverage, and balance sheet flexibility front and center.
Artisan Partners Asset Management's current analyst narrative points to revenue of $1.3b and earnings of $320.3 million by 2029, based on 3.2% yearly revenue growth and an earnings increase of about $58 million from $262.2 million today.
Uncover why Artisan Partners Asset Management's fair value indicates a 4% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view on Artisan Partners Asset Management leans heavily on the risk that equity outflows and client moves toward passive strategies keep pressure on active fees. The most pessimistic analysts were already modeling only 2.6% yearly revenue growth and about US$326.4 million of 2029 earnings. That is a cooler outlook than the baseline and could shift again after this news. Treat it as one of several viewpoints to compare as you form your own expectations.
Explore 2 other Artisan Partners Asset Management fair value estimates, including one that suggests it could be worth just $35.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Artisan Partners Asset Management research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Artisan Partners Asset Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Artisan Partners Asset Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Artisan Partners Asset Management?
If the Artisan Partners Asset Management profile leaves you wanting a broader watchlist, it can help to scan other opportunities that better fit your preferred mix of quality, risk, and income. The Simply Wall St screener lets you filter for exactly that, whether you care most about balance sheet strength, payout potential, or long term resilience.
- For income that aims to feel more durable, start with companies screened as potential 6 dividend fortresses that line up with your yield and payout preferences.
- If balance sheet resilience matters most to you, narrow your focus using a list of solid balance sheet and fundamentals (23 results) that may help you sidestep more fragile businesses.
- When you want lower volatility and steadier profiles, consider building a shortlist from a 30 resilient stocks with low risk scores that emphasizes financial robustness and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com