
Is FuelCell Energy (FCEL) A Bargain As Ratepayer Protection Act Fuels Data Center Hopes?
The latest move in FuelCell Energy (FCEL) has been sparked by legislation, not earnings. The U.S. House passed the Ratepayer Protection Act, which shifts grid upgrade costs for heavy power users such as large data centers.
For context, FuelCell Energy’s recent move comes after a sharp year-to-date share price return of 121.66% and a 1-year total shareholder return of 116.63%. However, momentum has faded in recent months, with a 30-day share price return down 7.32% and a 90-day share price return down 25.75%.
Scan how FuelCell Energy compares with other grid and power plays positioned for heavy data center demand by reviewing the 39 power grid technology and infrastructure stocks.FuelCell Energy now trades below both analyst targets and an intrinsic value estimate, while carrying fresh legal and operational overhangs. Is that discount a margin of safety, or a warning sign the market is respecting?
Most Popular Narrative: 11.7% Undervalued
FuelCell Energy’s most followed valuation storyline pegs fair value at $20.50, above the last close at $18.11. This frames the recent pullback as a debate about execution rather than blue sky hopes.
The partnership with Diversified Energy to deliver up to 360 megawatts to data centers in Virginia, West Virginia, and Kentucky is anticipated to drive significant revenue growth as it positions FuelCell Energy at the forefront of powering AI and high-performance computing sectors. The joint development agreement with Malaysia Marine and Heavy Engineering to co-develop large-scale hydrogen production systems is expected to enhance revenue by expanding FuelCell Energy's market presence in Asia, New Zealand, and Australia, tapping into growing demand for hydrogen.
See why 51 investors see FuelCell Energy as 12% undervalued.
Result: Fair Value of $20.50 (UNDERVALUED)
Still, FuelCell Energy’s continued net loss of US$178.3 million and fresh securities investigations around Fit Energy related charges could test how durable that 11.7% undervaluation narrative really is.
Find out about the key risks to this FuelCell Energy narrative.
Another View: FuelCell Energy Looks Expensive On Sales
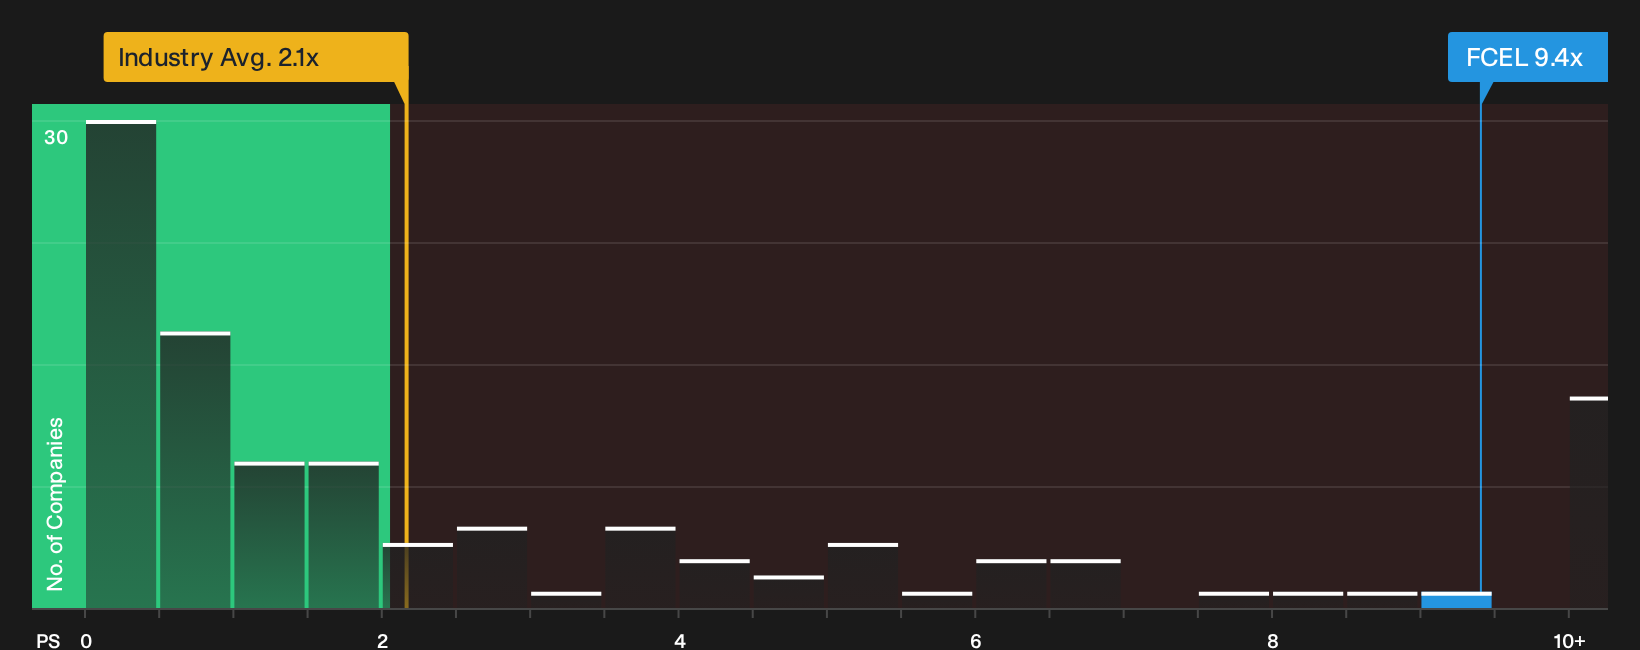
The fair value story around FuelCell Energy leans on future earnings and long term margin repair. A simple P/S check tells a different story. The stock trades on 9.4x sales, compared with 2.1x for the US Electrical industry and a fair ratio of 1.6x. That is a wide gap. Is this really undervaluation, or has the market just moved the risk to what happens if growth disappoints?
For a closer look at how this sales based view stacks up against other checks on FuelCell Energy, run through the valuation breakdown next and then decide which framework you trust most for your own process, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on FuelCell Energy appears mixed. If you want to move quickly and make your own decision, consider weighing both sides through the 1 key reward and 3 important warning signs
Looking for more FuelCell Energy sized opportunities?
If you stop with FuelCell Energy, you risk missing other setups where price, quality, and risk come together more cleanly than this single stock ever could.
- Target potential upside in higher risk corners of the market by reviewing the 9 elite penny stocks with strong financials that already screen well on key fundamentals.
- Zero in on value led ideas by scanning the 33 high quality undervalued stocks that pair quality financials with prices below their estimated worth.
- Prioritise resilience and sleep at night holdings by focusing on the 30 resilient stocks with low risk scores that clear strict balance sheet and volatility filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com