
Should Long Term Charter Deal Require Action From DHT Holdings (DHT) Investors?
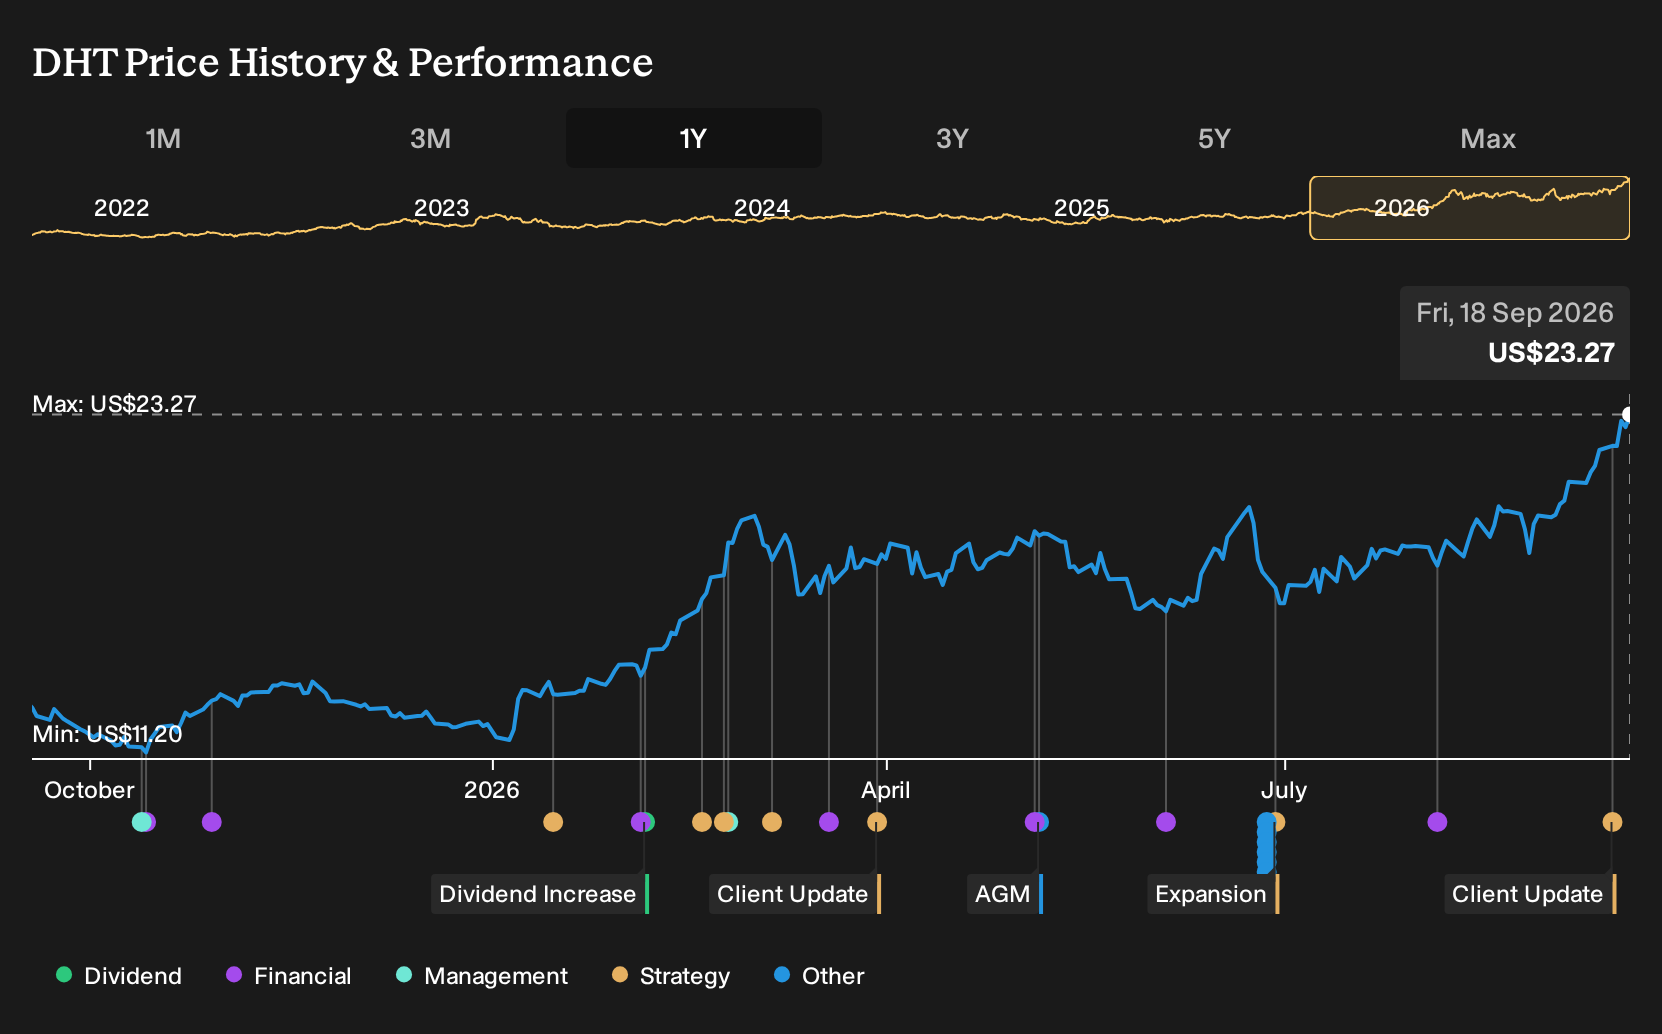
- DHT Holdings announced a three year time charter for the 2016 built VLCC DHT Panther at a rate of $100,000 per day with a global energy company, with the contract starting in October 2026.
- The fixed multi year charter on a modern VLCC locks in contracted revenue for DHT Holdings and provides greater visibility on fleet utilization compared with relying purely on spot exposure.
- We will look at how DHT Holdings' investment narrative around cash flow stability is affected by the $100,000 daily charter commitment.
DHT Holdings Investment Narrative Recap
To own DHT Holdings you need to be comfortable with a crude tanker business that still leans on volatile spot earnings, while using select period charters to smooth cash flows. The DHT Panther deal adds more contracted revenue visibility, although it only covers one VLCC out of a 22 vessel fleet, so it does not change the overall exposure to tanker cycles.
The main near term swing factor remains freight rate strength against analyst expectations for earnings to decline over the next three years. The key risk stays the same: heavy dividend payouts and sector wide regulatory and environmental costs can tighten financial flexibility if vessel earnings weaken.
The DHT Panther charter lines up with the existing focus on modern VLCCs and time charter interest highlighted in the prior catalyst narrative. A three year commitment at a fixed US$100,000 per day fits the idea that DHT Holdings may use higher quality fixtures on newer ships to underpin cash generation while keeping the rest of the fleet more rate sensitive.
That earlier context around limited new VLCC supply and customer appetite for newer, fuel efficient tonnage gives this contract more weight as a proof point. For you as a shareholder, the link between this kind of multi year coverage and the company’s willingness to distribute 100% of ordinary net income is important, because steadier vessel earnings can help support that payout policy through a weaker part of the cycle.
DHT Holdings' narrative projects US$424.7 million in revenue and US$263.8 million in earnings by 2029. This projection assumes revenue declines at 19.0% per year and that earnings fall by US$209.9 million from US$473.7 million today.
Uncover how DHT Holdings' fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For a contrasting angle on DHT Holdings, the bullish analysts focus on the potential for sustained longer trade routes rather than demand risk from renewables. They were already penciling in about US$458.0 million of revenue and US$258.5 million of earnings for 2029. Those more optimistic forecasts pre date this charter, so their narrative could shift again.
Explore 5 other DHT Holdings fair value estimates, including one that suggests potential upside of up to 55% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DHT Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DHT Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHT Holdings' overall financial health at a glance.
Looking For More Ideas Beyond DHT Holdings?
If you want to build on the DHT Holdings thesis but keep your portfolio options open, it helps to scan for other stocks with balance sheets and earnings profiles that match the kind of risk you are willing to take.
- For investors who want a shot at high upside in smaller companies while still applying a financial quality filter, consider using the 9 elite penny stocks with strong financials.
- If your priority is finding opportunities where quality and pricing both look reasonable, you can start with the 33 high quality undervalued stocks.
- For readers who care most about resilience and limiting downside surprises, a helpful next step is to run the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com