
Linde (LIN), What Is Drawing Fresh Attention Now?
Linde (LIN) grabbed investor attention after its latest share price move, with the industrial gas specialist now trading around $460.40 per share on the Nasdaq. Short term performance has been mixed.
Recent trading has been choppy for Linde, with the 30 day share price return down 5.57% and the 90 day share price return lower by 10.90%, even though the year to date share price return is still up 7.29%. That pullback contrasts with a 1 year total shareholder return that is slightly negative at 2.58% but stretches to 28.28% over 3 years and 58.78% over 5 years. This suggests short term momentum is fading while longer term holders have still seen meaningful gains.
Compare Linde's recent pullback with other industrial leaders by scanning a hand picked set of resilient materials and infrastructure stocks in the 30 resilient stocks with low risk scores.
Linde now trades near $460, yet analyst targets and intrinsic estimates point in very different directions. Where does a reasonable view of fair value actually land after this recent pullback?
Most Popular Narrative: 16% Undervalued
Linde's most followed narrative points to a fair value of about $545 per share, comfortably above the recent $460 close. This puts the recent pullback in a different light for anyone focused on long term cash generation.
Strategic investments and customer commitments in rapidly expanding growth markets such as commercial space launches, electronics, and clean hydrogen (with almost $5 billion in new clean energy contracts) provide a runway for high-margin revenue streams and new project conversion that will structurally lift blended margins and earnings.
See why 113 investors see Linde as 16% undervalued.
Result: Fair Value of $545 (UNDERVALUED)
Still, the bullish Linde story can crack if weak industrial demand in Europe drags on gas volumes, or if oversupply pressures squeeze pricing in key product lines.
Find out about the key risks to this Linde narrative.
Another View On Linde’s Valuation
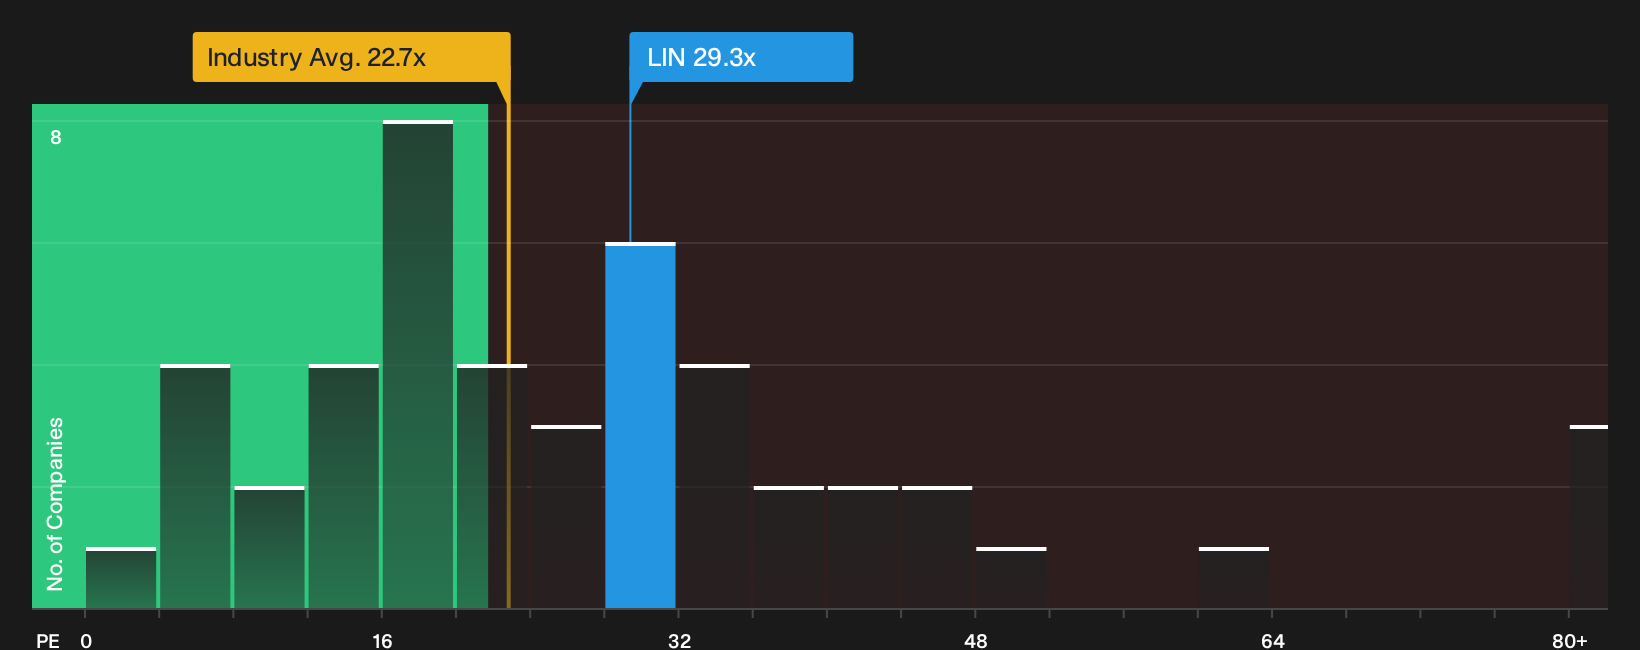
The rally case around fair value near $545 meets a very different message from the market’s own P/E math. Linde trades on about 29.3x earnings, while the US Chemicals industry sits nearer 22.7x and the fair ratio for Linde is estimated at 24.2x. That gap suggests investors today are paying a clear premium. Is that extra multiple really the cushion you want, or the risk you are taking?
For a closer look at how this pricing stacks up against peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Linde can leave you torn between the upside story and the risks on the table. Move quickly, review the key facts for yourself, then weigh the 2 key rewards and 2 important warning signs
Looking for more Linde sized investment ideas?
If Linde has you thinking harder about valuation and risk, do not stop here. Broaden your watchlist with a few focused stock shortlists built from hard data.
- Target quality at a discount by scanning the 33 high quality undervalued stocks and compare how other companies line up on both fundamentals and pricing power.
- Prioritise resilience in tougher markets by working through the 30 resilient stocks with low risk scores so you are not relying on one industrial heavyweight alone.
- Hunt for future leaders early by checking the 16 high quality undiscovered gems before the crowd starts paying attention to the same opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com