
On Holding (ONON) Stock Looks Reasonable After A 42% Fall
On Holding has seen a sharp reset in its share price this year, and the size of that pullback puts a fresh spotlight on whether the current valuation can still be explained by its earnings power. With the stock now trading around US$27.26, the key issue is how that price lines up against what the business is actually generating in profit.
- The share price is down about 41.9% year to date, which puts pressure on the idea that the current market value reflects what the underlying earnings can justify.
- The company’s model relies heavily on turning brand momentum into sustained profitability, so the durability of margins and the conversion of sales into cash can shape what investors are willing to pay for each dollar of earnings.
- The analysts covering On Holding have run their own numbers. See what analysts think On Holding's shares could be worth.
The issue now is whether On Holding’s current share price can be explained by its earnings when set against the Fair Ratio benchmark.
If you want a broader watchlist while you assess whether On Holding’s earnings justify today’s price, a focused stock screen built around 33 high quality undervalued stocks is a useful next step.
Does On Holding Look Undervalued on Earnings?
The P/E ratio is a useful fit for On Holding because it links what you pay for the stock directly to the profit the business is already reporting.
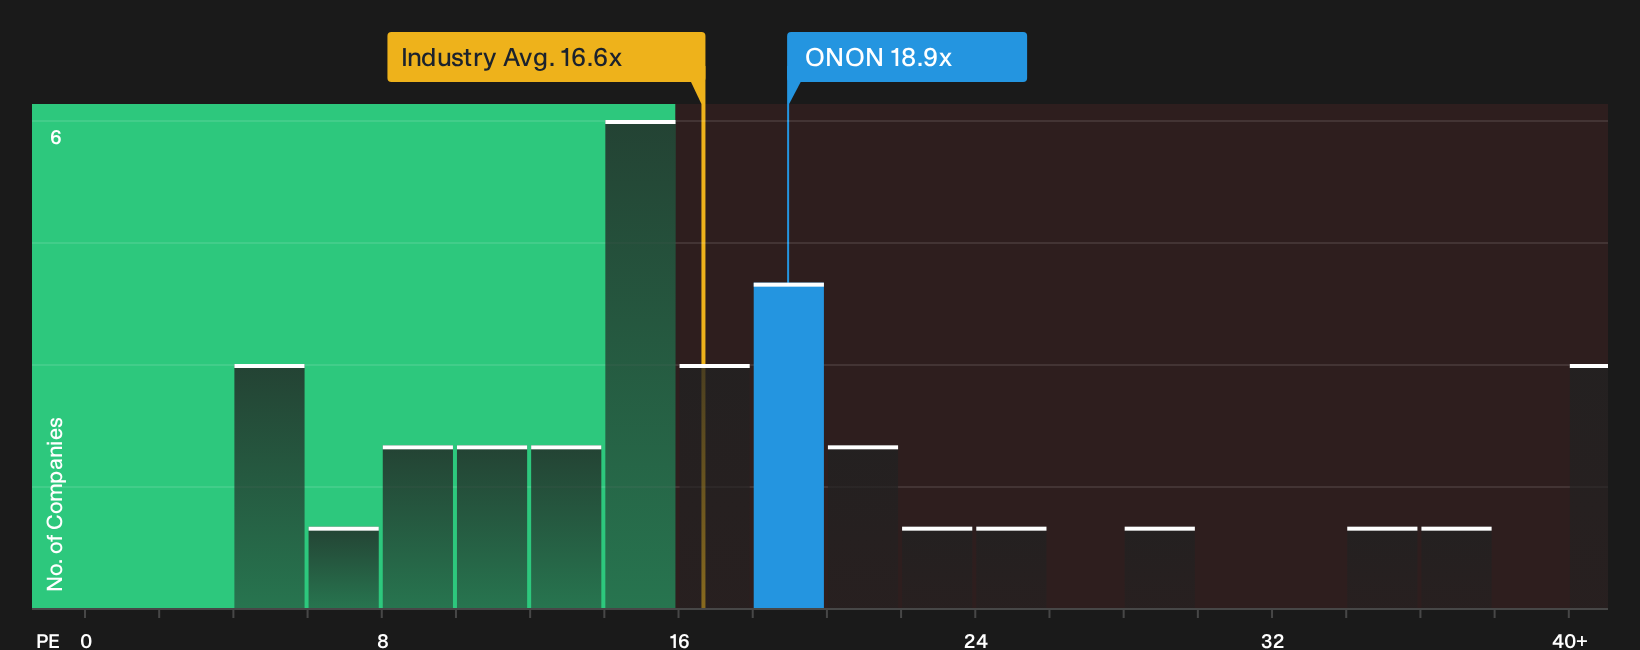
On Holding currently trades on a P/E of about 18.9x, which is above the broader luxury group average of roughly 16.6x and also richer than peers at around 14.0x. The Fair Ratio, which reflects what would typically be expected given this company’s mix of growth profile, margins and risk, sits higher than where the shares change hands today, so the current multiple screens as undervalued on this framework.
For you as an investor, that means the market is pricing On Holding at a lower earnings multiple than this tailored benchmark implies, even though the stock still carries a premium to the wider sector and peer set. How comfortable you feel with that gap comes down to how durable you think the brand and profitability story is over time, and whether the risk profile justifies paying up for each dollar of earnings. Explore the numbers behind On Holding's P/E valuation.
The On Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for On Holding pick up where the valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today. Each scenario links a fair value estimate to a clear storyline about On Holding's potential catalysts and key risks, allowing you to track over time which version of events appears to be gaining traction on the Community page.
On Holding splits opinion, with bullish holders seeing premium margins and brand strength as underappreciated, while skeptics focus on execution risk and softer wholesale trends.
Bull case: 58% undervalued
"Scaling of direct to consumer channels, through highly productive flagship stores and a tightly integrated e commerce ecosystem, is boosting customer loyalty…"
Discover why this Narrative puts On Holding at 58% undervalued.
Bear case: 9% overvalued
"Dependence on premium positioning and full price discipline exposes the model to a potential normalization in consumer appetite for high priced performance and lifestyle sportswear…"
Explore why this Narrative puts On Holding at 9% overvalued.
One last On Holding check that belongs beside the P/E
Price multiples tell you what the market pays for today, while professional projections sketch out where the earnings story could be a few years from now. This gives you a different reference point for the same US$27.26 share price. Explore where analysts expect On Holding to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com