
3 Canadian Penny Stocks With P E Under 18
Canadian policymakers are pushing hard to attract fresh capital, with Mark Carney championing tax breaks and investment incentives to pull more money into the country. That focus on disciplined capital allocation makes financially solid penny shares in Canada especially interesting right now. This article highlights three lower priced, financially healthier micro caps from our screener that could appeal to investors seeking growth potential while still paying close attention to balance sheet strength.
The three penny stocks covered below are just a small sample. The full Financially Fit Penny Stocks screen surfaced 346 more companies with similarly detailed stories that are not broken out in this article.
Head straight into the Financially Fit Penny Stocks screener to identify, analyze, and focus on the higher conviction ideas that best fit your risk tolerance and time horizon.
Cronos Group (TSX:CRON)
Overview: Cronos Group is a cannabinoid producer selling branded cannabis products like Spinach and Lord Jones to consumers in Canada and abroad.
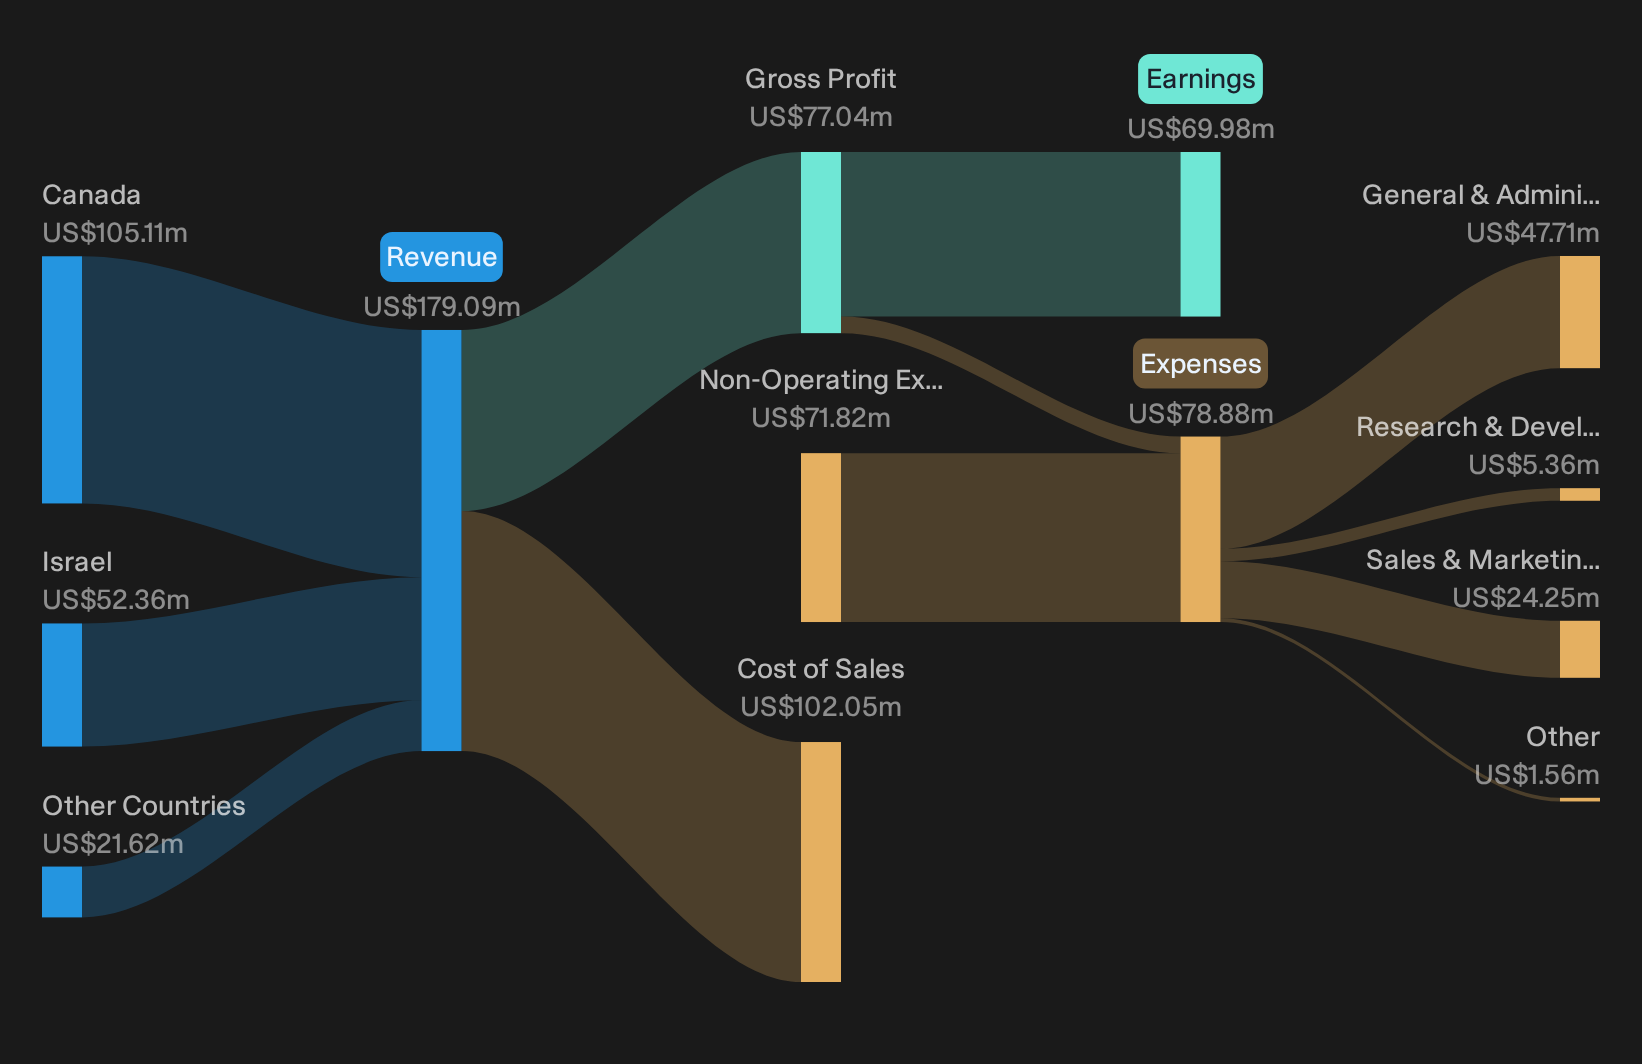
Operations: The business earns about $179 million from cannabis and cannabis-derived products, mostly in Canada at $105 million, then Israel and other markets.
Market Cap: CA$1.7b
Cronos Group fits this Financially Fit Penny Stocks theme because it couples smaller-cap pricing with everyday cannabis brands that reach real consumers at the shelf.
"The strength and breadth of premium brands (Spinach, Lord Jones, PEACE NATURALS) across flower, vapes, edibles, and concentrates, coupled with industry-leading market shares in high-margin categories, point to sustainable pricing power and enduring consumer loyalty, supporting continued gross margin improvement and resilient long-term earnings.
What happens to those attractive margins if a single unseen cost pressure or regulatory shift starts to bite into pricing power?
That kind of pressure point is exactly what the full narrative for Cronos Group unpacks, showing where Cronos Group could accelerate, stall, or quietly reshape its earnings mix.
CEMATRIX (TSX:CEMX)
Overview: CEMATRIX manufactures and pours cellular concrete on construction sites across North America, supplying lightweight backfill and insulation for major infrastructure work.
Operations: CEMATRIX generates about CA$53.8 million from supplying and placing cellular concrete, with roughly CA$42 million from the United States and CA$11.8 million from Canada.
Market Cap: CA$71 million
CEMATRIX fits the Financially Fit Penny Stocks theme as a low-priced construction materials specialist whose cellular concrete is already embedded in real-world road, bridge, and utility projects, giving you direct exposure to infrastructure activity rather than speculative concepts.
"Rising demand for sustainable, low-carbon construction materials, driven by both regulatory pressure and ESG-conscious customers, is a potential tailwind for CEMATRIX's environmentally focused product line and its addressable market."
The key question for CEMATRIX is how much of any expanding project pipeline can translate into durable profitability if one critical input cost shifts.
If that input shock matters to you, the full narrative for CEMATRIX explains how CEMATRIX's pricing power, contract structure, and capital discipline could amplify or absorb it.

McChip Resources (TSXV:MCS)
Overview: McChip Resources is a Toronto based natural resources investor holding petroleum interests and a Saskatchewan potash project alongside other mineral stakes.
Operations: McChip Resources generates about CA$3.6 million from oil and gas exploration and production activities in Canada.
Market Cap: CA$4.2 million
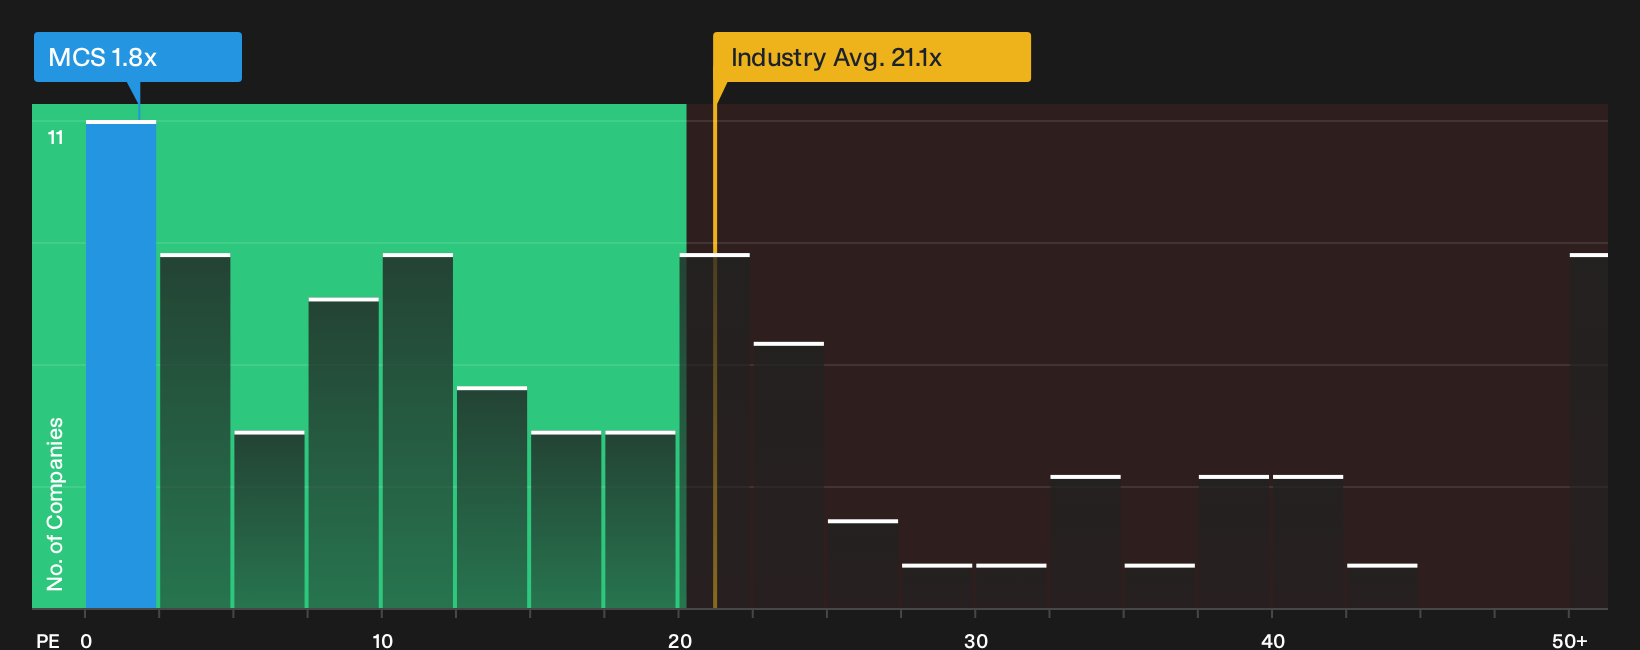
McChip Resources offers a tiny market value, asset backed petroleum and potash profile, and a very low 1.8x P/E that fits the Financially Fit Penny Stocks idea of smaller companies with identifiable projects underpinned by real assets. The appeal depends on how one unresolved pressure on those earnings interacts with a volatile share price and shifting governance.
Those cross currents make it worth pulling up the 2 key rewards and 3 important warning signs to see whether McChip Resources’ low P/E reflects overlooked assets or brewing pressure.
Seeking Alternatives Before Others Catch On
Fresh ideas move first. Slower capital often gets caught chasing breakouts after momentum is already flying. Scan these focused lists while the data still matters and get in early.
- Spot income workhorses with yields that could steady a portfolio by running the 1 dividend fortresses before those payouts get crowded by late arrivals.
- Hunt for resilient operators with cleaner finances using the curated list of solid balance sheet and fundamentals (7 results) before strong balance sheets get fully priced in.
- Track real-world picks-and-shovels beneficiaries of AI demand by reviewing the hand-picked 88 AI infrastructure stocks while the theme is still relatively under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com