
Enterprise Products Partners (EPD) Stock Trades At A Discount On Its 158% Five Year Run
Enterprise Products Partners has delivered strong multi year returns, which puts a spotlight on whether the current US$38.89 unit price lines up with the earnings behind it. With the recent move in the units, investors are asking how much of the partnership's profit power is already reflected in today’s valuation.
- Over the past 5 years, Enterprise Products Partners has returned 158.4%, which raises the question of whether its earnings can support the current unit price.
- The partnership relies heavily on fee based energy infrastructure. As a result, the stability and quality of those earnings streams may support a different valuation profile from more commodity exposed businesses.
- The analysts covering Enterprise Products Partners have run their own numbers. See what analysts think Enterprise Products Partners's shares could be worth.
The stock's next move may depend on whether Enterprise Products Partners' current earnings justify paying around US$38.89 per unit today.
If you want to evaluate whether Enterprise Products Partners' earnings support its recent 5-year performance, you can use a focused screener of other income-focused infrastructure plays, such as 6 dividend fortresses.
Is Enterprise Products Partners Still Cheap on Earnings?
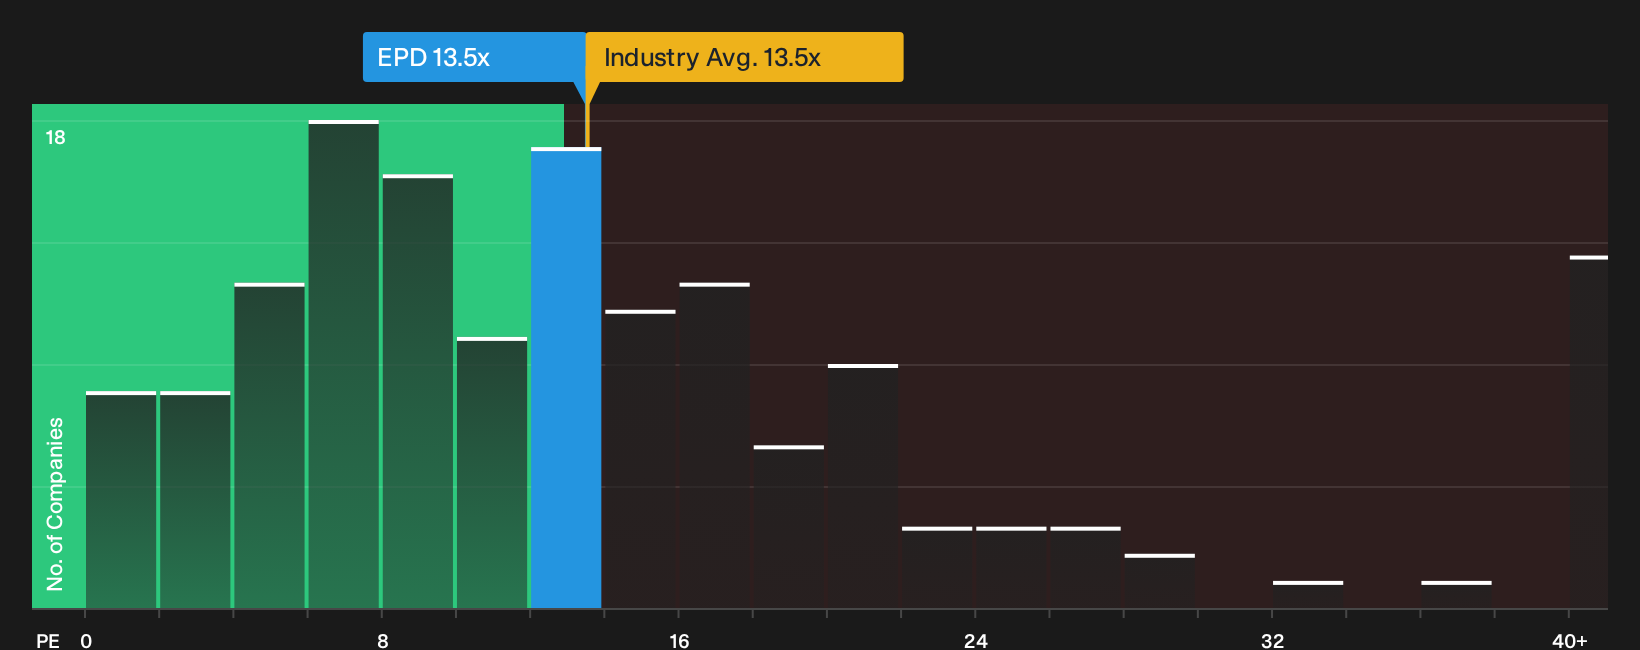
The P/E ratio suits Enterprise Products Partners because earnings are the main anchor investors watch for a fee based infrastructure business. On this lens, the partnership trades on a P/E of about 13.5x, which is very close to the Oil and Gas industry average of roughly 13.5x. That keeps the current unit price broadly in line with how the wider sector is being valued on reported profits.
The fair value framework, which adjusts for factors such as growth profile, margins, size and risk, points to a higher P/E than where Enterprise Products Partners currently trades. That puts today’s 13.5x multiple below the level this model would usually expect for this type of earnings stream, so the units screen as undervalued on this measure. For investors, the key question is whether the partnership can sustain the earnings quality that this framework appears to be giving it credit for. Explore the numbers behind Enterprise Products Partners's P/E valuation.
The Enterprise Products Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Enterprise Products Partners sit between the current P/E puzzle and your own view of what the partnership could be worth over time. They spell out which paths for earnings, margins and growth would need to play out for the units to be priced materially higher or lower than today. Each thread ties its number to a clear stance on how Enterprise Products Partners' growth potential, profitability and key risks might evolve, which you can revisit as fresh information appears on the Community page.
One of the top community narratives on Enterprise Products Partners: 6% undervalued
"The completion of two gas processing plants in the Permian, along with several key pipeline and export terminal projects, is expected to enhance Enterprise Products Partners’ infrastructure…"
Discover why this Narrative puts Enterprise Products Partners at 6% undervalued.
One more Enterprise Products Partners check that belongs beside the P/E
Price and earnings only tell you so much, because the real steering wheel sits with the people running Enterprise Products Partners and how their interests line up with yours as a unitholder. See who runs Enterprise Products Partners and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com