
Robertet (ENXTPA:RBT) Stock Faces Profit Squeeze As Margins Tighten
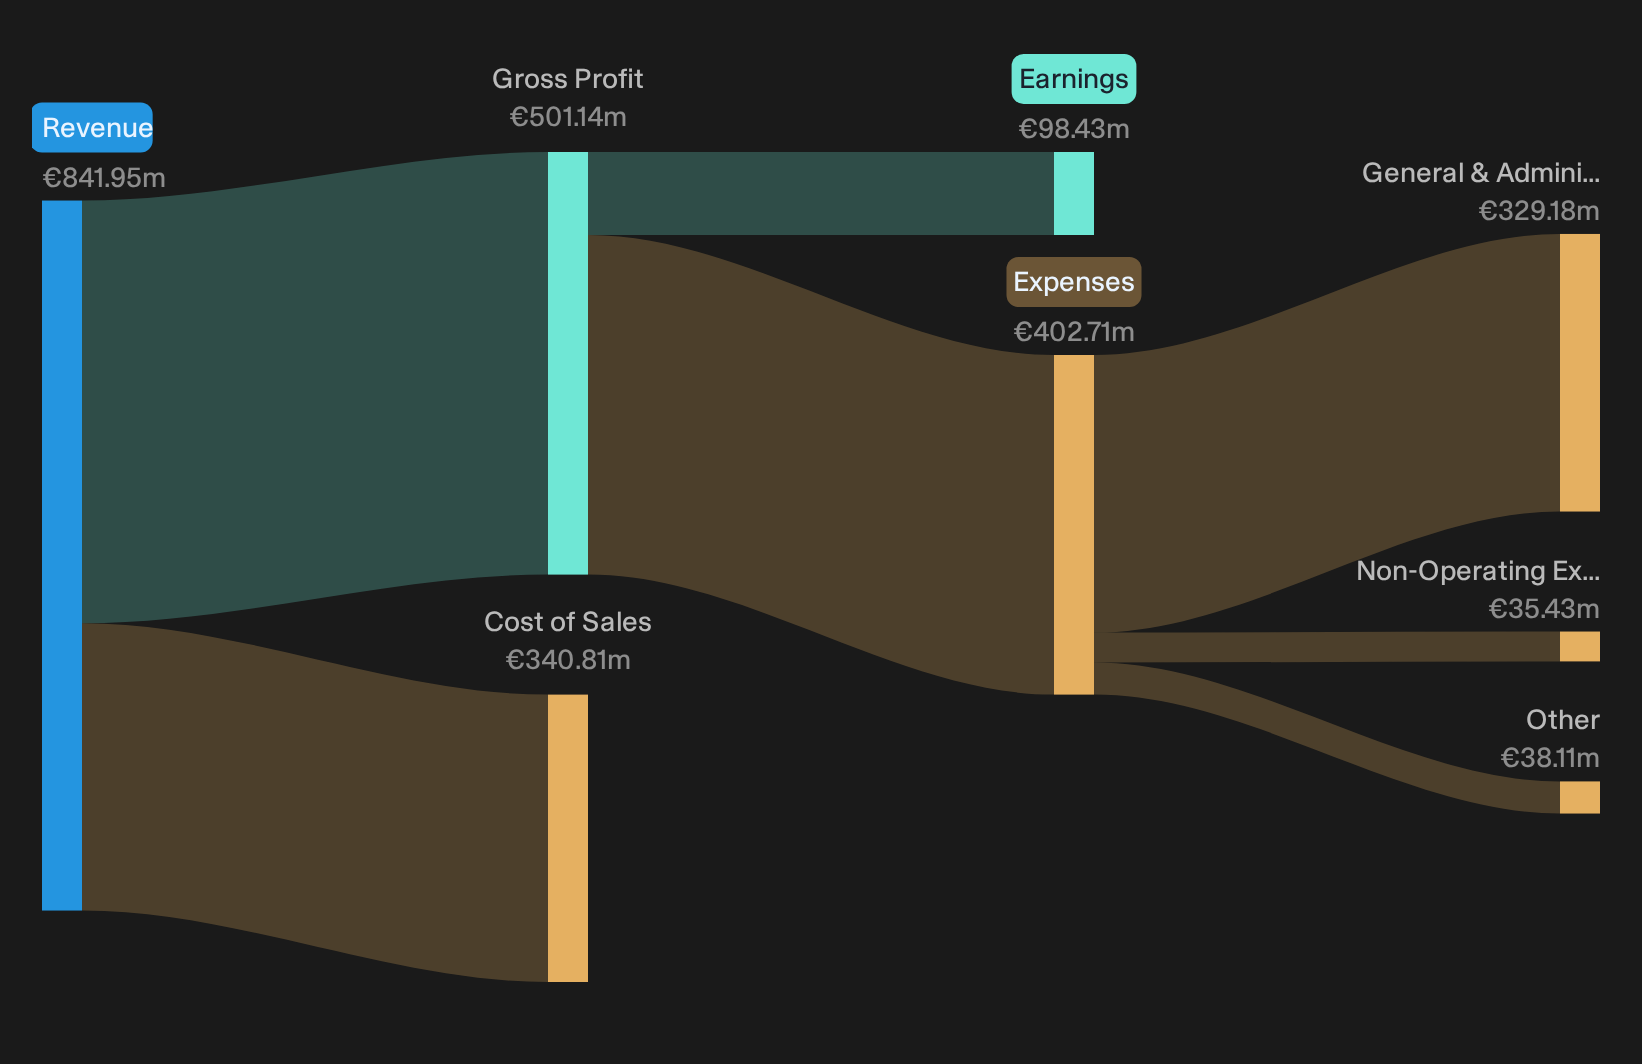
Robertet came into this release with a bruised share price, down roughly 5% over the past week and about 9% over three months, yet still carrying a reputation as a quality fragrance and ingredients compounder at a restrained P/E of 16.4x. The headline from H1 2026 is a profit squeeze. Net income landed at €54 million on €444 million of sales, softer than the €58.5 million earned on a slightly higher top line in H1 2025. For a stock often framed as a steady compounder, that pressure on earnings is what traders are reacting to first.
Is Robertet now simply cheap for a reason, or is the market overreacting to a temporary earnings squeeze at a 16.4x P/E and softer H1 profits? See how that trade off looks inside the valuation analysis for Robertet
H1 2026 Earnings Summary
- Revenue (H1 2026 vs. H1 2025): €444 million vs. €446.337 million (slight decline in sales)
- Net Income, excl. extra items (H1 2026 vs. H1 2025): €54 million vs. €58.501 million (profit compressed year on year)
- Basic EPS (H1 2026 vs. H1 2025): Not disclosed for H1 2026 vs. €28.551 in H1 2025 (earnings per share detail not provided for the latest half)
- Net Margin, trailing 12 months vs. prior year: 11.7% vs. 11.5% (slight uplift in profitability ratio despite softer recent half)
If you prefer clean charts to dense rows of figures and footnotes on Robertet, view the full visual picture of its valuation in an easy dashboard format through the company report for Robertet.
Robertet bull case leans on mix and resilience
Bulls argue Robertet can keep compounding through a mix shift toward Fragrances and Health & Beauty, underpinned by natural ingredients and expanding capacity. H1 2026 organic revenue grew 2.8%, and recurring EBITDA reached €94 million with a 21.1% margin. That points to some resilience despite softer reported sales. Fragrances and Health & Beauty are described as showing strong and solid momentum, which lines up with management highlighting demand tied to Indonesia and São Paulo rather than just restocking. CapEx weighted to late 2025 is framed as feeding 2026 capacity, and guidance for 2026 organic growth of 3–5% is maintained. So the milestone of holding investment and margin while keeping guidance is intact. The missing piece is a broad based contribution. Raw Materials and Flavors are not yet pulling their weight, so the bullish story currently relies on only part of the portfolio.
Robertet bear case focuses on margins and breadth
Skeptics worry that margin pressure, weaker divisions and FX drag show a less durable growth engine at Robertet. H1 2026 net income slipped to €54 million from €58.5 million on a slightly softer top line, even as the trailing 12 month net margin sits at 11.7% versus 11.5%. That suggests recent profit pressure is real, even if long run ratios are not collapsing. Management flags strong cost headwinds in synthetics and packaging and has already softened precision on margin targets and timing. Raw Materials and Flavors have decelerated or turned negative, while explanations lean on base effects and prior one off orders. FX is described as a significant drag on reported growth. With the share price down about 5% over 7 days and roughly 9% over 3 months into September 18, 2026, the view that earnings quality is under scrutiny looks partially validated by this print.
With margins under pressure and capex still in focus, the real question is whether Robertet has the balance sheet strength and cash generation to ride out a slower earnings patch. Check the full solvency and liquidity picture in the financial health analysis of Robertet stock.Take Control Of Your Next Move
With Robertet facing a profit squeeze and its P/E at 16.4x, register for free with Simply Wall St and add it to a Watchlist so you can track the share price against fair value and wait for an entry point that suits your plan. Once you own it, use the Portfolio Command Center to cut through day to day noise and focus on the key developments that matter for your holdings. For longer term context, tap into the Community to see how other investors are reading the same numbers and risks. That way you can spot potential catalysts or warning signs early and aim to stay a step ahead of the wider market.
Seeking Alternatives Beyond Robertet?
Fresh ideas move fast. Some potential breakouts are already building momentum while others stay under the radar for now. Scan these curated shortlists before the best entry windows are gone and act now.
- Spot resilient cash generators before they start flying by reviewing a curated list of solid balance sheet and fundamentals stocks (198 results) and find candidates that may hold up when sentiment cools.
- Chase income opportunities that could keep paying even when prices wobble by scanning a hand picked set of 156 dividend fortresses built around consistent distribution strength.
- Track future facing themes that might not be fully priced in yet by filtering a focused group of 88 AI infrastructure stocks while the story is still forming.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com