
CITIC (SEHK:267) Stock Still Looks Like A Bargain Following Its 115% Run
CITIC has delivered a strong share price run in recent years, which naturally raises the question of whether the current valuation is still grounded in its earnings power. With the stock last closing at HK$13.04, investors are asking how much of the business's profit profile is already reflected in that price.
- CITIC's share price has gained 114.8% over the past 3 years, putting a lot of focus on whether that move lines up with the earnings the business is generating.
- The group relies heavily on how efficiently it converts operating performance into sustainable profits and cash, which can influence how much investors are willing to pay for each dollar of earnings.
- Your read on CITIC is one view; the desks covering it have another. See what analysts think CITIC's shares could be worth.
The issue now is whether CITIC's current share price is justified by the earnings that support it.
To assess whether CITIC's recent share price rise appears stretched or reasonable, it can help to compare it with other companies that meet a similar quality and value filter using the 179 high quality undervalued stocks
Does CITIC Look Undervalued on Earnings?
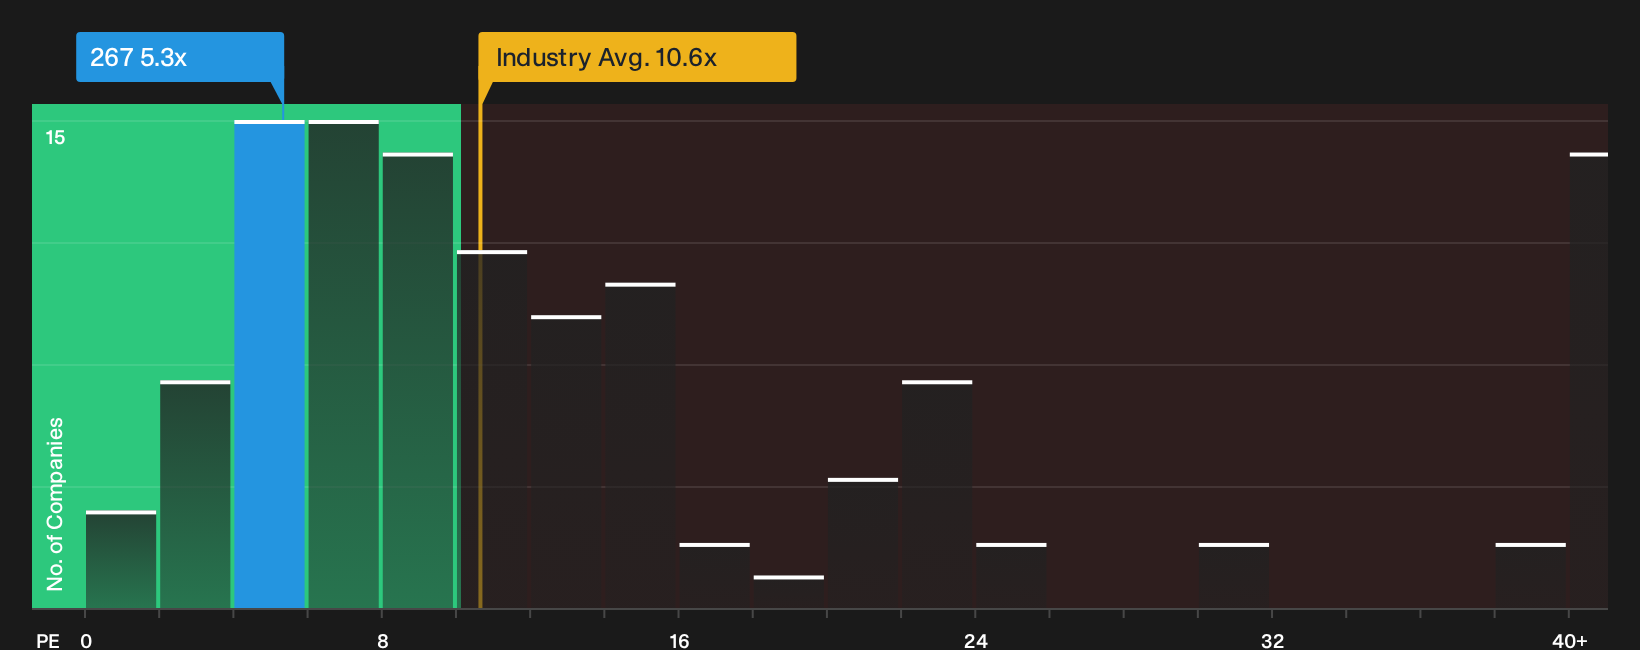
The P/E ratio suits CITIC because earnings are a key anchor for how investors value a diversified industrial group. At the current price, CITIC trades on a P/E of 5.3x, which is below the Industrials sector average of about 11.3x and also under the peer group mark of roughly 10.7x. For a reader, that means the market is paying fewer Hong Kong dollars for each unit of CITIC's reported profit than it does for many comparable businesses.
The fair multiple implied by the valuation model, which factors in CITIC's size, margins, risk profile and sector context, sits above where the shares change hands today. That gap suggests the stock is pricing in more caution than the model applies to its earnings stream, so the current P/E leans toward an undervalued reading on this framework. To judge how comfortable you are with that, you would still need to weigh the durability of those profits, the mix of CITIC's operations and any company specific risks that are not captured in a simple multiple. Explore the numbers behind CITIC's P/E valuation.
The CITIC Narrative: What Would Justify Today's Price?
Narratives on CITIC pick up where the P/E puzzle leaves off. They explain which paths for CITIC's growth, profitability and earnings would need to play out for the current HK$13.04 share price to look materially higher or lower in hindsight. Each one links its conclusion to a specific view on how the group's growth, margins and risks might shift over time so you can revisit that logic as fresh information comes through.
One of the top community narratives on CITIC: 6% undervalued
"CITIC Limited plans to increase its dividend payout ratio to at least 30% by 2026, which may attract more investors seeking income..."
Discover why this Narrative puts CITIC at 6% undervalued.
One more CITIC checkpoint that sits beside the share price
Before you treat CITIC's valuation as the full story, it is worth asking who is steering the group, how their rewards are structured and whether those incentives truly line up with your interests. See who runs CITIC and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com