
Celestica (TSX:CLS), What Is Behind The Fresh Attention?
Celestica (TSX:CLS) is reshaping its leadership structure after announcing that long-time finance chief Mandeep Chawla will become Group President, Global Markets, while Todd Ankenmann steps into the Chief Financial Officer role.
At around CA$465.13 per share, Celestica has delivered a 14.09% 1 month share price return and a 12.16% share price gain year to date. The 1 year total shareholder return of 32.96% and very large 3 and 5 year total shareholder returns point to momentum that many investors will see as still firmly intact, despite a recent 7 day pullback and a 90 day decline of 12.80% as the market reassesses growth potential and execution risk around moves such as this leadership reshuffle.
Scan for other electronics manufacturing and AI infrastructure plays showing similar leadership and growth positioning by reviewing the hand picked 88 AI infrastructure stocks alongside Celestica.
Celestica is now trading on a mix of strong reported growth and fresh questions after this finance reshuffle. Are investors paying for a sturdier underlying engine, or for shifting sentiment around a headline friendly AI and infrastructure story?
Most Popular Narrative: 31% Undervalued
Against the current CA$465.13 share price, the most followed narrative pegs Celestica's fair value at about CA$677.38, which implies a sizeable valuation gap built on aggressive AI infrastructure assumptions and rich earnings projections.
Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is driving rapid growth in Celestica's CCS segment, with multiple new 800G and upcoming 1.6T program ramps, supporting robust revenue expansion and greater operating leverage over the next 12 to 24 months.
Widespread digital transformation initiatives and technology transitions (AI/ML compute, next-generation racks) across hyperscalers and digital native customers are expanding Celestica's design pipeline and deepening customer engagements, which increases revenue visibility and improves per-customer revenue potential.
See why 165 investors see Celestica as 31% undervalued.
Result: Fair Value of CA$677.38 (UNDERVALUED)
Still, the whole Celestica story leans heavily on a few hyperscaler customers and the CCS segment, so any slowdown or program hiccup could quickly puncture that 31% undervalued narrative.
Find out about the key risks to this Celestica narrative.
Another View On Celestica’s Valuation
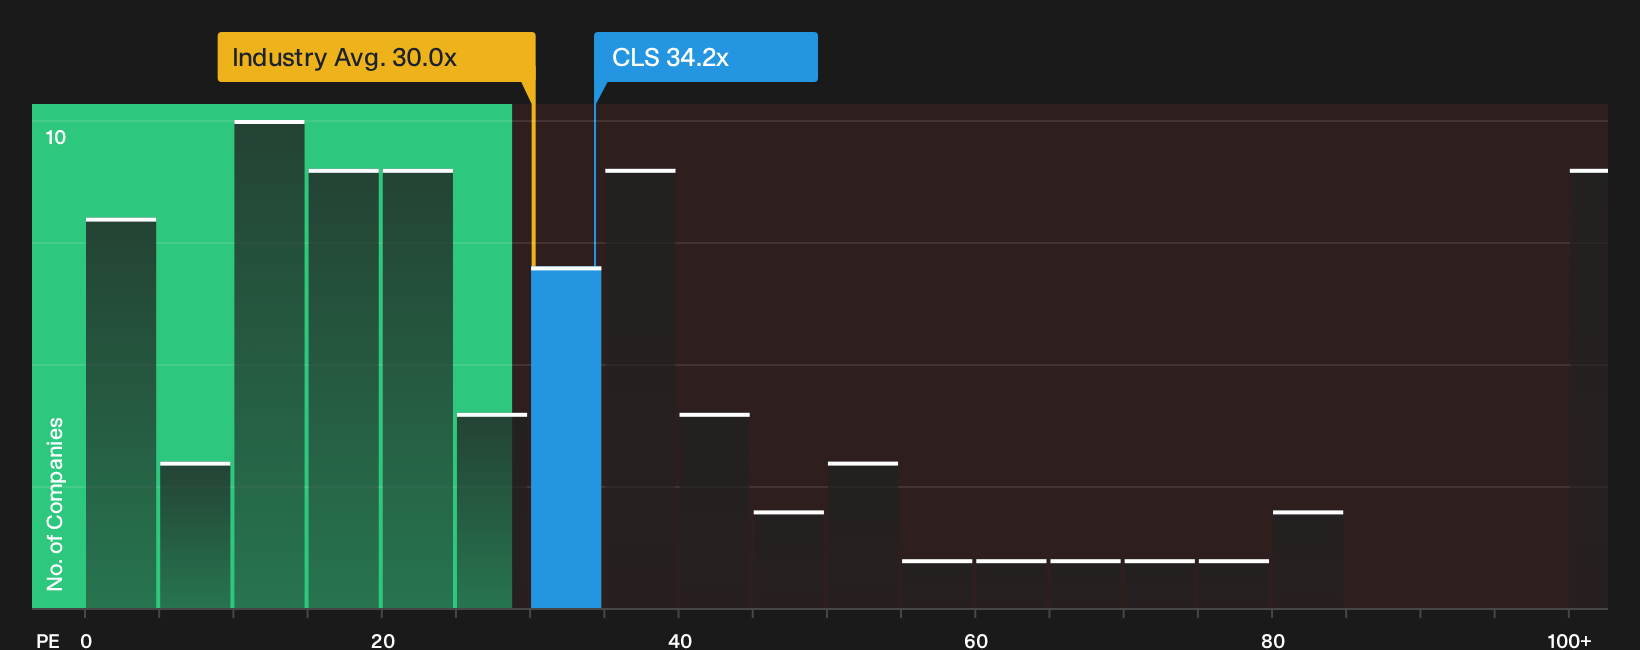
The story looks very different once you move away from fair value estimates and focus on what the market is already paying for earnings. Celestica trades on a P/E of 34.2x, compared with about 30x for the wider North American electronic group, and an estimated fair ratio of 50.5x. That mix of higher than peer pricing but lower than the fair ratio points to a stock where expectations are already high, yet some investors may still see room for repricing if growth keeps matching the current narrative. Which side of that trade do you want to be on?
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through all this, does Celestica feel like a momentum story with hairline cracks or a sturdier compounder in disguise? Act while the facts are fresh, compare the upside and downside in detail, and ground your own view in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Celestica?
Once you have a clear view on Celestica, widen the lens and pressure test your thinking against other opportunities that match your risk and return preferences.
- Target overlooked potential by running through the 9 high quality undiscovered gems that may not yet be crowded with attention.
- Prioritise resilience and support your peace of mind by checking companies in the 8 resilient stocks with low risk scores that score well on overall stability.
- Focus on financial strength by using the list of solid balance sheet and fundamentals (7 results) that highlights businesses with healthier foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com