
Snap (SNAP) Stock Looks Below Fair Value After AI Launches
Snap Inc. has rolled out new AI tools and augmented reality glasses. The bigger question for you today is whether the current share price is properly supported by its sales. With the stock drifting and sentiment mixed, investors are increasingly asking what the recent revenue base really justifies.
- Over the past 5 years, Snap’s share price has fallen 93.3%. This puts the focus squarely on whether today’s valuation still lines up with what the business delivers in sales.
- New AI driven products such as SPECS Intelligence and the Commerce Power Pack for advertisers can influence how quickly revenue grows and how efficiently those sales translate into future cash generation.
- Your read on Snap is one view; the desks covering it have another. See what analysts think Snap's shares could be worth.
The issue now is whether Snap’s current market value is well supported by its sales when you line it up against the Fair Ratio benchmark.
If you want a broader watchlist of AI driven opportunities alongside Snap, a focused stock screen is a useful second lens. You might start with 36 AI small caps.
Does Snap Look Undervalued on Sales?
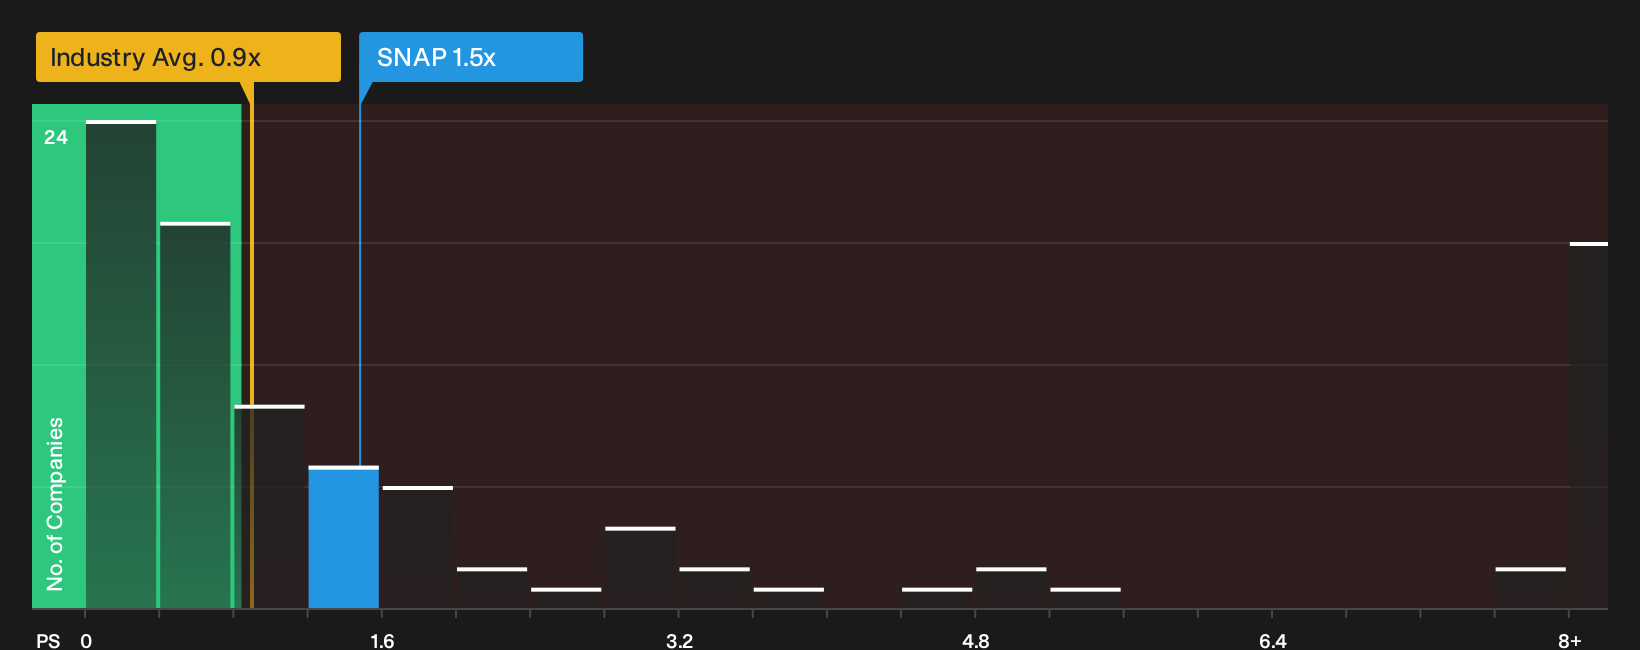
P/S is a clean way to look at Snap because earnings are still hard to read while revenue remains the main anchor for the business. On this lens, Snap trades on a P/S of 1.5x, which is above the Interactive Media and Services industry average of 0.9x but far below the peer group average of 9.3x.
The Fair Ratio model, which estimates what a stock’s P/S might be given its growth profile, margins, size and risk, points to Snap changing hands below that tailored benchmark. Because the new SPECS Intelligence and Commerce Power Pack launches focus tightly on monetising the existing user base, the current discount to that Fair Ratio suggests the market is yet to fully credit those revenue opportunities. For investors, the key question is whether today’s lower P/S versus peers is justified by execution risks or whether it marks a mispriced entry on sales. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Snap pick up where the P/S discussion leaves off by spelling out what kind of growth, margins and earnings path would need to play out for the stock to be worth materially more or materially less than today’s price on the Community page. Each storyline is structured as a thesis about Snap's fair value that you can track over time and test against how the business actually performs.
Community views on Snap split between those who see more upside in the AR and subscription story and those who are wary of the ad and engagement risks.
Bull case: 25% undervalued
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base..."
Discover why this Narrative puts Snap at 25% undervalued.
Bear case: 11% overvalued
"Snap faces the risk of long-term user stagnation or decline as younger generations shift their attention to emerging niche or decentralized platforms..."
Explore why this Narrative puts Snap at 11% overvalued.
One more Snap factor to check before you lean on the valuation
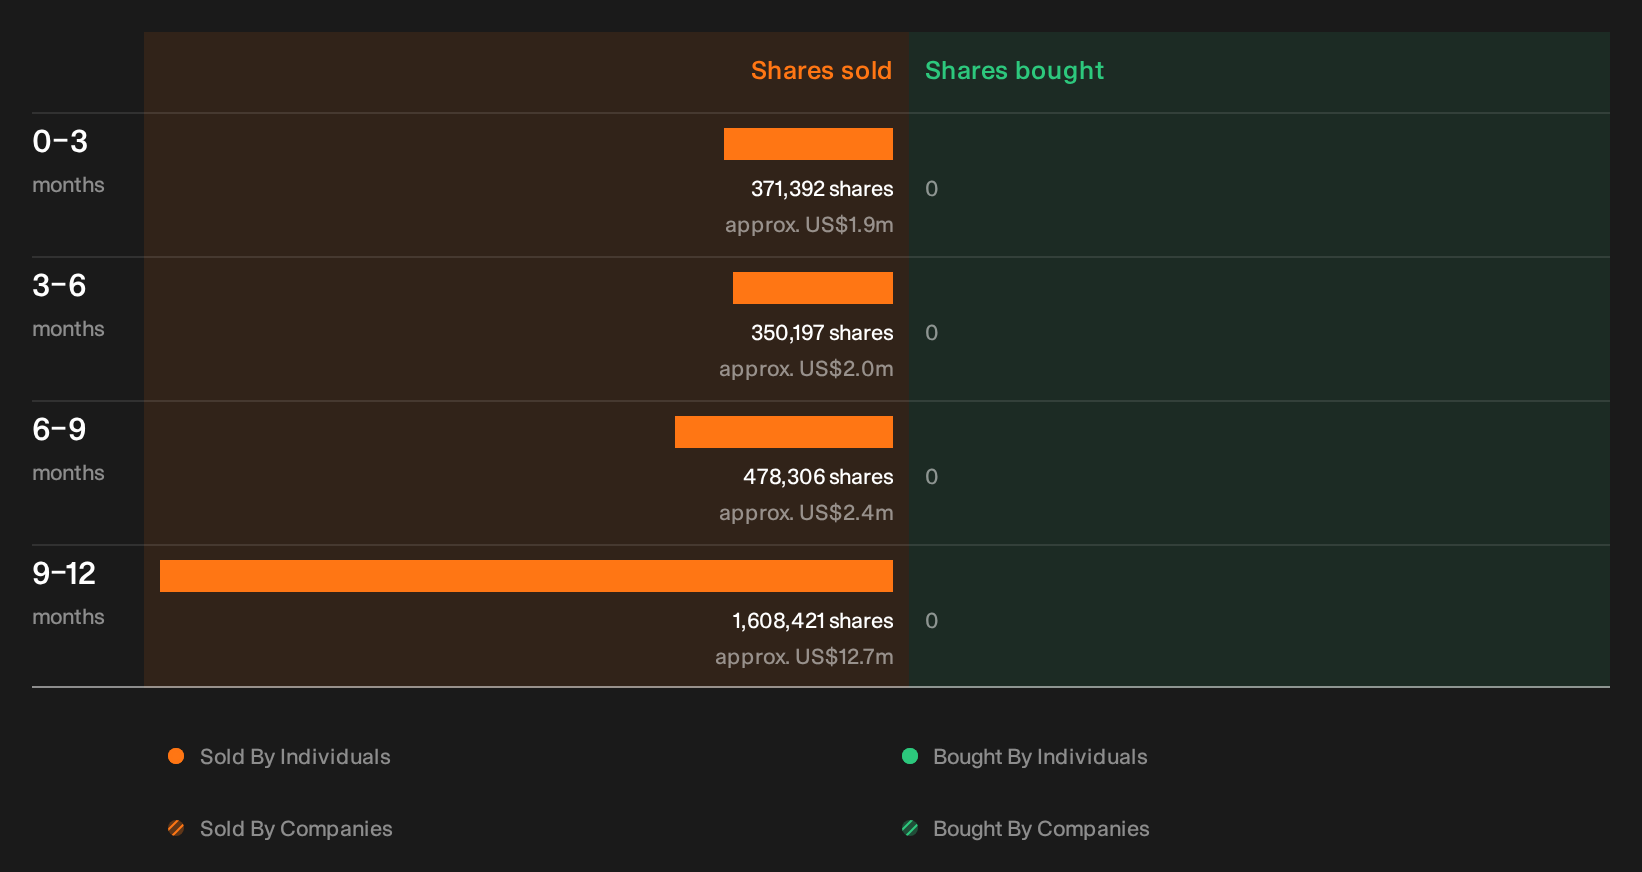
Before you treat Snap’s pricing as purely a story about sales and sentiment, it helps to know that recent insider share sales have been flagged by our checks, with the specifics still for you to examine. See the recent insider selling flagged for Snap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com