
Is SaizeriyaLtd (TSE:7581) Fairly Valued After Its Recent Pullback?
SaizeriyaLtd (TSE:7581) has drawn fresh attention after recent trading left the share price at ¥6,410. The stock is down over the past week and month but higher over the past 3 months.
Short term momentum for SaizeriyaLtd has cooled, with the share price down 12.67% over the past month. However, the 16.97% year to date share price return and 29.73% one year total shareholder return point to an uptrend that investors are now reassessing in light of shifting growth expectations and perceived risks.
Scan how SaizeriyaLtd compares with other consumer stocks showing strong price action on our hand picked list of 75 high quality undiscovered gems to see what else is moving.
SaizeriyaLtd has cooled after a strong run, which leaves you weighing two options: lean into the pullback now, or wait and hope the valuation math offers a cheaper entry ahead.
Price-to-Earnings of 26.1x: Is it justified?
Valuation on SaizeriyaLtd hinges on what investors are willing to pay for its earnings, and at a P/E of 26.1x the market is pricing the stock above the broader JP Hospitality industry on this metric while still below its closest peer group average.
The P/E ratio compares the current share price to earnings per share and gives a quick shorthand for how much you pay for each unit of profit. For a restaurant operator with established operations across Japan and parts of Asia, this matters because it reflects how strongly the market is pricing in future earnings progress relative to current profitability.
Here, the 26.1x P/E is higher than the JP Hospitality industry average of 22.1x. This signals that investors are assigning a richer tag to SaizeriyaLtd than to the sector overall. At the same time, that valuation looks restrained next to the peer average P/E of 58.8x, which is far higher. The stock also trades close to an estimated fair P/E of 27.9x, a level the market could move towards if sentiment aligns with that fair ratio estimate.
Explore the SWS fair ratio for SaizeriyaLtd.
Result: Price-to-Earnings of 26.1x (ABOUT RIGHT)
Still, the SaizeriyaLtd story can break if consumer demand softens in key Asian markets or if cost pressures squeeze profitability faster than revenue grows.
Find out about the key risks to this SaizeriyaLtd narrative.
Another view on SaizeriyaLtd’s value
The P/E picture only tells part of the story. Our DCF model values SaizeriyaLtd at about ¥12,690 per share, which is roughly double the current ¥6,410 price. That points to a stock the cash flow model sees as undervalued, even with only moderate growth forecasts baked in.
DCF outputs can swing a lot when you tweak growth or discount rate assumptions. The real question is whether you think those long term cash flow inputs are conservative enough or still too optimistic for SaizeriyaLtd.Look into how the SWS DCF model arrives at its fair value.
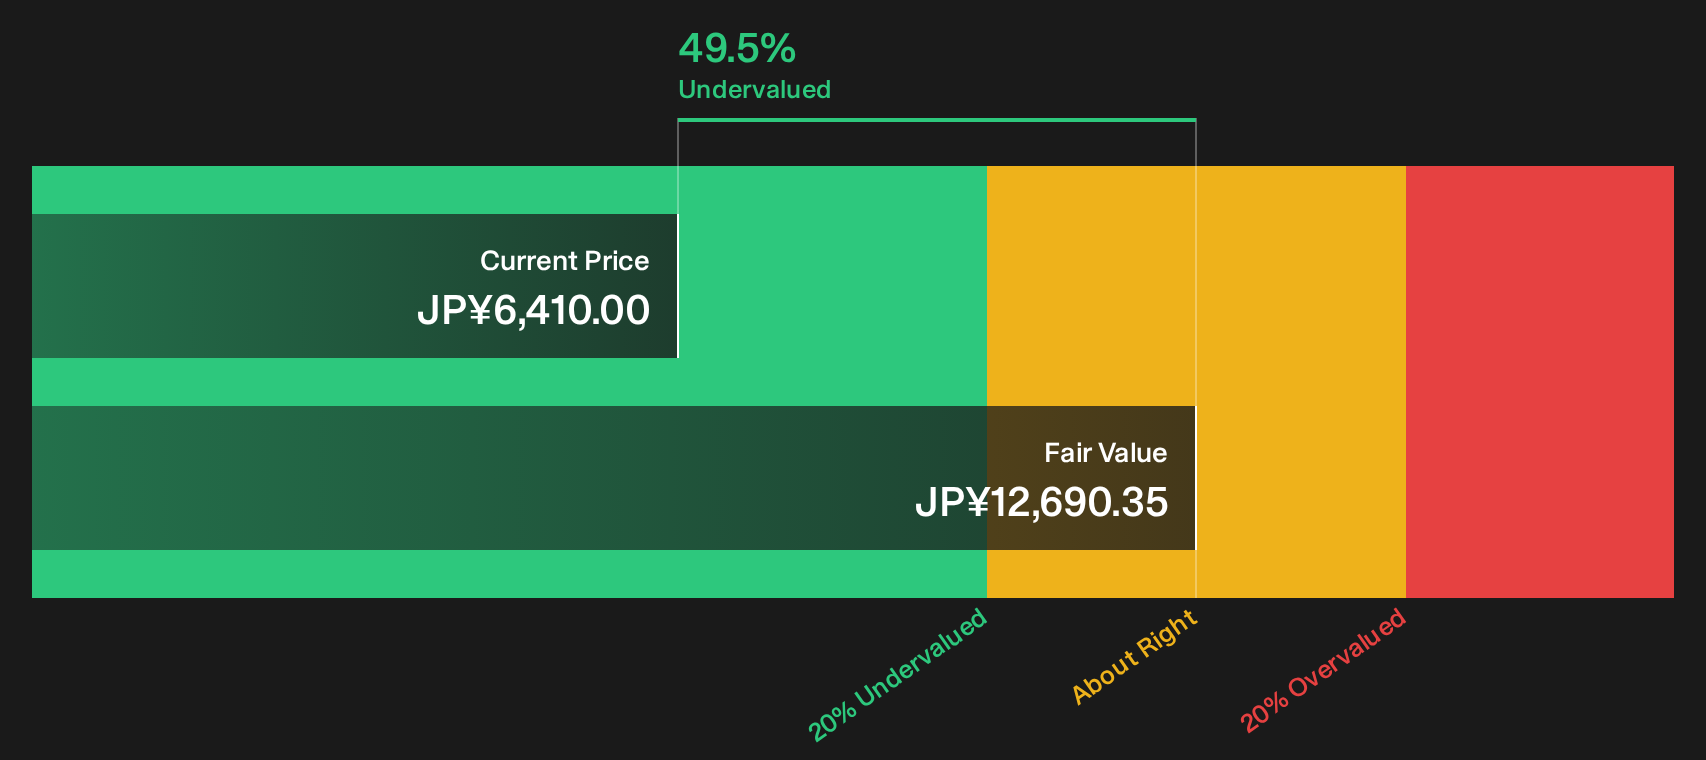
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SaizeriyaLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about SaizeriyaLtd after all of this. Check the numbers, weigh the upside against the weak spots, then base your own call on the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SaizeriyaLtd?
If SaizeriyaLtd has you thinking more broadly about opportunities, do not stop here. A wider watchlist can help you spot themes before everyone else.
- Target dependable compounding by reviewing companies with a history of paying investors from a pool of 14 dividend fortresses that focus on income strength.
- Zero in on quality at a discount by scanning a curated set of 17 high quality undervalued stocks that combine fundamentals with valuation support.
- Protect your downside first by combing through 21 resilient stocks with low risk scores that score well on resilience and balance sheet stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com