
Is ExlService Holdings (EXLS) Priced Right After Its AI Push?
ExlService Holdings has seen its share price move around over time, and with the stock recently trading at US$35.15, the question is how well that level lines up with the earnings the business is generating. For anyone tracking ExlService today, the key issue is whether the current valuation still makes sense given how its profit engine is evolving.
- Over the past 5 years the stock has returned 41.8%, which puts real weight on the question of whether the present earnings base can support where the share price now sits.
- The new "Go Beyond" brand launch and the acquisition of iMerit signal a push deeper into data and AI services that can influence how investors think about ExlService's long term earnings potential and the timing of future cash flows.
- Your read on ExlService Holdings is one view; the desks covering it have another. See what analysts think ExlService Holdings's shares could be worth.
The issue now is whether ExlService's current earnings justify the price that investors are paying for the stock today.
To see how ExlService Holdings compares with other data and AI plays on the market, it can help to line it up against 36 AI small caps.
Does ExlService Holdings Look Fairly Valued on Earnings?
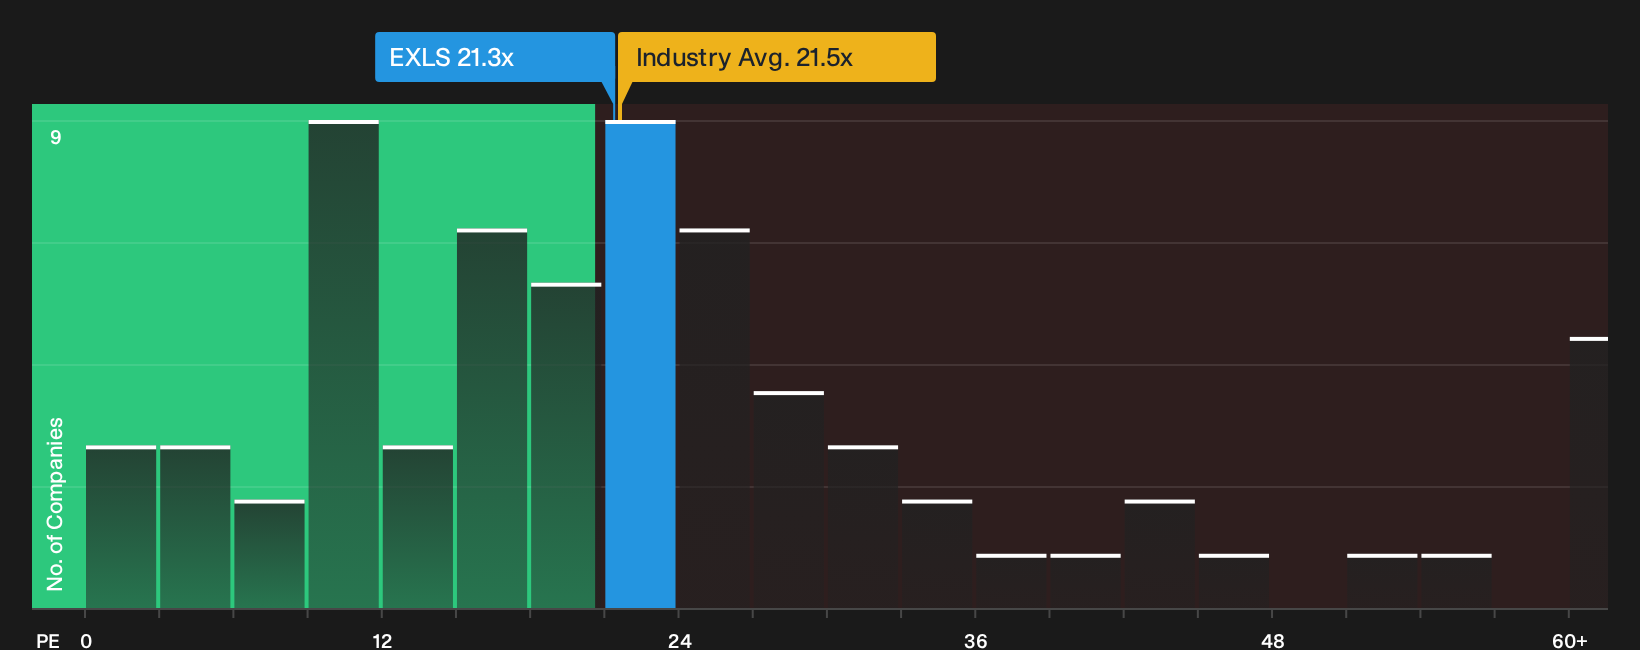
The P/E ratio fits ExlService Holdings well because earnings are still the main anchor for how the business is being priced. At the recent share price, ExlService trades on a P/E of about 21.3x, which is very close to the Professional Services industry average of roughly 21.5x. Against a peer group that averages around 14.0x, the stock carries a clear premium, so the market is assigning a higher price for each dollar of profit than for many other data and AI focused platforms.
The Fair Ratio model, which adjusts for factors like growth profile, margins and risk, also points to a level near where ExlService currently trades. Because the new Go Beyond brand launch and iMerit acquisition sharpen the story around data and AI, the market appears comfortable paying this multiple that lines up with the Fair Ratio rather than the cheaper peer group. That leaves the stock priced in a way that seems broadly in line with what this framework suggests. Explore the numbers behind ExlService Holdings's P/E valuation.
The ExlService Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the valuation puzzle around ExlService Holdings' current P/E and turn it into explicit, testable assumptions about future growth, profitability and earnings that would need to hold for the stock to be worth meaningfully more or less than today. They sit on the Community page rather than within a single model output, and each one lays out the earnings and margin story it is using so you can later compare those inputs with the actual numbers as they arrive.
Community views on ExlService split sharply between those who see an AI powered runway and those who think the valuation already reflects more than enough optimism.
Bull case: 19% undervalued
"ExlService's deep domain expertise and proprietary data platforms enable rapid development of differentiated AI solutions, creating high barriers to entry and competitive advantages..."
Discover why this Narrative puts ExlService Holdings at 19% undervalued.
Bear case: 91% overvalued
"Five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited..."
Explore why this Narrative puts ExlService Holdings at 91% overvalued.
One more angle on ExlService Holdings that could change the story
Price tags and profit lines only tell part of the story for ExlService Holdings, because the people steering the ship and the way they are rewarded can heavily shape what happens next. See who runs ExlService Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com