
West Pharmaceutical Services (WST) Could Be 10% Undervalued On GLP 1 And Annex 1 Demand
West Pharmaceutical Services event puts growth drivers and risks in sharper focus
West Pharmaceutical Services (WST) is back in the spotlight after a cyber incident weighed on its West Vantage segment, just as regulatory Annex 1 sterility upgrades reshape demand for its injectable containment and delivery products.
The same business now faces tariff related cost inflation that could influence margin trends, even as high value products and expanding biologics exposure frame the longer term opportunity investors are trying to price in.
At a share price of US$362.31, West Pharmaceutical Services has logged a 31.08% year to date share price return and a 42.61% total shareholder return over the past year, while the 3 and 5 year total shareholder returns are mildly negative. This suggests that near term momentum has picked up even as longer term returns remain muted.
Spot 30 resilient stocks with low risk scores that, like West Pharmaceutical Services, aim to balance operational hurdles such as cyber incidents and tariffs with resilient products and solid financial footing.After a sharp reset in longer term returns and a strong rebound over the past year, the main concern for West Pharmaceutical Services now is the price tag. Does the current valuation still leave enough upside for new buyers?
Most Popular Narrative: 10% Undervalued
Against the last close of $362.31, the most followed valuation narrative pegs West Pharmaceutical Services at a fair value of about $404, which puts the current debate squarely on how durable its high value product story really is.
The continued growth in GLP-1s, which made up about 7% of total revenues in the first quarter, and the company's ability to capitalize on significant opportunities in this market could drive revenue and earnings growth.
The increase in demand and the transition to higher-margin HVP components, supported by approximately 340 Annex 1 projects, is likely to positively impact both revenue and net margins due to a favorable mix shift.
See why 13 investors see West Pharmaceutical Services as 10% undervalued.
That narrative leans on a fair value estimate of about $404 built using a 7.83% discount rate, compared with West Pharmaceutical Services' current market value of around $25.5b and reported net income of $564.9m.
Analysts behind this view fold in forecast revenue growth of 6.4% a year and an expected profit margin of roughly 20.3%, with earnings projected to reach $812.6m by around July 2029, while still assuming a P/E in the low 40s.
They also assume share count falls by just over 2% a year, which supports per share metrics, and they point to the swing in recent total returns, with 1 year gains of 42.6% contrasting with weaker 3 and 5 year outcomes, as a sign that sentiment has only recently turned more optimistic.
Set against those upside drivers are clear pressure points, including tariffs that could squeeze operating margins, constraints in high value component capacity as demand clusters in specific facilities, and execution risk around exiting continuous glucose monitoring contracts while backfilling with GLP 1 and drug handling volumes.
On top of that, the management team is relatively new with an average tenure of 1.9 years, and restructuring and leadership changes, including a CFO transition, sit in the background as potential sources of volatility for West Pharmaceutical Services if the shift toward higher margin business lines does not go smoothly.
Result: Fair Value of $404 (UNDERVALUED)
Still, execution risk around exiting continuous glucose monitoring contracts and exposure to higher tariffs could unsettle the West Pharmaceutical Services story if margins falter.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another view on West Pharmaceutical Services valuation
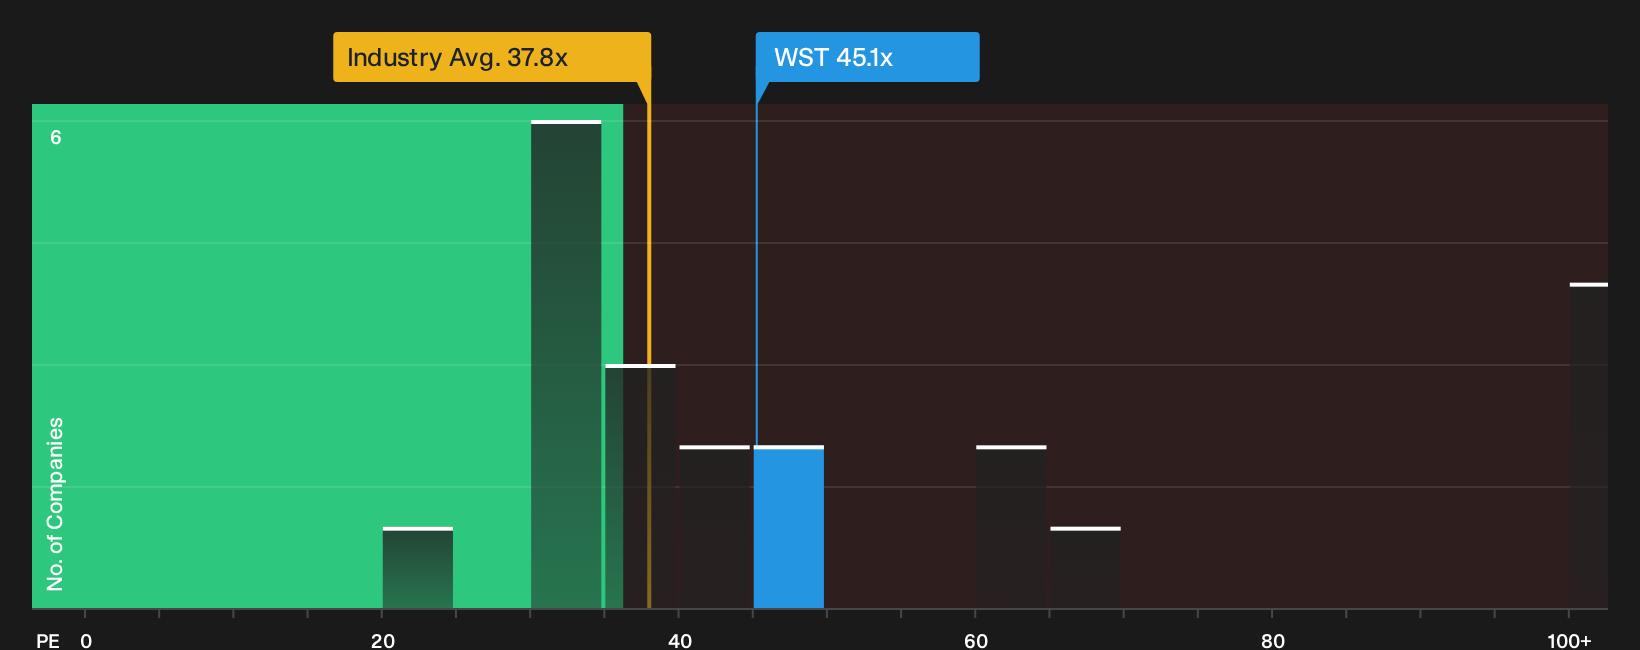
The first narrative leans on earnings forecasts and a fair value near $404. On a simple P/E lens, West Pharmaceutical Services looks expensive, trading around 45.1x earnings versus 37.8x for the global Life Sciences industry and 34.3x for peers, while the fair ratio sits at 23.6x. That gap points to meaningful valuation risk if sentiment cools or growth expectations get re-rated.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of risks and rewards around West Pharmaceutical Services feels finely balanced, consider acting while sentiment is still forming and review the numbers yourself. To understand what is driving the optimism around the upside case, take a closer look at the 2 key rewards
Looking for more West Pharmaceutical Services style investment ideas?
If you want to stress test your thinking beyond West Pharmaceutical Services and avoid leaving potential opportunities on the table, put the Simply Wall St Screener to work now.
- Target quality at a discount by scanning a focused set of attractively priced businesses through the 33 high quality undervalued stocks.
- Build a steadier income stream by lining up companies that prioritize reliable payouts using the 6 dividend fortresses.
- Fortify your watchlist with businesses that carry less financial strain by filtering for strong balance sheets via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com