
Hesai Group (HSAI) Expands Its Lidar Reach, Is Margin Pressure Already Priced In?
Hesai Group (NasdaqGS:HSAI) is in the spotlight after expanding further into lidar, robotics, and spatial AI, securing fresh design wins with major automakers while tighter margins begin to pressure overall profitability.
Recent trading shows pressure building on Hesai Group’s share price, with a 1-day share price return that declined 2.34%, a 7-day move down 4.56%, and a 30-day slide of 11.28%. The year-to-date share price return has fallen 31.40%, and the 1-year total shareholder return is down 43.13%. However, the 3-year total shareholder return remains positive at 59.61%, suggesting longer term holders have still seen meaningful gains despite the recent pullback and rising concern over margins.
Scan what other lidar, robotics, and spatial AI players look like beside Hesai Group by comparing the hand picked 95 robotics and automation stocks in a single view.
After a sharp pullback in Hesai Group, despite revenue and net income growth, the real tension sits between margin pressure and potential future lidar wins. Does that balance still appear attractive for new buyers at this price, based on valuation alone?
Most Popular Narrative: 39% Undervalued
Hesai Group last closed at $16.52, while the most followed narrative pegs fair value at $27.07, which highlights a sizable gap between the story implied by the price and the story implied by the cash flows.
Hesai’s valuation is increasingly supported by tangible execution and forward visibility rather than expectations alone. Following strong 4Q25 results, management reiterated a confident outlook, underpinned by stable gross margins driven by scale efficiencies and ongoing technology-led cost reductions. This combination is critical because it signals that growth is not coming at the expense of profitability, but alongside improving unit economics.
See why 24 investors see Hesai Group as 39% undervalued.
Result: Fair Value of $27.07 (UNDERVALUED)
Still, that story around Hesai Group can break if geopolitical friction restricts overseas demand, or if pricing pressure erodes the margin profile investors are leaning on.
Find out about the key risks to this Hesai Group narrative.
Another Look At Hesai Group’s Valuation
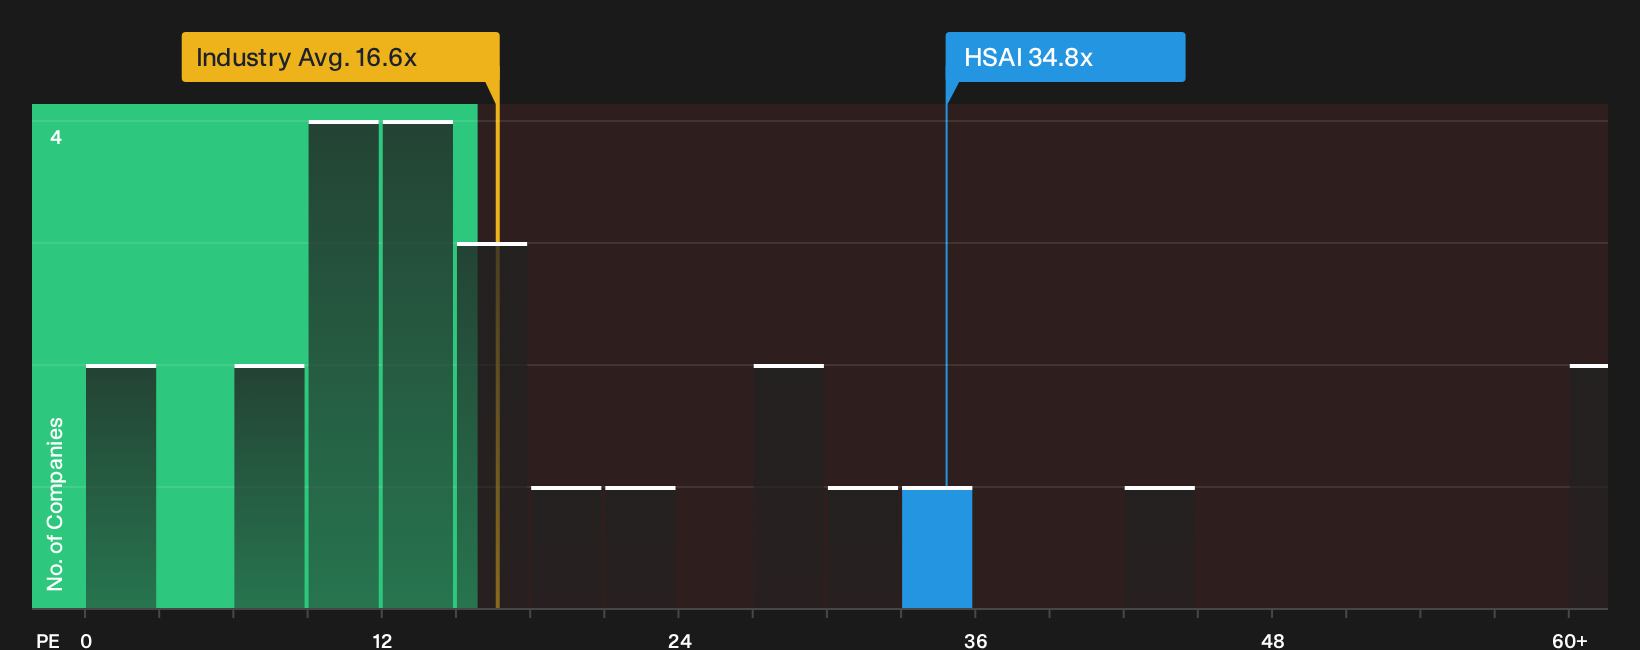
The first view leans on fair value at $27.07, yet Hesai Group currently trades on a P/E of 34.8x. That is higher than the US Auto Components industry at 16.6x, peers at 14.8x, and even the 32.9x fair ratio. Paying that kind of premium raises the question of how much upside is already priced in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Hesai Group’s valuation and risk profile can feel confusing, so move quickly, sift through the data, and test the balance yourself with 4 key rewards and 1 important warning sign.
Looking for more Hesai Group sized investment ideas?
If Hesai Group is on your radar, do not stop there. Use the same disciplined lens across fresh opportunities that might suit your watchlist next.
- Target potential value opportunities by scanning the 33 high quality undervalued stocks to find candidates that combine quality fundamentals with prices that may not fully reflect underlying business strength.
- Strengthen your income stream by reviewing the 6 dividend fortresses to explore companies offering higher yields with an emphasis on resilience.
- Protect your downside by filtering through the 30 resilient stocks with low risk scores to identify businesses with steadier profiles when volatility picks up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com