
How Buyback Plan Will Impact Anterix Stock Investors
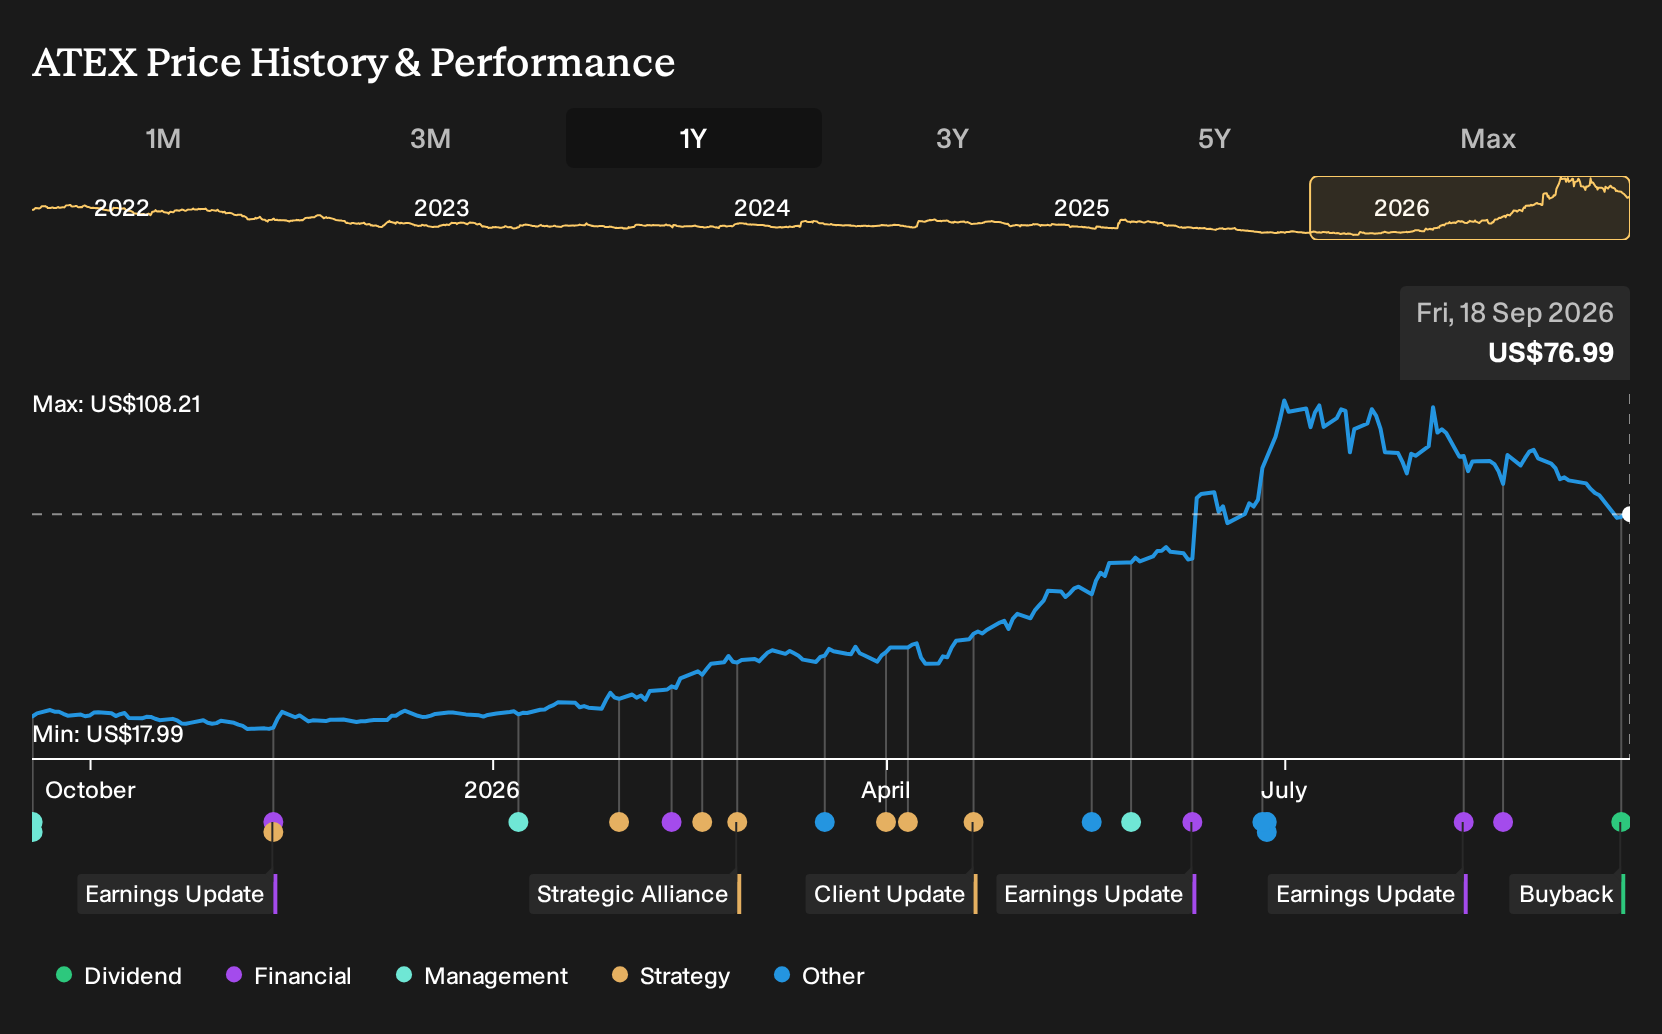
- Anterix announced that its board approved a share repurchase plan and, on September 18, 2026, unveiled authorization to buy back up to US$250 million of stock through September 22, 2029.
- The multi year buyback program commits a sizeable portion of capital, which directly affects share count assumptions and signals how management currently prioritizes capital allocation over alternative uses, such as spectrum development or new utility partnerships.
- We will examine how Anterix's investment narrative, centered on long term utility spectrum monetization, may shift in light of this sizable buyback authorization.
See how Anterix's buyback compares with other capital allocation stories by reviewing a curated list of 33 high quality undervalued stocks that may be preparing for their next move.
Anterix Investment Narrative Recap
To own Anterix, you need to believe its 900 megahertz spectrum can keep finding long term utility partners that sign meaningful leases, then actually deploy networks that turn into recurring service revenue. The newly approved US$250 million buyback does not change that basic bet. The near term swing factor still looks like execution on new contracts and deployments.
The biggest risk remains operational and regulatory. Delays in FCC progress on 10 megahertz expansion, slower clearing of incumbents, or utilities opting for alternative connectivity could all choke the pace of monetization. The repurchase program mainly affects share count and capital allocation, not those core business hurdles.
The most relevant announcement for this discussion is the board’s September 16 authorization of the buyback plan, followed by the September 18 disclosure of the US$250 million program running through September 22, 2029. That is a long window. The actual effect on per share metrics depends on how consistently it is used over time.
For you as an investor, the key question is how this interacts with Anterix execution on grid modernization opportunities and spectrum leasing. A long dated repurchase plan can support per share figures if the business converts more pilots into full deployments and continues clearing licenses efficiently. If adoption or FCC outcomes disappoint, the operational risks flagged earlier still sit in front of the buyback story.
Anterix's current analyst setup points to revenues of US$6.9 million and earnings of US$935.0 thousand by 2028. This outlook is built on an assumed 5.3% yearly revenue growth rate and a move from US$95.6 million of earnings today to that much smaller profit figure, which represents a very large earnings decline rather than an increase.
Uncover why Anterix's fair value indicates a 28% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view leans on FCC progress as a catalyst. The most optimistic analysts were already modeling faster 8.2% yearly revenue growth and roughly US$7.5 million of sales by 2028, with earnings near US$1.0 million, before this Anterix buyback surfaced. That crowd may now rethink, and you can weigh how their story could shift.
Explore 2 other Anterix fair value estimates, including one that suggests as much as 46% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Anterix research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Anterix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Anterix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Anterix?
If the Anterix story has sharpened your thinking about capital allocation and risk, you might want to broaden the watchlist with other opportunities that fit different roles in a portfolio. The Simply Wall St Screener can help you filter for specific traits rather than chasing headlines.
- If resilience matters most to you, consider reviewing 30 resilient stocks with low risk scores that aim to keep drawdowns in check when sentiment turns.
- If balance sheet strength is your first filter, scan the list of solid balance sheet and fundamentals (23 results) to see which companies pair financial flexibility with cleaner fundamentals.
- If you want potential mispricing ideas, use the 16 high quality undiscovered gems and focus on businesses the market may not be paying close attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com